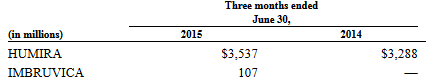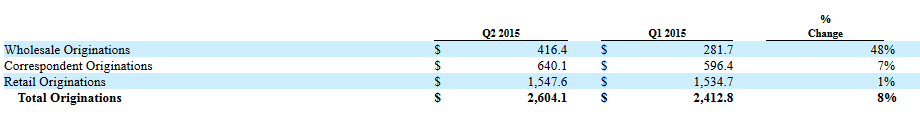Skip to content

Week 223: Playing the Volatility

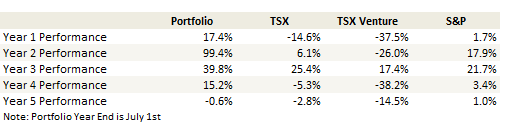
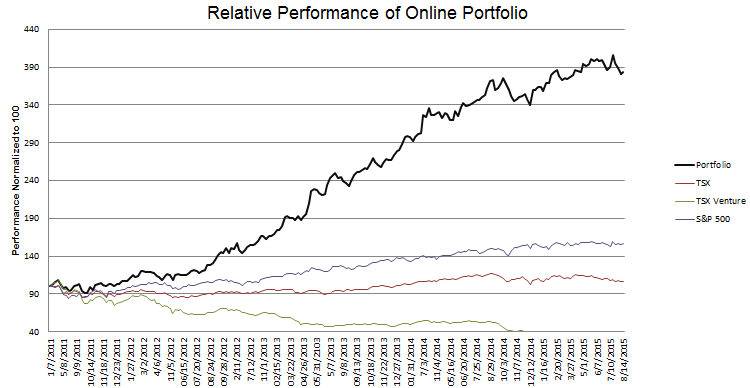
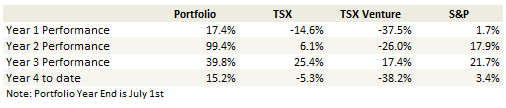
Portfolio Performance
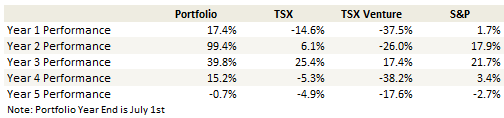
week-223-yoyperformance

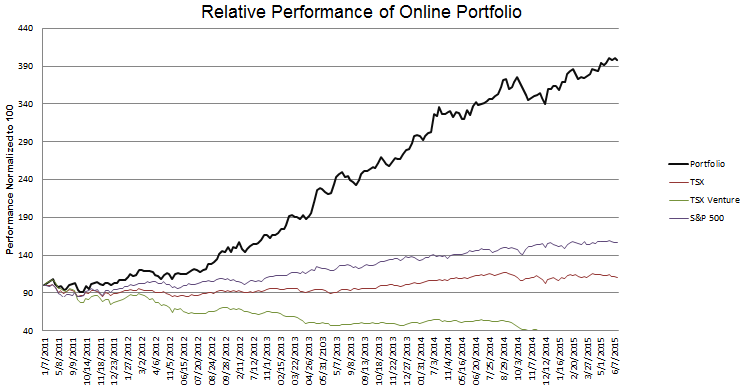
week-223-Performance

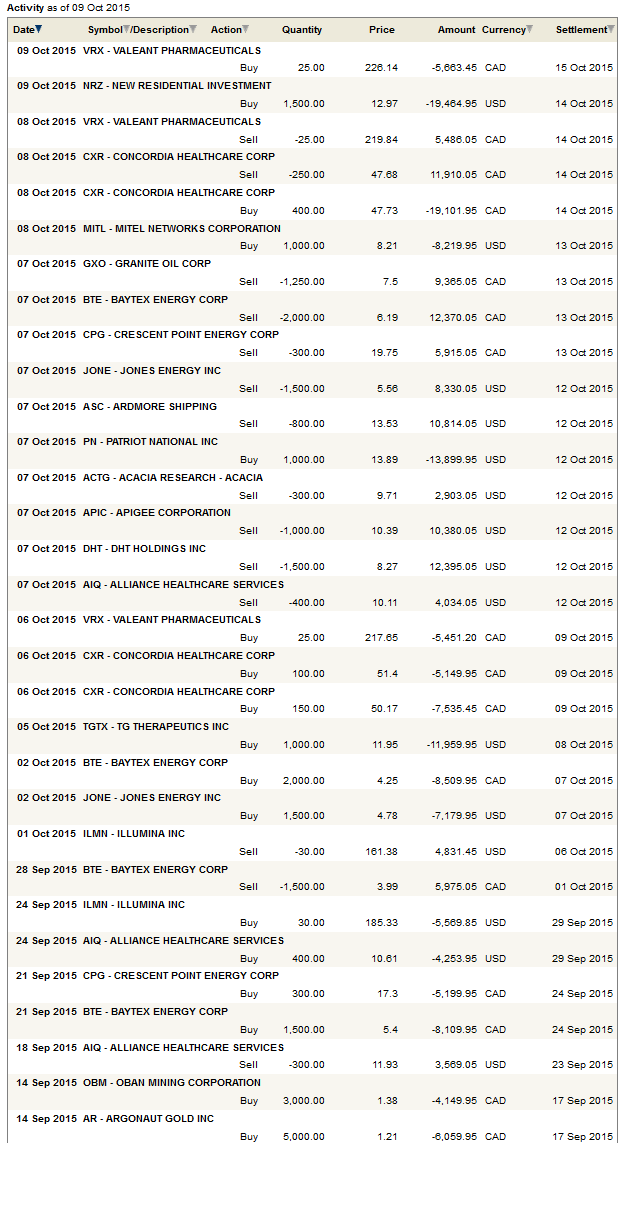
See the end of the post for the current make up of my portfolio and the last four weeks of trades

Monthly Review and Thoughts

I was on vacation for three of the past four weeks, so my portfolio changes have beeen minimal.  It was nice time away but the timing was unfortunate; the market swooned but bounced back before I got back.  There were plenty of opportunities I missed out on.

As it were, the only two I was able to capitalize on were Mitel Networks and New Residential.  In both cases I had old stink bids that got hit (a little over $6 for Mitel and $12.50 for New Residential).  But even in these cases, the positions I ended up with were much smaller than I might have had I been actively watching the action.  I’ll talk about Mitel a little later on.

I haven’t been tweeting a lot either, but I can’t attribute that entirely to being away.  I find my mind hesitating on any conclusion.  Its very difficult to tweet when each comment requires a couple of caveats a maybe and at least two possible scenarios.  There are only 140 characters.

David Tepper was on CNBC a few weeks ago sharing his thoughts about the current state of the market (click here for one of the clips).  Most of the summaries I’ve read focused on his comments about the S&P possibly going to 1,800.

What I took from the interview was uncertainty.   The direction of money flows are criss-cross, whether the tide is still coming in or starting to go out is more uncertain then it has been in recent years. When quantitative easing was in full swing there was a clear easing of liquidity, now its much more muddled.  And Tepper isn’t really sure where it will all settle out.  It might be higher, but he seemed to suggest that he thought it was more likely to resolve itself lower.

If David Tepper isn’t sure of path of least resistance, I bet you can say the same for the market.  And that to me says we are in for volatility.  Which is what we are getting.

If we are going to be in market where directionality is wanting and volatility rules then the right approach is to not believe too much too fast.  Sell the rallies and by the dips.

If I’ve done one thing right in the last four weeks it is that I have manifested these convictions in my trades.  I sold out of a lot of positions as the market rose last week.  I will be ready to buy them back if the market falls back far enough.  Without QE, without China, and without sensible leadership from any of the market groups, I think we simply flounder around aimlessly, at worst with a downward bent.

A Position in Mitel

Mitel develops and installs unified telephone systems for businesses.  They also provide white label back-end services and software for carriers so they can offer their own telephone products to business.

With Mitel’s legacy business, called the “premise” segment, they install a telephone platform on location, including the phones, connections and back-end.  Upon sale of a telephone system Mitel generates revenue from upfront hardware and software sales, and a small amount of recurring revenue for maintenance and support.

The premise business has been shrinking as companies migrate toward a cloud solution.  The cloud system Mitel provides is similar to premise in terms of functionality: the business gets a telephone platform that operates and connects its devices, provides unified voice mail, conferencing, all of the functionality you’d expect.  But the system runs through the cloud, so the hardware component is mostly absent.

With the cloud product Mitel receives recurring revenue for each end-user that is hooked up.  For their retail customers (those who purchase cloud services directly from Mitel) they receive around $45/month revenue per user.  For their wholesale clients (carriers who resell the service as their own) they receive somewhat less, but at a much higher margin as they are only providing the software and support.

In April Mitel expanded into a third segment, mobile, with their purchase of Mavenir for $520 million. Mavenir offers a 4G LTE solution to telecom carriers.  4G LTE is the next evolution of telecom transmission.

4G LTE is slowly being adopted by carriers for its functionality and costs. With respect to functionality, 4G LTE allows for something called Rich Communication, which makes it easier to do things like video calling, group messaging or video streaming over mobile.  As well 4G can deliver voice over the LTE connection rather than the legacy voice network which is expected to improve call quality.

For carriers the cost advantage is that once installed 4G LTE uses less bandwidth, which limits the requirements of additional spectrum that they have to buy.

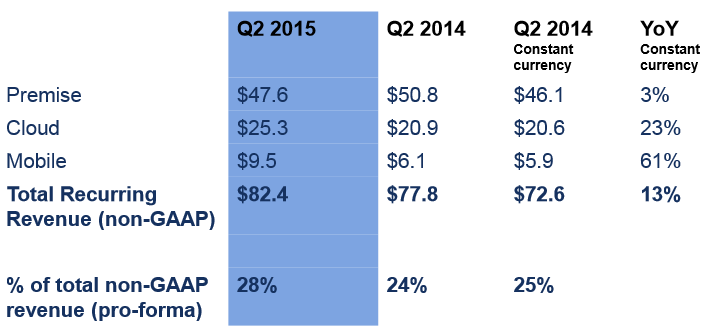
Mitel’s shift to cloud and mobile means that the overall business model is shifting towards one of  recurring revenue through subscription/licenses.  Below is a snapshot of recurring revenue growth for each of the segments.
recurringrevs

The overall premise business is shrinking by about 5% to 8% per year as companies migrate to a cloud or hybrid cloud/premise solution.  The cloud business has been growing at 20%. Mavenir grew at 30% in the second quarter.

Overall the company has been growing only nominally as the premise business, which makes up 75% of revenue, declines have overshadowed the smaller, growing cloud and mobile businesses.  But this will change as the other two segments become larger.

The early indications are that the Mavenir acquisition is going well.  Second quarter revenue for the mobile segment (which is essentially Mavenir), was $45 million.
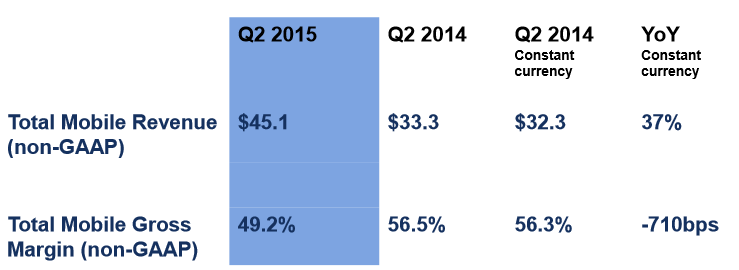
mobilerevs

On both the second quarter conference call and at subsequent conferences Mitel has noted an acceleration in Mavenir’s wins since they have been acquired.   The concern of many carriers with respect to choosing the Mavenir solution was that it was a small company with limited resources and a small global footprint.  Mitel’s acquisition has alleviated those concerns.  At the time of the acquisition Mavenir had 17 footprint wins with carriers.  Since April Mitel/Mavenir have won 10 more footprints including 1 major cable company in the United States.

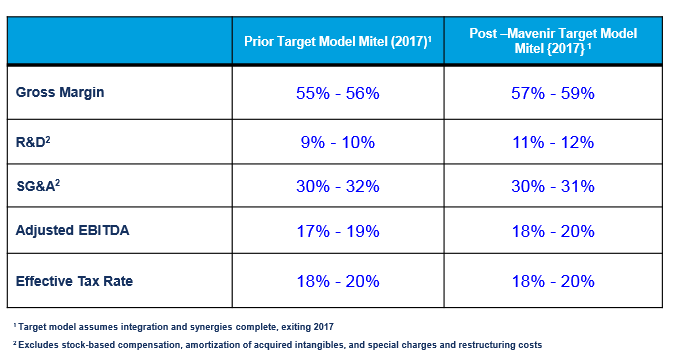
Mitel provides the following roadmap for earnings in 2017.
earningsroadmap

If I use the above roadmap and assume that Mitel can continue 20% growth in both the cloud and mobile business and that the premise business declines at 5%, I can see Mitel earning over a dollar in 2017.

I only wish I would have bought more of the stock when it was in the $6’s.  The timing was unfortunate.  As it is, I am contemplating adding to the position if it dips back into the $7’s.

There are a couple of decent Seeking Alpha articles on Mitel here and here.

Wading into the Biotech Controversy

I decided to jump in with the sharks and take a position in Concordia Healthcare.  I also took a very small position in Valeant Pharmaceuticals.

Concordia has a similar business model to its much larger competitor Valeant.   Its a roll-up strategy.  In the last year they have acquired three pharmaceutical companies: Donnatal, Covis and AMCo.  In the process they have increased their revenue from a little over $100 million in 2014 to over $1 billion in 2016.  Below is a table of the companies acquisition pre-AMCo.

acquisitions

The stock has been hammered as Valeant has been singled out for pushing through price increases on many of its newly acquired drugs.  The comparison is not unwarranted as Concordia has much the same strategy as Valeant, raising prices on newly acquired drugs where the market has been inelastic.

In both the cases I haven’t been able to get a solid handle on the extent of the price increases.  Articles point to 20% plus increases in some drugs.  Others go on to point out that these list price increases are not representative of what is actually paid, and that the actual price increases are more modest.

Valeant is also suffering from its own opacity.  There is an excellent four part blog series that I would recommend reading before investing in either Concordia or Valeant.  It is available here.  The author illustrates numerous examples where Valeant had questionable disclosures and raises some questions about the performance of their acquisition post-integration. Most important though, it provides an overview of how to think about the valuation of both companies that I found extremely helpful.

Concordia is not quite as opaque as Valeant, though some of this is a function of its size.  Until very recently the company only owned a few drugs and depended heavily on Donnatal for its revenue.  So its not too hard to separate the contributing parts.

Unlike Valeant, I don’t see evidence that Concordia’s acquisitions have underperformed after being acquired. Donnatal, being Concordia’s largest acquisition prior to 2015, is illustrative.  Donnatal was purchased in May of 2014.  In 2013 Donnatal had revenue of about $50 million.  In 2014 Donnatal had revenue of $64 million.  In 2015 Donnatal is expected to bring in between $87-$92 million of revenue.

Of course some if not most of that revenue increase was due to price increases.  How reasonable are future price increases on newly acquired drugs?  Without a doubt the potential has diminished.  But I think that as the front page headlines fade the reality will appear less dire than it does now.  Keep in mind that the price increases are not comparable to the 5000% jack-up by Turing Pharmaceuticals an other aggressively managed hedge-fund like pharma providers.  Meanwhile Concordia is down 50% in the last month; surely the more robust expectations have been priced out of the stock.

The bottom line is that both Valeant and Concordia have real negatives but they have also experienced really dramatic falls in valuation.  Concordia was a $100 stock (Canadian) a few months ago.  Valeant was over 30% higher.

I can’t take a big position in Valeant because I can’t really figure out how well its doing and I think the difficulty of performing their roll-up strategy  increases with size.  With Concordia performance is easier to evaluate and they are still small enough to be able to find interesting acquisitions and fly under the radar of the news. I think the question is more one of: are the negatives priced in?  And I think there is a reasonable chance that is the case.

A Few Small Bets on Gold Stocks

Gold stocks have been so beaten up that it just had to turn at some point soon.

I also thought I saw was kind of a win-win situation with respect to the September rate hike decision.  Either the Fed was going to hike rates, which would mean the event had finally passed and the stocks could stop pricing in its inevitability, or they wouldn’t, in which case the legitimate question would resurface as to whether we are really passed the QE-phase.

Additionally, there has been a shift quietly occurring in the gold sector.  Many producers are getting their costs under control.  This has been helped by improving currencies for non-US based producers, by lower energy costs and by lower construction costs.  While the market seems to have a curious focus on valuing gold companies on the price of gold, which has been stagnant to down, the margin they make have been improving.

Let’s take Argonaut for example, which is one of the companies I took a position in.  Argonaut has 155 million shares outstanding and trades at about $1.50, so the market capitalization is about $250 million.  Debt is nil and the cash position is around $50 million.  They have been improving their performance year over year.
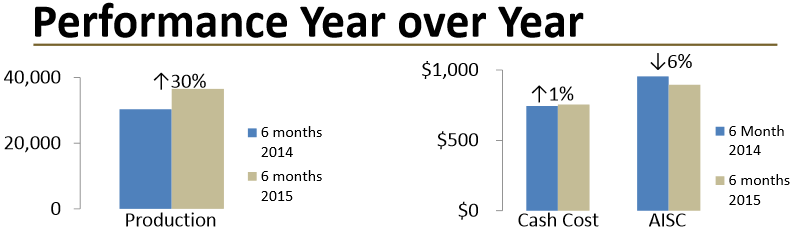
yoycomp

Argonaut produced cash flow from operations before working capital changes of $28 million in the first half of 2015 (cash flow including working capital was $38 million, but because changes in inventory are such a big and fluctuating part of a gold mining operation I think they need to be ignored).

Sustaining capital expenditures and capitalized stripping at Argonaut’s operating mines (El Castillo and El Colorada) runs at about $5 million per quarter.  So free cash (so before expansion and development capital) is around $35 million for the year.

Argonaut, and other gold producers like them, are not expensively priced at $1,100 gold.  That means there is no expectation of higher gold prices priced into them.  I think there is a reasonable chance we see higher gold prices as there is a reasonable chance that the economy continues to muddle.  These stocks are multi-baggers if that happens.

Oil

I have had some strong opinions on oil over the past few months but I don’t have a strong opinion now.  When oil was in the low $40’s I once again bet on a number of oil stocks including Crescent Point, Baytex and Jones Energy.  I went through some consternation as Goldman Sachs came out with their $20 oil call and I listened to the twitter universe decry the inevitability of a collapse in the oil price.  But in the end it all worked out, and I sold Baytex for a quick 50% gain, Crescent Point for a 40% gain, and Jones for a 20% gain.

With oil back in the $50’s I feel much more non-committal.  For one, I think that at least some of this move is due to geo-political concerns, which isn’t a firm footing to base a stock purchase.  For two, earnings season is upon us and there is at least some risk that the lack of drilling leads to downward revisions in production forecasts for companies like Baytex and Crescent Point.  And for three, pigs really do get slaughtered, so when the market gives you a big gain in a couple of months I have found it more often than not prudent to take that gain and run.

I will be a bit sick to my stomach if Baytex runs quickly back up to $8, or Crescent Point to $25 but this doesn’t seem like the sort of market to be trying to squeeze out the last 10%.

What I sold (and one more I added)

As I already said I sold out of most of my oil stocks.  I also used the run-up in tanker rates (they breached the $100K per day rate last week) to sell out of DHT Holdings in the mid-$8s and Ardmore Shipping at $13.  I took some quick profits on my small position in Apigee, which ran back up from $7 to $10 on just as little news as what precipitated its move down from the same level.  And I sold out of Alliance Healthcare after the rather bizarre acquisition of shares by a Chinese investment firm (another case where poorly timed holidays contributed to a larger loss than I might have otherwise taken).

I also had a bunch of stocks that I neglected to add to my on-line portfolio, mostly previously held names like Enernoc, Espial Group and Hovnanian.  I took small positions in these stocks during the last dip but sold out them of quickly as they rose.  My plan is to continue to do this sort of cycling, taking advantage of dips and selling the rips.

With that in mind, I did re-add one last position on the last downdraft that hasn’t recovered like I had hoped and that I think will at some point soon.  Air Canada.  The third quarter is mostly passed and there isn’t a lot of evidence that overcapacity from Air Canada and WestJet is going to hinder their performance.   The stocks has barely budged from $11 while other airline stocks soar.  I think it catches up some of this performance in the near term. (Note that I forgot to add this one to the online portfolio but will correct that when the market opens on Tuesday).

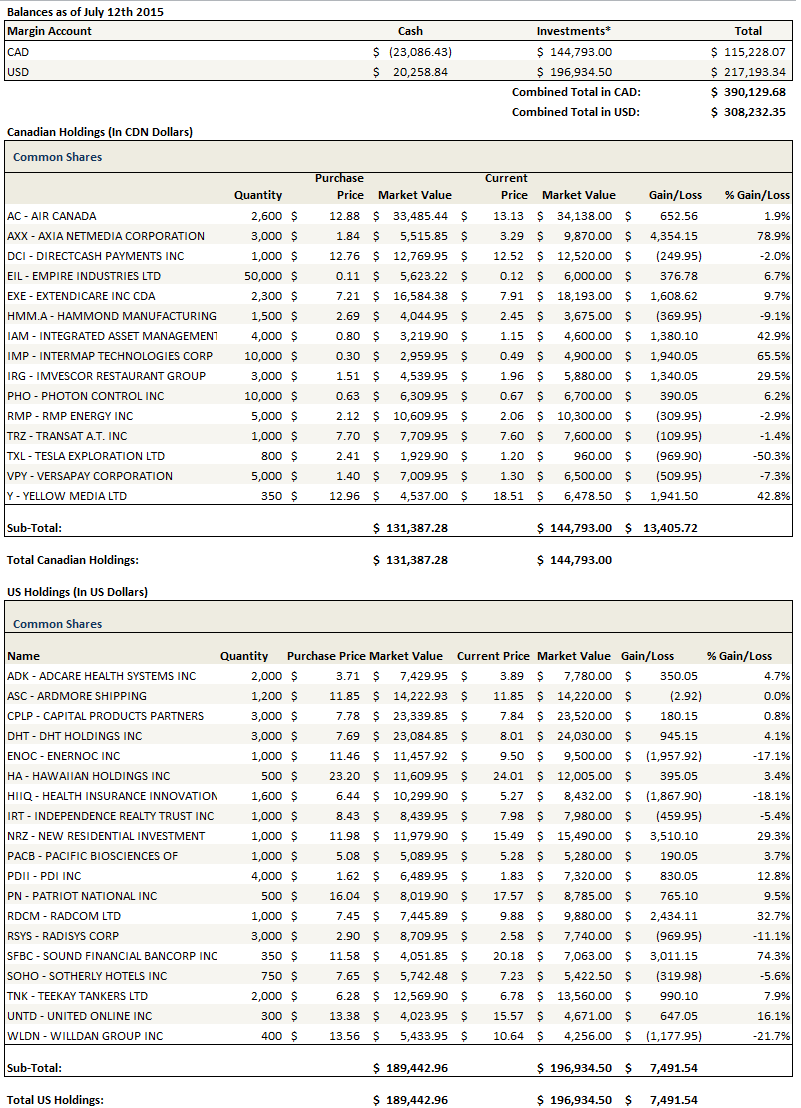
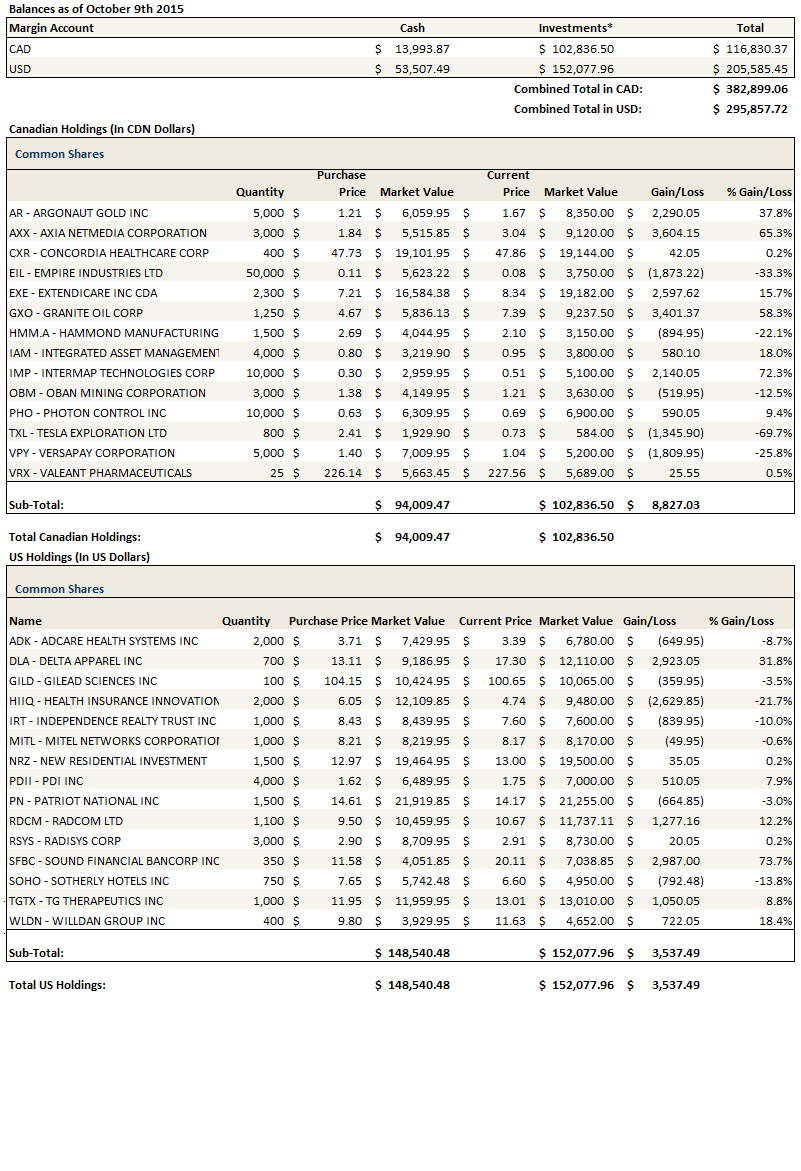
Portfolio Composition

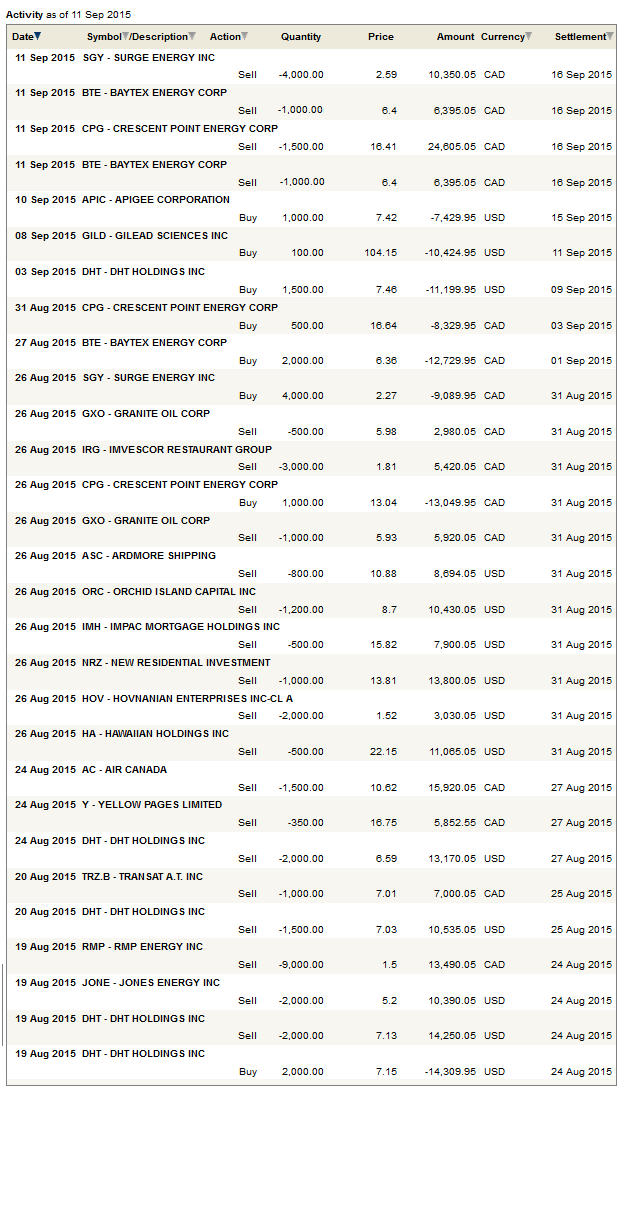
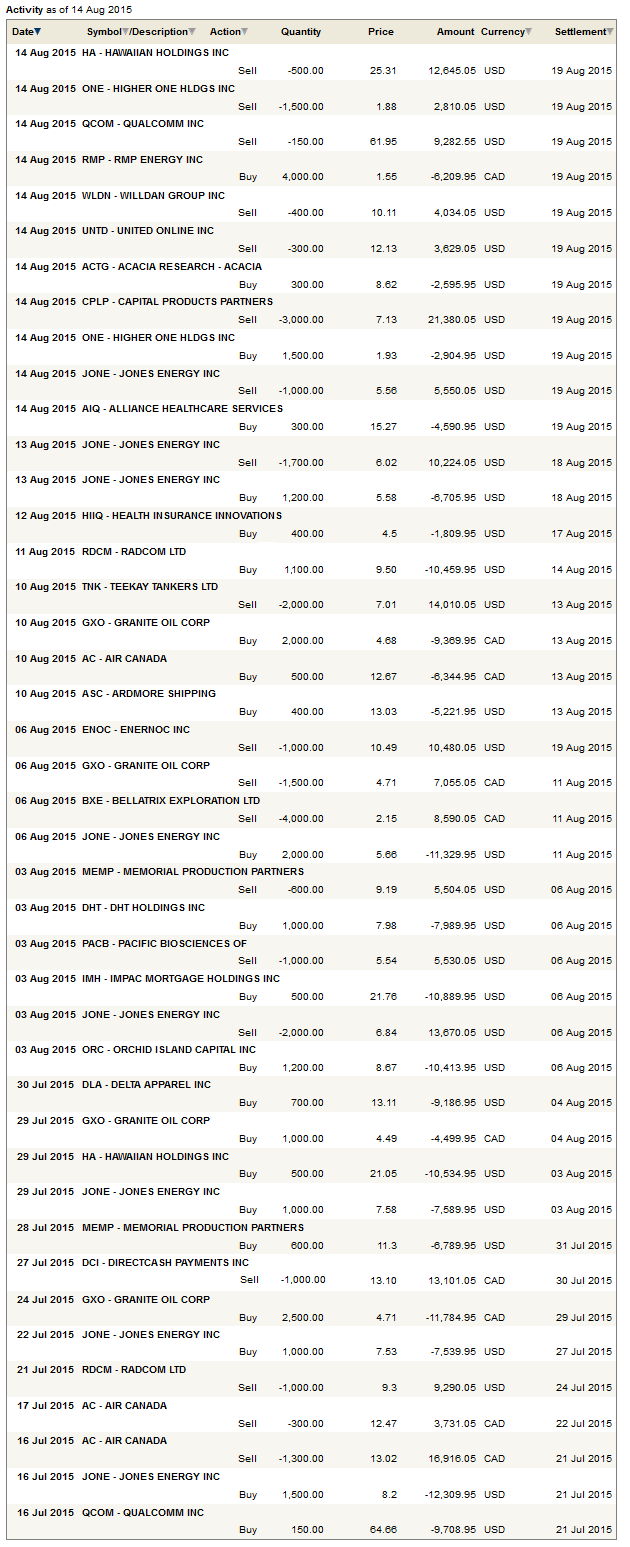
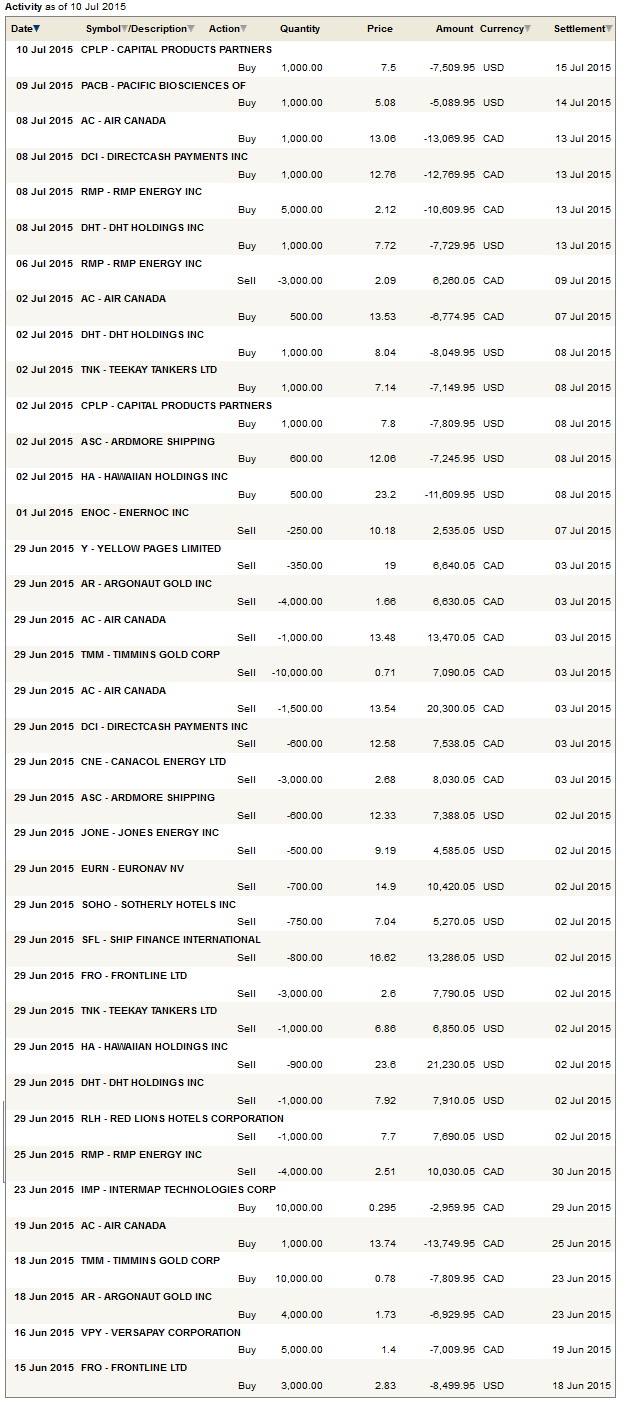
Click here for the last four weeks of trades.
week-223

Week 219: Feeling more like a bear market

Portfolio Performance

week-219-yoyperformance

week-219-Performance

See the end of the post for the current make up of my portfolio and the last four weeks of trades

Monthly Review and Thoughts

In my update four weeks ago I wrote:

When I raise the question of whether we are in a bear market, it is because, even though the US averages hover a couple of percent below recent highs, the movement of individual stocks more closely resembles what I remember from the early stages of 2008 and the summer of 2011.

Since that time my concern that the averages had only been lagging the inevitable has born itself out.  We have seen a 10-15% pull-back depending on the index you are referencing.   It has become clear that we are indeed in a bear market, if not by definition then certainly in spirit.

The next obvious question is – when do you buy?  Every other pullback over the last few years has been a buying opportunity.  Is this pullback, being the deepest of the bunch, the best of the bunch?

I don’t think so.  At least not yet.  There are just too many headwinds right now.

First, returning to what I wrote last month:

When the Federal Reserve ended its quantitative easing program last year I was concerned that the market might revert back to the nature it had demonstrated after first two QE endeavors.  But for a number of months that didn’t happen.  Stocks kept moving; maybe not upwards at the speed they had previously but they also did not wilt into the night.

I am starting to think that was nothing more than the unwinding of the momentum created by such a long QE program.  Slowly momentum is being drained from the market as the bear takes hold.

Nothing has changed here and stocks are still too expensive to say that we’ve passed through this process.  If QE was a positive influence on stock valuations, certainly the lack thereof has to be a negative influence.  While there are a few stocks that are cheap right now, many are not.

Second, when volatility is as high as it has been over the last few weeks it usually indicates the market is breaking down rather than breaking out.  I’ve seen this pattern too many times; increasingly choppy and nomadic market moves tend to break down.

Third, we don’t really know what is going on in China.  Nobody really knew how strong the boom was through the last decade; in fact I made a lot of money following the advice of metal prices over analyst comments.  Similarly, I don’t think there are many that have a good grasp on the magnitude of the slowdown.

None of this means that it has to play out to the downside.  Maybe China will be a blip, stocks will resolve themselves to the upside and I will be frantically trying to catch up.  But betting against the odds is not profitable and these odds don’t feel like they are in my favor.

So what am I doing?  Sitting with a lot of cash ( I have 55% cash in my investment account and 60% cash in my RRSP).  Picking a couple of opportunities where I see them but keeping the size small enough that I won’t be hurt if the markets break down again.  And where I can, holding some shorts to help hedge long exposure.

The last five years have been an incredible opportunity to compound capital.  In 2012, when the Fed was clearly going to announce more QE and stocks were going up every day my strategy was simply to find the most levered longs I could to make the most of the upside.   I remember how I was derided by many for doing that.

To give a particular example, I remember how some folks on twitter wrote snide remarks about my YRC Worldwide position.  What a shitty company it was, how it was inevitable it would go bankrupt (one even wrote that the probability of a YRC banruptcy was 100%), and so on.

I just couldn’t figure it out.  I kept thinking, who cares?  The point of this game is to make money and in that particular environment, with the amount of stimulus we had and with a US economy on the mend, it was exactly the kind of stock that could run as a multi-bagger.

It seems as though some investors/pundits think that being right is a philosophical exercise.  And in this game it’s not.   My only measure of success in the market is how quickly and how far that chart at the top of each post trends from the lower left to the upper right.  The rest is sophistry.

While 2012 was the time to buy the levered longs, today the reverse is in play.  You have to be very careful about even buying good businesses that you believe are being mis-priced by the market.  In a bear market just about everything goes down, so you better be sure about what you pick.  Just because it is a good business with a moat doesn’t mean it won’t get sold off with the rest of the market.

I do think that in this environment growth is most likely to come back first.  I am looking for stocks with catalysts and stocks with growth profiles maybe not recognized yet by the market.  Especially if they are beaten down.

Selling Out

I did a lot of selling leading up to and on the bounces of the first decline.  I wanted to get my cash positions up to at least 50%.  I sold entirely out of Hawaiian Holdings, Impac Mortgage, Orchid Island Capital, Ardmore Shipping, DHT Holdings, Air Canada, New Residential and Yellow Pages. I also reduced just about every other position I had.

Since that time I have bought back into Ardmore Shipping and Air Canada to lesser degrees than the level that I had originally held them.  I have added back my full position in DHT Holdings as I see strong fourth quarter shipping rates as a catalyst for some short term gains.  The other stocks I might buy back if the prices become very attractive or if I see changes to the landscape that make me more constructive on the market.

New Positions

Most of my research in the last month focused on biotech firms.  I have to say, its been a lot of fun.  Its fascinating stuff. I even discovered a Vice documentary on how we are using viruses to battle cancer.   The technology leaps are amazing!

I looked at Mylan, Mallinckrodt, Intrexon, Teva, and a whole pile of smaller Phase 2 candidates (including Flexion, which subsequently was clobbered after their FX006 Phase 2b trial had less than stellar results – note though there might be an opportunity with this one).

Most of these names I can’t bring myself to buy because of valuation.  Even though the charts are bad and the stocks are way off their 52-week highs, most still look expensive to me.  But I did take small positions in a couple of names: one large cap pharmaceutical stock (Gilead) and one small cap phase 3 drug developer (TG Therapeutics).   Here is what I think of both of Gilead and TG Therapeutics and why I added them.

Gilead Pharmaceuticals

Gilead is a much bigger company than I typically invest in.  With over 1.5 billion shares outstanding,currently trading at $105, they have a market capitalization of around $160 billion.  The company has very little debt, with cash on hand of $7.4 billion and $12.2 billion in long term debt as of the end of the second quarter.  They also just raised an additional $10 billion of debt this week, which many are speculating will be used for an acquisition.

Gilead produces leading hepatitis drugs (Harvoni and Solvaldi, with Harvoni being the next generation treatmen) and leading HIV drugs (Truvada, Atripla and Stribula).  The two hepatitis drugs accounted for 65% of sales in the first half of the year.  Harvoni, which is new to the market, accounting for almost 50%.  They also make a cancer drug that I will discuss a little when I talk about TG Therapeutics.

In 2014 Gilead had cash flow from operations of $12.8 billion and capital expenditures of $500 million, so free cash flow was $12.3 billion.  In the first half of 2015 cash flow was $11.4 billion and capex was $300 million.  The increased profitability is coming from an increasing number of insurance payers approving coverage of the hepatitis drugs and from the recent introduction of Harvoni.

If you annualize first half cash flow Gilead has a free cash flow multiple of 7.4x, which is a lot cheaper than the other drug companies I have looked at.  Why?  The market is concerned about the concentration of revenues in one drug (Harvoni), potential competition for the hepatitis drugs, and the lack of a pipeline of new drugs.

While these concerns are valid, I think that the discount is over done.  When I look at other large bio-techs Gilead trades at a 30-50% discount on free cash flow, and that seems too large.  It just seems like the relative sentiment has gotten too extreme.  There is also the potential of a catalyst in the form of an acquisition that the market approves of.  Finally, as this excellent 3 part Seeking Alpha article series identifies, Gilead’s pipeline of homegrown drugs is not as barren as is often made out.

I’m keeping my position small.  Much of this thesis is based on valuation and as I’ve already implied, I don’t believe that valuation in a bear market is a terribly strong leg to stand on.  I think Gilead does well and outperforms if the market does well. But it will likely fall along with the market if things depress further.

TG Therapeutics

I owe this idea to a tweeter by the moniker of @Robostocks123, who has been tweeting about TG Therapuetics for some time.

Of all of the late stage biotechs that I looked at, this one made the most sense to me.  TG Therapeutics is a $600 million market capitalization company with no debt and $60 million of cash.  The company is in stage 3 development of a couple of different drugs targeting lymphomic malignancies.

The first drug, TG-1011, is in a phase 3 trial as a combination with another drug, Ibrutinib, which is owned by Abbvie.  Ibrutinib has already been approved to treat b-cell lymphoma’s but there are a number of patients taking Ibrutinib that have had to discontinue treatment early because of adverse side-effects.  Combining Ibrutinib with TG-1011 is expected to improve the effectiveness of the treatment and, most importantly, reduce adverse reactions and so far the results bear that out.

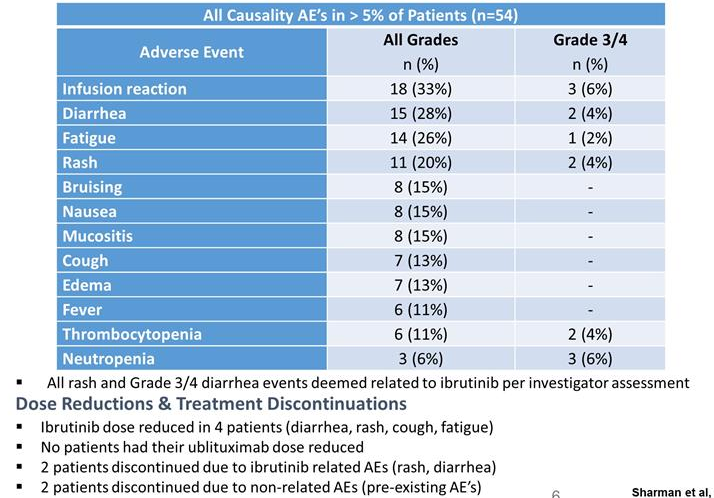
While we won’t know the phase 3 results for a few months, the Phase 2 results looked pretty promising.  First with respect to adverse events, the combination of TG-1011 and Ibrutinib led to very few serious side effects:

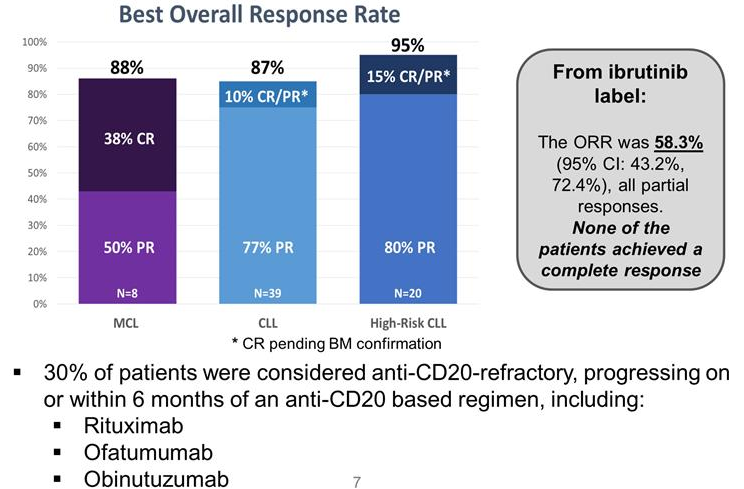
adverseeventsAnd with respect to efficacy, the combination showed improved results over Ibrutinib alone.

responserateThe immediate opportunity is that after approval TG-1011 will be prescribed alongside Ibrutinib.  Ibrutinib is relatively new but already is experiencing fairly significant revenue.  Below is an excerpt from Abbvie’s last 10-Q (Abbvie calls it Imbruvica):

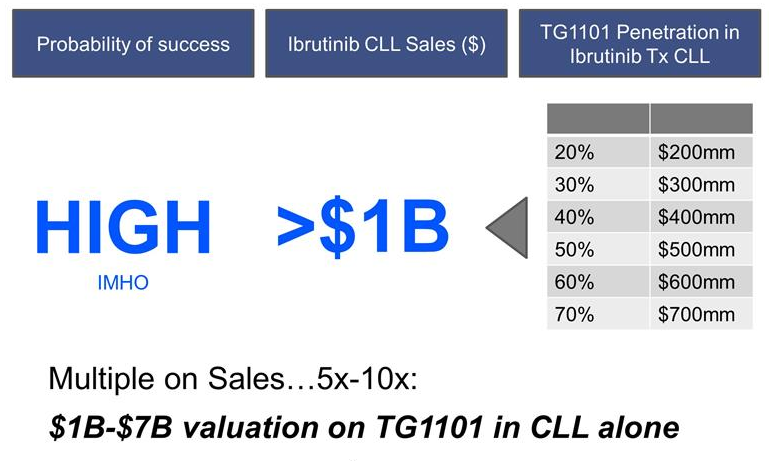
ibrutinibI’m sure some will see the following as a promotional red flag but TG Therapeutics put their own quantification to the opportunity in this slide at their recent presentation at the Rodman & Renshaw Annual Global Investment Conference:

potentialTG Therapeutics second drug in Phase 3 is TG-1202.  The 1202 drug is a PI3K-delta inhibitor, again targeting lymphomic malignancies.  It is the same type of compound as another already on the market called Zydelig (from Gilead with $50mm of revenue in the first half of 2015).  A third similar compound called Duvelisib from Infinity Pharmaceuticals is in phase 3 trials.

Both drugs from the competition suffer from varying degrees of toxicity problems.  Specifically with Zydelig patients can experience very bad diarrhea that can become life threatening.  The consequence is that often patients don’t stay on the drug long enough to fully recover.  Lymphomic malignancies are extremely difficult to fully wipe out and so you need a drug or combination of drugs with low toxicity so that treatments can run their full course.

TG-1202 appears to have a much improved toxicity profile versus the alternatives while having similar effectiveness.

While TG-1202 is showing promise as a single agent the ultimate game plan of TG Therapeutics is to combine TG-1202 with other drugs.  The first combination that is being investigated is alongside the TG-1101 compound.

A phase 3 trial is just about to begin using the combination of 1202 and 1101.  The trial includes the potential for accelerated approval of the drug combination if a significant overall recovery rate is observed among the first 200 patients.  As I already mentioned earlier stage testing of TG-1202 on its own showed both good tolerance from patients and good efficacy.  The hope is that together with TG-1101 TG Therapeutics will have a real winner, and one that does not depend upon a third party drug lie Ibrutinib.  A further possibility that will be investigated down the road is that a 3-drug combination of TG-1101, TG-1202 and Ibrutinib may provide even more benefits.

TG Therapeutics is taking the attitude that no one drug is going to cure the blood cancers they are targeting.  So their approach is to layer together drug combinations, first by adding TG-1101 to Ibrutinib, then by combining TG-1101 and TG-1202, and later by adding in combinations of earlier stage drugs in their pipeline like IRAK4 and Anti-PDL1.

Obviously I’m not an expert in this field, so maybe someone will be able to point out a fatal flaw in this idea.  What I see is a company with upcoming catalysts and with a stock price that does not, in my opinion, reflect the potential success of those catalysts.  So its a buy, but a small position because we know that when biotech’s go wrong, they go wrong badly.

Apigee

In addition to my two bio-tech buys, I added a small position in one tech name.  I found Apigee while scouring the 52-week lows a few weeks ago.  When I was first looking at the company it was trading at about a $180 million market cap with no debt and $90 million in cash.

I am going to do my best to describe what Apigee does without using the word platform.  Because everywhere you read about anything tech you read about the platform, and I honestly believe that at least 50% of the time what that really means is the author doesn’t know exactly what it is the company does so using a term that implies a vague, black box it will be less likely to arouse suspicions.

So what Apigee does, as I understand it, is write code that allows companies to have their internal databases, servers and applications accessed by users (it could be a consumer of the data for personal or commercial use or another company leveraging the data or functions from an application to build upon their own application), but with restrictions in place that limit what data can be consumed and by whom, what app functionality is exposed and what modifications can be made, and that give the company the ability to track, monitor and extract information about what the API clients are doing and how their data and applications are being consumed.

So they sell an API platform.

I think its a pretty decent business idea.  There are plenty of non-tech companies that are getting dragged into the mobile world and to think they are going to hire programming staff that will create mobile interfaces that function and perform effortlessly, be secure, be expandable over time and serve the needs of clients seems like a tough gig to me.  I’ve worked in a dedicated software firm for seven years and its tough to have good code even when this is what you do.  Having a third party provider of the necessary middle man interfaces makes sense.

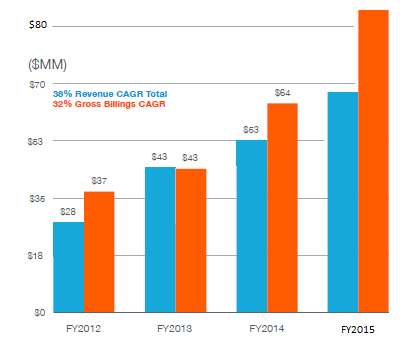
Of course the question is whether Apigee has the best solution out there.  While I can’t speak directly to that I can fall back on the results.

revenue

Apigee is growing revenue, growing gross bookings and adding clients.   Note that I added the 2015 data to the company slide below.

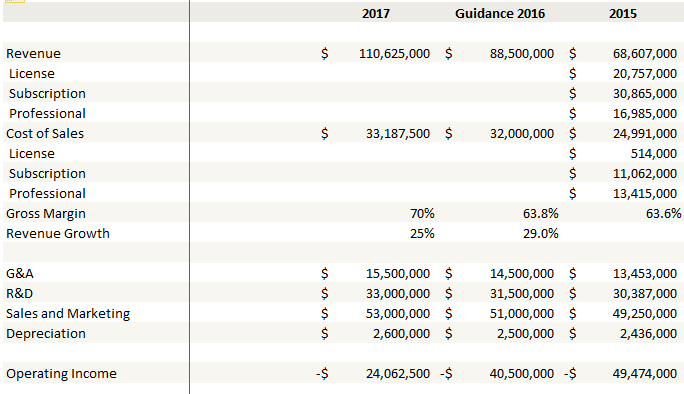
But I am still not completely sold on the stock, and I have kept my position quite small.  My problem is that Apigee is far from being cash flow positive.  And I really have a problem holding stocks will lose money as far as I can model out.

Below is my model.  The 2016 numbers are based on their own midpoint guidance while 2017 is based on my estimate of 25% revenue growth, some improvement in margins as subscription and licensing takes a bigger piece of the pie, and modest operating cost increases.

forecast

The company says they expect to be cash flow positive in the second half of 2017 so maybe my expectations are too conservative.  And really, that’s kind of the bet here.  The story is an IPO gone bust, but the results so far suggest the business is on solid ground.  If the company puts together a couple more quarters of beats that profitability number is going to start to come in and I bet the stock gets back to its IPO price.

Where I am at with Oil

If I were a promoter I might say that I nailed the bottom in oil stocks.  A more honest appraisal would point out that it took me three tries.

Those that follow the blog will recall that I had tried and failed to pick a bottom in July.  I was in the process of my second try when I wrote my mid-August update but that one didn’t stick either, as I sold out of RMP Energy and Jones Energy soon after my August 16th post (I kept Granite Oil which has turned out to be a big winner even as other oil stocks have suffered).  My third attempt came on the heels of this release from the EIA, where they revised production downward for the first six months of the year and that one proved to be the winner.

The changes to the EIA data, which clearly show US production has been declining since early in the year, seems like a game changer to me.  Maybe it is not a reason for oil to go straight up, but it might be a reason for it to no longer go down.  Just like the stock market, it’s not when the data begins to get better that matters, but when the data stops getting worse at an accelerating rate.  Its all about the second derivative.

So we will see.  After the EIA release at the end of August I bought Crescent Point, Surge Energy and Baytex, and added back Jones Energy and RMP Energy.  However I knew I would not have the nerve to hold onto these positions if they moved and sure enough I quickly panicked down my positions in each on that first, rather dramatic, correction from $49 (and no I did not catch the top in any of the positions).

I’ve since sold  completely out of a number of the positions (I currently hold Granite, a little Crescent Point and a little RMP) as we seem tenuously on the brink of a re-test.  While I want to believe that an oil turn is upon us, I’m just not sure.  I am really torn about whether to believe the Goldman Sachs of the world or side with the tiny minority that think that all the data doesn’t quite make sense.

Because the reality is that to be an oil bull you have to believe the data is wrong and the forecasts are wrong.

One opinion I will note is this interview from BNN ith Mike Rothman of Cornerstone Analytics.  Rothman believes, if you can believe it, that we will see $85 Brent at year end.  Check out the date – he called this on August 25th, when oil was carving out its bottom in the $30’s.

Rothman’s thesis is basically that the IEA numbers aren’t right and everyone, all the experts and so on, are at their root basing their opinions on this one set of numbers.

And they have an unfortunate problem that I think is well known where they are chronically underestimating demand.    Typically the problem is in the emerging markets… we’re seeing a major episode of that… a lot of the assertions I’m sure you have heard, I’m sure the people listening to this program have heard is that the oil market is oversupplied by 2-3mmbbls and that demand is weak.  Demand is at record levels.  Its not an opinion its an assessment of the actual data.  The problem is the underestimation of the non-OECD.

I am somewhat sympathetic with this view.  I remember back to pre-2008 when the IEA continually underestimated demand.  Meanwhile we know that world production declines by 4-5% and that decline is, if anything, accelerating.  Wells have to be drilled to stem that decline and it still requires capital to drill wells.  I have to ask – is that capital really getting the return to justify its expenditures?  Because if it takes 2-3 years to get back your capex then its not worth doing even if you are a national oil company.  You’ll end up deeper in debt.  I don’t know, maybe everything I read is gospel but it just doesn’t sit right with me.  I would love to see well level analysis and economics of new developments in Iraq, Iran, Russia, all these countries where it is supposedly so profitable to ramp production and where all those production ramps are sustainable.

But with all that said, I remain neutral in my actions.  I’m not going to pound my fist and say the market is wrong.  I’m just going to quietly write that I don’t think things are as certain as all the oil pundits write and continue to be ready to pounce when the skies clear enough to show that an alternate thesis is playing out.

Portfolio Composition

Click here for the last four weeks of trades.
week-219

Week 2015: Maybe its just a bear market

Portfolio Performance

week-215-yoyperformanceweek-215-Performance


See the end of the post for the current make up of my portfolio and the last four weeks of trades

Monthly Review and Thoughts

I don’t flash sensational headlines about bear markets for the sake of getting attention.  I get about 100-150 page views a day and given the frequency and technicality of my writing I don’t expect that to increase materially regardless of the headline I post.

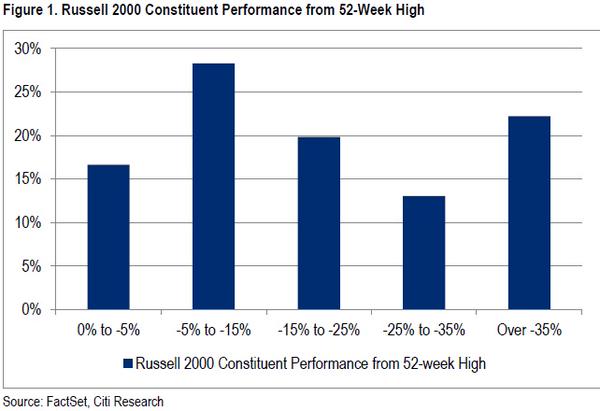
When I raise the question of whether we are in a bear market, its simply because even though the US averages hover a couple of percent below recent highs, the movement of individual stocks seems to more closely resemble what I remember from the early stages of 2008 and the summer of 2011.

A breakdown of the performance of the Russell 2000, which is where a lot of the stocks I invest in reside, was tweeted out this week by 17thStrCap and I think illustrates the pain quite well:

us market

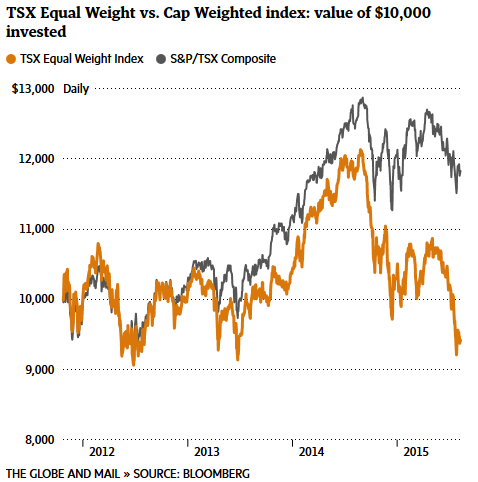
The Canadian stock averages have been made respectable by Valeant and not much else. In a Globe & Mail article appropriately capsulizing my comment here called “The market is in much worse shape than the TSX index suggests” the following comparison was made between the TSX Composite and an equal weighted version of it that dampens out the Valeant effect.

tsxperformance

When the Federal Reserve ended its quantitative easing program last year I was concerned that the market might revert back to the nature it had demonstrated after first two QE endeavors.  But for a number of months that didn’t happen.  Stocks kept moving; maybe not upwards at the speed they had previously but they also did not wilt into the night.

I am starting to think that was nothing more than the unwinding of the momentum created by such a long QE program.  Slowly momentum is being drained from the market as the bear takes hold.

A week late

I am a week late getting to this update.  We were on vacation last week, which made it tough to write.  As well I was in no mood to ruin my vacation and write with my portfolio going through significant perturbations to the downside.

It is frustrating to see my portfolio doing poorly.  My investment account is being saved by two things:

  1. Shorts
  2. US stocks in Canadian dollars

As I mentioned last month I have had a number of technology shorts, some shorts on Canadian banks and mortgage providers, and hedges on energy and small caps via the XOP and IWM.  I actually took a bunch of the tech shorts off in the last few days for the simple reason that they are up so much.  I had some decent gains from INTC, SNDK, MU, ANET AVGO, RAX, HIMX and TSM.  I also ended my multi-year short on YELP.

I am covering my shorts because with earnings season over I think there could be a counter rally resulting from the news vacuum.   The China collapse angle has been beaten up and priced in; I could see the perception shifting towards the positive outcomes of the stimulus. And I’ve read that Apple is increasing orders for the iPhone 6s and 6s+ which may or may not be warranted (I suspect not) but could lift tech results in the short term.

I would put these shorts back on if the stocks recovered.  But I don’t feel like I know enough about tech to be pressing my luck on the names.  And as I reduce my long portfolio and raise cash, I feel less need to have what feel like stretched shorts to hedge those positions.

Without the benefit of short hedging this blog’s online tracking portfolio has done worse.  I’m down about 5.6% from a brief peak I hit in mid-July (when the tankers were at their highs) and I am essentially running flat for the last 4 months.

At the center of my frustration are tankers, airlines, small caps and the REITs.  So pretty much everything.  Let’s talk about each.

The Tankers

With oil oversupplied and refiners working at record capacity producing gasoline, jet fuel and heating oil, one would expect that the market would turn to crude and product tankers as a natural beneficiary.

No such luck.

The recent moves by my favorite tanker plays: DHT Holdings, Ardmore Shipping and Capital Product Partners, have been to the downside.  There was a brief move up towards the end of July that coincided with earnings (which were outstanding) but it was quickly unwound and now we are back to levels seen a few months ago.  While I sold some along the way up, it wasn’t (and isn’t) ever enough.

Ardmore Shipping

Particularly with the product tankers (specifically Ardmore Shipping), I just don’t get why the behavior is so poor.  I found it difficult to come away from their second quarter conference call with anything but an extremely bullish take on the company’s prospects.

The product market is benefiting from extremely strong refinery utilization and strong demand for products.  It is also benefiting from the move by Middle East nations to add refining capacity with the view of exporting finished products.

Ardmore had earnings per share of 30c.  They achieved those earnings with 18.4 ships. By the end of the year, once all of their newbuild fleet is delivered, the company expects to have 24 ships.  If newbuilds had been operating in the second quarter, earnings would have been 43c for the quarter.

In the second quarter Ardmore saw spot rates of $22,400 TCE.  So far in the third quarter spot rates are up again to $23,500.  At current $23,500 spot rates and with 12 MR’s in the spot market, EPS would be $1.85.  The stock has been trading at around $13.

Yet the stock sells off.

DHT Holdings

Likewise, I couldn’t believe it when DHT Holdings traded down to below $7 on Wednesday.  At least the crude tanker market makes some sense in terms of rates.  Voyage rates have come off to $40,000 TCE for VLCC ships.  This is seasonal and if anything rates have held up extraordinarily well during the slow third quarter.

DHT stated on its conference call that they had more than 50% of their third quarter booked at $80,000 per day.  The company has a net asset value of around $8.50 per share.

While I already had a pretty full position heading into the last move down I held my nose and added more at $7.15 (i never catch the lows it seems).  I’m not holding these extra shares for long though.  In this market having an over-sized position in anything seems akin to holding an unpinned grenade.

The Airlines

While Hawaiian Airlines has been an outperforming outlier, responding well to strong earnings, Air Canada has languished.  The stock got clobbered after the company announced record earnings and great guidance.

Air Canada reported 85c EPS and $591 million EBITDAR.  In comparison, BMO had been expecting 90c EPS and $618mm EBITDAR and RBC had been expecting 77c EPS and $558mm EBITDAR.

The story here really boils down to the Canadian economy.

Both WestJet and Air Canada are increasing capacity.  The market is worried that they are going to flood a weak market and pressure yields.  On the conference call Air Canada addressed the concern by pointing out that A. the capacity they are adding is going into international routes and B. they have yet to see anything but robust demand for traffic.

What’s crazy is that while investors have responded negatively, analysts have been bullish to the results.  I read positive reports from RBC, TD and BMO.   Only Scotia, which I don’t have access to, downgraded the stock on concerns about no further upside catalysts.

Its rare to see multiple upgrades accompanied by a 7% down move in a stock.  I would love to see one of the darling sectors, tech or biotech, respond in such a manner.

So the analysts are bullish and the company is bullish but right now the market doesn’t care.  As is the case in general, the market cares about what might happen if some negative confluence of events comes to fruition.  And it continues to price in those worries.

Its just a really tough market.

Trying to find something that works

Another contributor to my poor performance has been that what has worked over the last five years is working less well now.

In particular, over the last give years I have followed a strategy of buying starter positions in companies where I see some probability of significant upside.   In some cases I will buy into companies that do not have the best track record or are not operating in the most attractive sectors.  But because the upside potential is there I will take a small position and then wait to see what happens. If the thesis begins to play out and the stock rises, I add.  If it doesn’t I either exit my position or, in the worst case, get stopped out.

This has worked well, with my usual result being something like this.  I have a number of non-performers that I end up exiting for very little gain or loss, a few big winners, and a couple of losers where I sell after hitting my stops.

I’ve had a lot of winners this way over the last few years: Mercer International, Tembec, MGIC, Radian, Nationstar, Impac Mortgage (the first time around in 2012), YRC Worldwide, Pacific Ethanol, Phillips 66, Nextstar Broadcasting, Alliance Healthcare Yellow Media and IDT Corp are some I can think of off-hand.  In each case, I wasn’t sold on the company or the thesis, but I could see the potential, and scaling into the risk was a successful strategy of realizing it.

Right now the strategy isn’t working that well.  The problem is that the muddling middle of non-performers is being skewed to the downside.  Instead of having stocks that don’t pan out and get sold out at par, I’m seeing those stocks decline from the get-go.   I am left sitting on either a 5-10% loss or getting stopped out at 20% before anything of note happens.  Recent examples are Espial Group, Hammond Manufaturing, Versapay, Higher One Education, Willdan Group, Acacia Research, Health Insurance Innovations and my recent third go round with Impac Mortgage.

All of these stocks have hair.  But none has had anything materially crippling happen since I bought them.  In the old days of 2012-2014, these positions would have done very little, while others, like Patriot National, Intermap, Photon Control, Red Lion Hotels and most recently Orchid Island would run up for big gains and overall I’d be up by 20% or so.  Instead this year the winners still win, albeit with less gusto, but its the losers that are losing with far more frequency and depth.

So the question is, if what has worked is no longer working, what do you do?

You stop doing it.

I cleaned out my portfolio of many of the above names and reduced a couple of others by half.

So let’s talk about some of what I have kept, and why.

Health Insurance Innovations

HIIQ announced results that weren’t great but the guidance was pretty good.  Revenue came in at $23 million which is similar to Q1.  In the first quarter the company had been squeezed by the ACA enrollment period, but in the second quarter this should have only impacted April.  So I had been hoping revenue would be a touch better.

The guidance was encouraging though.  The company guided to $97-$103 million revenue for the year which suggests a big uptick in the second half to around $28 million per quarter.  In my model, I estimate at the midpoint they would earn 40c EPS from this level of revenue if annualized.

Also noted was that ACA open enrollment would be 90 days shorter next year, which should mitigate the revenue drag in the first half of the year.  And they appear to be doing a major overhaul of management – bringing on people from Express Scripts (new president), someone new to evaluate the web channel and a number of new sales people.

Its been a crappy position for me but I don’t feel like there is a reason to turf it at these levels, so I will hold.

Impac Mortgage

As usual Impac’s GAAP numbers are a confluence of confusion.  The headline number was better than the actual results because of changes to accretion of contingent expense that they incurred with the acquisition of CashCall.

The CashCall acquisition had contingent revenue payout and that payout expectation has decreased leading to lower accretion via GAAP.  Ignoring accretion the operating income was around $8 million which was less than the first quarter.

The decline was mostly due to lower gain on sale margins, which had declined to 186 bps from 230 bps.

While origination volumes were up 8% sequentially (see below) I had been expecting better.  The expansion of CashCall into more states was slower than I expected.  In the second quarter CashCall was registered in 19 states.  I actually had thought that number was 29.

q2volumesBy the third quarter CashCall is expected to be compliant in 40 states.  And really that is the story here.  Volume growth through expansion.

CashCall is a retail broker dealing primarily with money-purchase mortgages (mortgages to new home owners).  Therefore Impac is not as dependent on refinancing volumes as some other originators.

While it was not a great quarter the company still earned 70c EPS.  Its lower than my expectations but in absolute terms not a bad number.  On the conference call they said that Q3 margins looked better than Q2, and while July production was only about $700mm, they expected better in August-September as the pipeline was large.

I made a mistake buying the stock at $20 on the expectation of a strong second quarter.  But I think at $16 its reasonable given earnings power that should exceed $3+ EPS once CashCall is operating nationwide.

PDI Inc

The response to the PDI quarter is indicative of the market.  The company released above consensus earnings on Thursday along with news that their molecular diagnostic products were being picked up by more insurers.  In pre-market the stock was up 20% and it looked like we were off to the races.

It closed down.

Recall that PDI operates two businesses.  They have a commercial services business where they provide outsourced sales services to pharmaceutical companies looking to market their product.  And they have the interpace diagnostics business, which consists of three diagnostic tests: one for pancreatic cysts and two for thyroid cancer.

I suspect that the market decided to focus on the one negative in the report: reduced guidance for interpace revenues from $13-$14 million to $11-$12 million.  The guidance reduction was caused by a delay in receivables from some customers.  The metric by which to judge the growth of the actual operations, molecular diagnostic tests, increased from 1,650 in the first quarter to 2,000 in the second quarter.

But in this market you gotta focus on the negative.  At least on Friday.

Patriot National

When I bought Patriot they were a new IPO whose business was a platform that allowed them to procure and aggregate workers compensation policies for insurance carriers.  They sign a contract with a carrier for a bucket of policies with particular characteristics and then distributed that to their pool of agents, collecting a fee in return.

But over the last couple of months Patriot seems to be expanding that role to something more holistic.  Among their nine acquisitions in the past six months is an insurance risk management firm, an auditing and underwriting survey agency, an insurance billing solution platform and a beneits administration company for self-funded health and welfare plans nationwide.

Patriot describes themselves in their latest presentation as follows:

whattheyarePatriot has shown solid growth since their IPO, both through their roll-up strategy of small insurance businesses and organically.  They have increased their carrier relationships from 17 to 82.  They are expanding their relationship with a few big carriers like AIG and Zurich.  They have grown their agent pool from 1,000 to 1,750.

I’m not really sure what it was about the second quarter that caused the stock to sell-off like it has.  It was down 16% at one point on Wednesday, which is about the same time I tweeted that this is crazy and pulled the trigger.  I suspect its simply another case of a bad market, a run-up pre-earnings and a release that didn’t have anything clearly “blow-outish” about it.

Nevertheless the company provided guidance along with its results and for 2016 predicts 37% revenue growth and 55% earnings growth.  These numbers make no allowances for further accretive acquisitions, which undoubtedly will occur.

The stock trades at 6.5x its 2016 EBITDA multiple.  From what I can tell its closest peers trade at around 10x, and they aren’t growing at a pace anywhere near Patriot.  As I said I added under $16 and would do so again.

Orchid Island

I have followed Orchid Island for a long time having been an investor in its asset manager, Bimini Capital, in 2013.  I never bought into Orchid though; it seemed small, it always trade around or above book value and being an mREIT it seemed that you had to have more of an opinion on the direction of rates than I have had for a while.

But when the stock got below $8, or a 30%+ discount to book value, it just seemed to me like the opportunity was too ripe to pass up.

There have been a number of good SeekingAlpha articles by ColoradoWelathManagementFund on Orchid where he describes the MBS investments and also the Eurodollar hedges.  These hedges, which require a different GAAP accounting then other more commonly used hedges, seem to be at least partially responsible for confusing the market and leading to the massive discount to book.

However I don’t plan to wait this out until book value is realized.  When the stock hits double digits again I expect to be pulling the trigger.

Higher One Education

I bought back into Higher One after it got clubbed down to $2.20, where it seemed to be basing.  Upon buying the stock was promptly clubbed down again to below $2.

Like many other names I am not sure if the clubbing is warranted.  The company’s second quarter results were better than my expectations.

Adjusted EBITDA in the second quarter came in at $8 million versus $7.2 million in Q2 2014.  While the disbursement business EBITDA was down, both payments and analytics were up (46% and 38% respectively).  EPS was 8c which again was better than last year.

They lost 6 clients representing 86,000 signed school enrollment (SSEs), signed 4 new clients with 16,000 SSEs and renewed 59 clients with 675,000 SSE’s.  Their total SSEs were 5mm at the end of Q2.  Given the headwinds in the industry, Higher One is holding their own.

The overhang in the stock is because the DOE proposed new rules that ONE and others are pushing back on, with the biggest issue being that you can’t charge fees for 30 days after deposits.  From their conference call:

The way the rule is proposed every time there is a disbursement made into the students accounts, we’d have to freeze all fees for 30 days.

This of course would severely impair Higher One’s ability to be profitable with these accounts.

On Friday after writing this summary I decided to sell Higher One.  I’m waffling here.  I like the value but don’t like the uncertainty and if the market can knock it down to $1.90 then why not $1.50?  Uncertainty reigns king.  I might buy it back but its difficult to know just how low a stock like this can go.

My Oil Stocks

I’ve done a so-so job of avoiding the oil stock carnage of the last few months.  After the first run down in the stocks I added a number of positions in March and ran them back up as oil recovered to the $60’s.  Then oil started dropping again and in May I began to sell those stocks.

oiltweetBy mid-June I was out of all my positions other than RMP Energy.  By July I had reduced RMP Energy down to about a percentage weighting in my portfolio.

So far so good.

Unfortunately I started buying back into the oil names in mid-July, which was too early.  I bought Jones Energy in the mid to high-$7s but sold as it collapsed into the $6’s.  I tried to buy RMP again at $2.20 but got pushed out as it fell to $2.  I bought Baytex and Bellatrix which was just stupid (I sold both at a loss).  I’ve probably given back half of the profits I made on the first oil ramp.

In this last week I made another attempt but I am already questioning its efficacy.  I took small positions in RMP Energy and Jones Energy and a larger position in Granite Oil.  The former two have done poorly, while the latter had an excellent day on Friday that provides some vindication to my recent endeavors.

One thing I will not do with any of these names is dig in if the trend does not turn.  I’ve learned that commodity markets can act wildly when they are not balanced, and the oil market is not balanced yet.  So its really hard to say where the dust settles.

Even as I write this I wonder if I should not have just waited for a clear turn to buy.

These positions are partially hedged in two ways.  First, I shorted XOP against about a quarter of the total value of the positions.  And second by having so much US dollar exposure (still around half my account) as a Canadian investor they act as a bit of a counter-weight to the wild moves I can see from currency changes.

Jones Energy

One of the interesting things happening right now is that natural gas production is flattening, in many basins it’s declining, and yet no one cares.  When natural gas first went to new lows in 2012 many pointed to the declining natural gas rig count, believing prices would quickly bounce back.  They didn’t, in part because of the associated gas coming from all the liquids rich plays.

With the oil collapse much of the drilling in those liquids rich plays is no longer as attractive.  You have to remember that even as oil has fallen, natural gas liquids like propane and butane have fallen even further (ethane, which is the lightest of the liquids, is now worth no more than natural gas).  Many producers that were labeled as oil producers, because they produced liquids, really produced these lighter liquids that are now trading at extremely depressed levels.  Drilling in light-liquids rich basins (the Marcellus but also the Permian and parts of the Eagleford) has declined precipitously, and with it all of the associated gas being produced.

Meanwhile much needed propane export capacity is on the horizon and expected to arrive en-masse in 2016.

Jones Energy has too much debt (around $770 million net) but they also have oil and natural gas that take them out into 2018.  I think they are a survivor.  They have reduced their drilling and completion costs in the Cleveland from $3.8 million to $2.6 million.  They actually increased their rigs in the Cleveland in June, though I have to admit that might be dialed back again with the prices declining.  I bought back into the stock for the third time this year when it was clobbered on what seemed to be pretty good earning results (a beat and guidance raise).  Its a play on oil, but also on falling natural gas production, as natural gas makes up 43% of production and much of the associated liquids are light.

RMP Energy

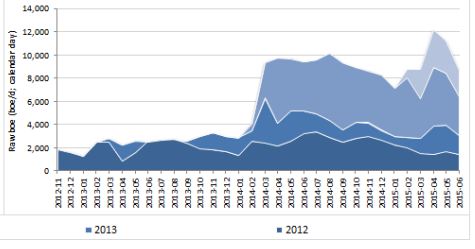
I think that the miserable performance of this stock is overdone, but I have thought that for some time and down it continues to go.  RMP gets punished over and over again for essentially the same concern – Ante Creek declines.  This latest pummeling seems to have been precipitated by the disclosure that August volumes at Ante Creek were around 8,500 boe/d.   This is a decline from April volumes of 12,200boe/d but similar to end of June volumes.  Below is a chart from Scotia that details Ante Creek production:

antecreekvolumes

The April increase coincided with the new gas plant.  The subsequent fall was because the company drilled no new wells in the second quarter.  That production has stabilized from June to August without any new wells being drilled is encouraging.

But the market sees it differently.

Lost in the shuffle (with nary a mention in any of the reports I read) is that RMP has reduced its drilling and completion costs by 30% and that operating expenses were down from $5.26/boe to $3.89/boe.  Also forgotten is that the company is experiencing positive results at Waskahigan with it new frac design.

RMP trades at about 2x Price/cashflow and has debt of about 1.35x expected 2015 cash flows.  Its not levered like many peers and its not expensive.  These constant concerns about Ante Creek need to be priced in at some point.

Granite Oil

Of the three names I own, this is the one I am going to stick with the longest.  Granite has a $150 million market capitalization and $50 million of debt.  Their asset is a large position in the Alberta Bakken (350,000 net acres).  They can drill 240MBBL wells that are 98% oil for $2.8 million per well.

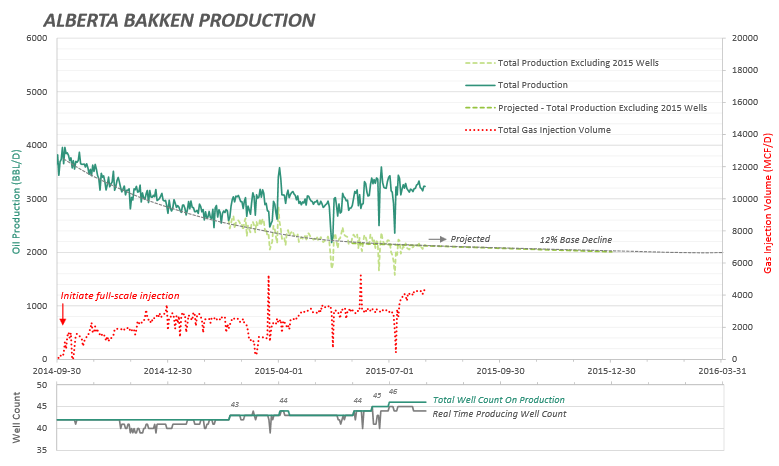
And they are beginning a gas injection EOR scheme that is showing promising results.  Below is company production as gas injection has increased.

alberta-bakken-eorThe results are well above expectation and show minimal decline even as the number of wells drilled has only increased marginally.

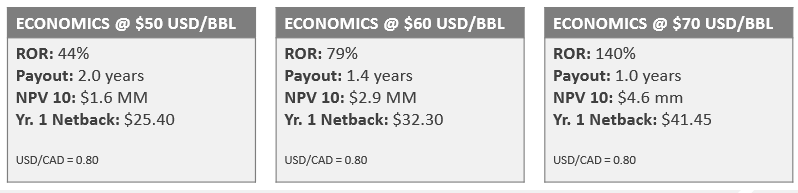
The result is some pretty strong economics even at lower oil prices.

economics

Granite management had been loading up on shares in the $4’s.  I did too.  The company announced earnings on Friday and is probably the only oil company to announce a dividend increase.  Like I said, this will be the last oil position to go for me.

Portfolio Composition

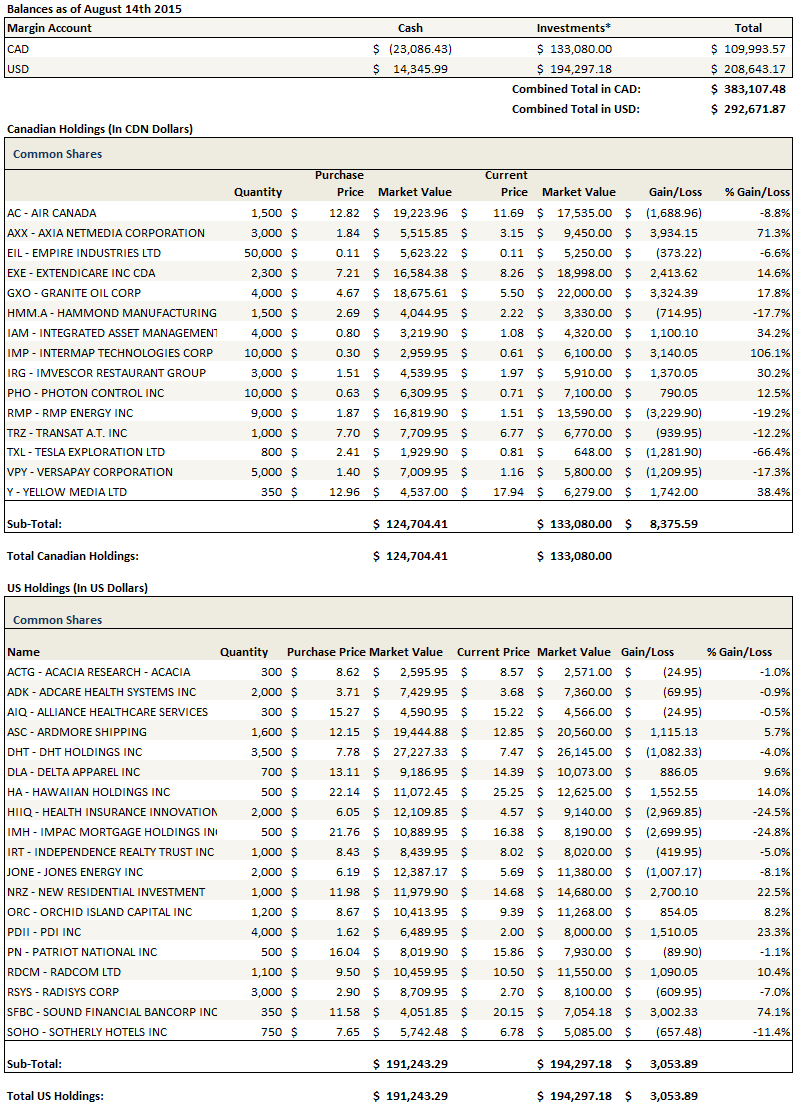
As I’ve said a number of times in the past, I sometimes forget to mimic my actual trades with the online RBC portfolio I track here.  After a while these differences get too out of whack and I have to re-balance.  I did some of that on Friday, and so the transactions on that day are simply me trying to square up position sizes.  I don’t have things quite right though; the cash level of my online portfolio is negative while my actual investment account is about 15% cash.  I looked at why this is and its the contribution of a number of positions that are all slightly larger in the online portfolio than they should be.  I didn’t have time to adjust everything exactly so I’ll just try to reduce this discrepancy naturally over time.

Click here for the last five weeks of trades.

week-215


Week 210: All about the 5-baggers

Portfolio Performance

week-210-yoyperformance

week-210-Performance

See the end of the post for the current make up of my portfolio and the last four weeks of trades

Monthly Review and Thoughts

A few weeks ago I was talking to someone who works at a large fund.   He was telling me about a retail clothing chain that their fund was interested in.  To help evaluate the opportunity, they commissioned a research firm to canvas and scout locations across the country.

That is amazing intel.  It is also wholly impossible for me to replicate.

I generally have a pretty good idea about a business before I buy into it.  I do a lot of work up front, far more than the highlights that go into these posts.  But I’m always left with elements that are uncertain.   For an individual investor with access to limited information and with limited time, certainty about one’s beliefs is more hubris than reality.

In the face of such disadvantages, my strategy is to take smallish positions and add to them if they begin to work out inline with my expectations.  If they don’t, I cut them.

By keeping my positions small until they start working and cutting my losses before they get big I guard against the big hit to my portfolio.  On the winning side of the ledger I generally end up with a similar number of winners that cancel out the losers.  But I also end up with 2 or 3 big winners that lead to out-performance.

It’s the 5-baggers that make the engine go.

Another portfolio year has passed (I started writing this blog on July 1st 2011) and you can see from the results that the last year was not as good as the previous few.  I still did better than the market, but I didn’t do that great.

In part the under-performance was caused by not sticking to my rules.  I have already rehashed my failures with Bellatrix and other oil names in past posts so I won’t go into that again here.

But I also attribute it to my lack of “5-baggers”.  I haven’t had a big winner in the last 52 weeks.  I’ve had a lot of good picks (Air Canada, Axia NetMedia, PNI Digital, Extendicare, Radcom, Rex American, the second go around with Pacific Ethanol and so on) but only one true double and nothing that tripled or quadrupled.

Realizing how important multi-baggers are I’m sending myself back to the drawing board.  I’m not sure why I’ve failed to discover the big movers over the last year.  But I suspect that it is at least partially due to ignorance of the sectors that have had the momentum.

Up until recently I never owned a bio-tech.  I’ve stayed away from technology in all but a few exceptions.  I’ve only been in healthcare on a couple of occasions (one of those being Northstar Healthcare, subsequently Nobilis Health Corp, which I rather amazingly sold last October, at no gain or loss, literally days before it began a climb from $1.20 to over $10 in thee next six months).  Yet these sectors are where the big winners have been.

My attitude towards these and other outperforming sectors is going to change.  I have invested in a couple of bio-techs and in technology (shorts mind you, as I will explain later) and in the last couple of months.  More new ideas will follow.

What I Sold

Usually I discuss my new positions next.  While I have a couple of these, they are not significantly sized and my actions have been more weighted to the sell side of the ledger, so it seems appropriate to discuss what I sold first.

As I tweeted on a couple of occasions I have been skittish about the market over the past month and a half.  I sold out of some positions and reduced others when Greece went on tilt and announced a referendum two weeks ago.

Since that time as my worries have subsided I have bought some of those positions back. It doesn’t look like an immediate contagion is upon us, which was my main concern.  Still I’m keeping a healthy amount of cash (20%) and where I can I am short a number of stocks.

In what turned out to be an unexpected consequence of my recent research expansion, over the past month I spent a lot of research hours looking at short opportunities. Trying to take more of an interest in tech, I read through reports describing the state of business and dynamics at play in everything from telecom infrastructure to smartphone.  As I did I felt most of the near term opportunity was on the short side, and so I took positions there.

My tech shorts have been based on three-fold expectations: PC sales are declining faster than consensus, smart phone sales will grow slower than consensus, and rumors that the big data build out by cloud providers has been overdone will prove to be true and future spending will be scaled back.  Without going into the individual names, I’ve stuck mostly with the big players and mostly with semi-conductor providers, which seem to be the most susceptible to spending downturns.

I think however that this play has almost run its course.  I have been taking off some positions heading into earnings (for example I was short Micron going into their June quarter but took it off the day after earnings were announced), and plan to exit my remaining positions as earnings are released.  I don’t like to hold short positions too long.

While I have yet to take any short positions in healthcare, I get the feeling that the recent merger mania may be leading to valuations that prove difficult to justify once the feeding frenzy subsides.  I note that a top pick of Jerome Haas, who I have followed and found to be a solid thinker, was a short on Valeant Pharmaceuticals.

In my online portfolio, in which I cannot short, I sold out of my gold mining shares, my oil stock shares, some of my tanker shares (Euronav and Frontline), a hotel play (Red Lion), reduced my airline exposure in both Air Canada and Hawaiian Holdings as well as my Yellow Pages and Enernoc positions.

I also sold out of DirectCash Payments, though I subsequently added the position back later (at about the same price).  I really want to hold this one through earnings because its been beaten down so far and I still have doubts as to whether the first quarter is the secular harbinger that the market seems to think it is.  In the turned out to be an unexpected consequence of my recent research expansion

Similarly, while I sold out of RMP Energy, I bought it back (at a lower price) because I want to see their quarter before giving up on the stock.  Like DirectCash Payments, I question whether results will be as dire as the market suggests. In the same segment of his BNN appearance Haas also made DirectCash Payments another top pick.

I only added to a couple of positions in the last month.  Patriot National continues to execute on their roll-up strategy, buying up smaller insurers at accretive multiples.  The stock is up 40% from my original purchase (though in the online portfolio I forgot to add it when I originally mentioned it so its up somewhat less there) and I decide to add to the position since its working out.

Second, I added to my position in Capital Product Partners on what I believe is unwarranted selling on Greece.  The company is incorporated in the Marshall Islands, does not pay Greek taxes but does have offices in Greece, which is at the heart of the sell-off.  A scan of the company’s annual filings shows that their exposure to Greece is potentially some deposits in Greek banks and the risk that one or more of their subsidiaries could face higher taxes.  I don’t think that correlates to the 20% plus sell-off in the share price.

I also added two new positions to my portfolio.

Intermap

I have followed Intermap for years.  Its a company that my Dad owned. While it always held out the promise of a significant revenue ramp Intermap could never quite figure out how to monetize their world class geo-spatial data.

Then, a couple of weeks ago, the company signed a large contract with unnamed government for the implementation of a National Spatial Data infrastructure program.

For years Intermap was primarily a mapping services provider.  They owned 3 Lear jets equipped with radar technology that scanned and mapped large swaths of terrain.  They would land contracts to map out a country or region and be paid for providing that data.

The company always kept the rights to their mapping data and, over time, Intermap compiled a database of geospatial data for a large part of the earth.   This spatial database became a product called NextMAP.   The database can be accessed through commercially available GIS software like ArcGIS or web browser apps developed by the company. Customers can license either parts of or the entire NextMAP database for their use.

The latest version of the database, called NextMAP World 30, is “a commercial 3D terrain offering that provides seamless, void free coverage, with a 30meter ground sampling distance, across the entire 150 million km2 of the earth’s surface.”

Intermap has always had a leading technology.  But they have struggled with coming up with profitable ways of marketing that technology.   Over the last three years the company has been working on applications that can be layered over their basic mapping data.  They have a program for analyzing the risk of fires and floods (InSite Pro), a program for managing hazardous liquid pipeline risk (InSite Pro for Pipelines) and a program for assessing outdoor advertising locations (AdPro).

None of these niche solutions have resulted in significant revenue to the company.

The carrot has always been that they land a large government contract for the full implementation of a geo-spatial solution for the country.  Most investors have given up on this ever happening, but then it did.

The announced contract is for $125 million over two years, during which time Intermap will implement the infrastructure solution.  This will be followed by an ongoing maintenance contract valued at $50 million over 18 years.

When I saw the number on the contract I knew immediately that the stock would jump significantly.  Including warrants and options Intermap has 127 million shares outstanding.  So at the closing price the night before the deal was announced the market capitalization was around $10 million.  When it opened around 25 cents I figured the upside was only about half priced in, so I jumped aboard.

The implementaton of a full geo-spatial solution as per the contract will involve the implementation of the company’s Orion platform, which includes the company’s NextMAP data integrated with other relevant third party data and with applications for accessing and analyzing the data.   The platform will be used to help with decision making with infrastructure planning, weather related risks, agriculture, excavation, and national security.  Because this is basically a new business for the company, its difficult to peg margins or profitability.  So I’m not going to try.

Nevertheless, just based on the rough assessment of what $125 million in revenue would mean, at this point, with the current stock price of 50 cents the contract is probably mostly priced into the stock.  I maybe should have sold on the run-up to 60 cents, but I decided not to.

The company has suggested in the past that they have a number of RFPs in the works and some of those they have already won but cannot announce until funding is secured.  The upside in the shares is of course a second contract. That could happen next week or next year.  Its impossible to predict.

The other consideration, and something I have always wondered about, is why some large company doesn’t pick up Intermap for what would amount to peanuts, securing what is truly a world class data set and a platform that would seem to be more valuable in the hands of a large company with the resources to sell large projects to governments.  Somebody like an IHS comes to mind.

Pacific Biosciences

This investment idea is a little out of my normal area of expertise and consistent with my desire to expand my investing horizons.   Its an idea I came up with after reading  this Seeking Alpha article which I think does a good job explaining the trend we are trying to jump on.

PACB has 74 million shares outstanding, so at $5.20 (where I bought it) the market capitalization is $385mm.   The company has $79 million of  cash and investments and $14 million in debt.

They are in the business of gene sequencing.  Pacific Biosciences sells gene sequencing machines and related consumables for running tests to map an individuals gene in hopes of detecting a mutation that will diagnose the future susceptibility to disease.  The machine of course is a one-time sale but the consumables are a recurring revenue stream so the business has a bit of a razor-blade type revenue model to it.

The big player in the gene sequencing arena is a company called Illumina.  This is a $30 billion market cap company that did nearly $2 billion in revenue last year.  They dwarf Pacific Biosciences, which did around $60 million of revenue last year.

In fact I read that Pacific Biosciences has only sold around 150 machines.  One interesting thing from their presentation is that for each of the machines Pacific Biosciences sells, they generate about $120,000 of consumable sales a year.   Thus the opportunity for significantly higher recurring revenues is there if they can sell a few more machines.

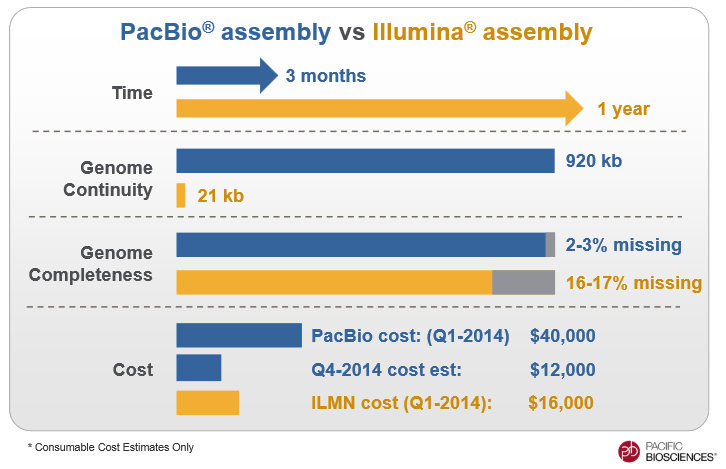
What seems to set Pacific Biosciences apart from Illumina is that their technology produces much longer gene sequencing strings which results in far lower error rates.  Below is a comparison between the two.

comparisonilluminaOne thing I am not sure of is where Pacific Biosciences sits compared to some of their non-public competition.  I was reading through some of the comments on a site called Stock Gumshoe that suggested that some private competition may have as good or better sequencing technology.

Pacific Biosciences also has an agreement whereby Roche will market their product for the diagnostics market in 2013.  In May Pacific Biosciences met the second milestone of that agreement.  The only thing that is a little disconcerting about this agreement is that Pacific Biosciences did not announce how much revenue they would be giving up once (and if) the product is commercialized.

My bottom line is that there are enough interesting things going on for me to speculate in the stock.  The key word being speculate.  There is a chance of wider adoption, there is a chance of an expansion of their relationship with Roche, there is maybe even an outside chance of a takeover.  And its an industry that is clearly growing, is in investor favor, and the stock was at a 52-week low when I bought it.

But I will flatly state that I would not take my comments about Pacific Biosciences too seriously.  My knowledge of this industry remains weak (though its improving as I read more).  They could be, or maybe even have been, surpassed by competition and I would not be the first to know.  So we’ll see how this goes and chalk up any loss to the cost of education.

Portfolio Composition

Click here for the last four weeks of trades.
week-210