Skip to content

Posts from the ‘Uncategorized’ Category

Research: Bank Earnings and CUBI

I went through all my bank earnings reports and conference calls on the weekend. When I say all, it isn’t really a big universe. It consists of: BSVN, BCBP, CADE, CUBI, MLVF, OCFC, PKBK SBFC, SFBG, SI, UBSI.

Nothing super exciting. Still hard to get excited about most of them unless I decide I just want to buy them cheap, close my eyes and wait it out. But I did buy CUBI back, and of course I bought Silvergate (more on that shortly). If there was any theme to all these earnings reports it would be that deposits remain up big and that the deferred loans are coming down fast, in large part because they better come down fast since the bank GAAP holiday is going to end Dec 31st and if these banks haven’t figured out how to make these loans current they are going to have to reserve for them (extend and pretend has been fun while it lasted but its now coming to an end).

The other thing that I think I underestimated was just how beneficial these PPP loans can be. In all honesty, between the extend and pretend CARES act and these PPP loans, it feel like a bit of a free-money wealth transfer to banks if you ask me. But anyway, the loans are pretty much no risk to the banks because the government stands behind them, the banks collect the interest, which are usually in the 2% range it seems and the best part (for the banks) is that they rake in fees for originating the loans and I didn’t realize how significant those fees can be.

Here is where CUBI comes in. They had a SBA lending program heading into the pandemic so they were well-placed to ramp up the PPP lending program once it was announced. They have originated $5 billion of PPP loans. That works out to 30% of the loan book as of the end of Q3. That’s a lot. Most other banks I’m looking at are 5% or less.

Anyway Customers expects to generate $100 million in pre-tax origination fees from these loans. They must be getting a 20 bps origination from the government to originate.

They recognize the fees when the loan is either forgiven or paid back. Given that we are in a ‘free for everyone’ world now, these loans are going to be forgiven and relatively soon. Customers figures 90% of loans will be forgiven by the end of the first half of next year.

~$100 million over the next 3 quarters is some decent juice to earnings. Consider that Customers net income was about $60 million last quarter and that was with $12 million of fees from PPP.

Meanwhile Customers is bringing down their deferred loans like a good little bank – from 7.3% in Q2 to 2.6% in Q3, and they operate in New York and New Jersey, where the virus pig is further through the python than most places.

Everyone hates Jay Sidhu it seems and maybe there is good reason but he is making some decent decisions here. He was quite adamant on the call that he is not going to stand by while the stock continues to trade at the rather shockingly low multiple of 0.45x tangible book. If they have to, he said they will take the nuclear option:

We are working on scenarios to shrink the balance sheet and have massive stock buybacks so that the appropriate valuation of the company is being reflected by — into the value of the organization.

Anyway, may not be the best run bank in the world, but does it really deserve to be priced as one of the worst?

Here are my notes on the quarter:

  • so first: Bank will earn approximately $100 million in pre-tax origination fees from PPP loans, significantly adding to its common tangible equity in 2021 – that’s a crazy amount of fees for a company with a market cap of $400mm
  • they recognized $12mm of fees in Q320 – will recognize the rest over life of PPP loans, expect 90% to be forgiven in H12021
  • total PPP loans are $5b – of total loans of $16.4b so about 30%
  • additional PPP loans in Q3 contributed $10mm of Net Interest Income
  • PPP loans have 1.97% yield on avg
  • expecting 95% of their PPP loans to be forgiven – half of their loan balances are below $150k
  • Core EPS of $38mm or $1.20 per share
  • their NIM declined to 2.86% – seems similar to other banks
    • are projecting NIM in 2.9% to 3% range for FY 2020
  • deferments are down quite a bit – from 7.3% to 2.6% – now $302mm loans
  • for reference here is the relevant section of CARES on loan deferments:

Temporary Relief from Troubled Debt Restructurings. A financial institution may elect to suspend requirements under U.S. GAAP for loan modifications related to the COVID-19 pandemic that would otherwise be categorized as a troubled debt restructuring and to suspend any determination of a loan modified as being a troubled debt restructuring, including impairment for accounting purposes, as a result of the effects of COVID-19. Any such suspension (1) is applicable for the term of the loan modification, but solely with respect to any modification, repayment plan or other similar arrangement that defers or delays the payment of principal or interest that occurs during the applicable period for a loan that was not more than 30 days past due as of December 31, 2019; and (2) will not apply to any adverse impact on the credit of a borrower that is not related to the COVID-19 pandemic. The election may begin effective March 1, 2020, and end at the earlier of December 31, 2020, or the date that is 60 days after the date on which the national emergency declaration related to COVID-19 is terminated. Financial institutions are directed to maintain records of the volume of loans involved so federal banking agencies may collect data about such loans for supervisory purposes. (Section 4013)

  • key point is that the deferments end Dec 31 2020 right now
  • hospitality is $404mm (3.5% of total loans) and 31% in deferment – so about $120mm or 40% of their deferments are hospitality
  • avg loan to value in hospitalty is 65% – seems pretty low, if these loans do get called they’d get back their money on sale you’d think
  • their multi-family portfolio has vacancy rate fof 3.4%, is 60% LTV, 4% of it is in deferment
  • consumer loan deferments down to $25mm from $60mm
  • NPAs are still very low, at 0.34% but this is of course because of the deferment
  • their reserves are way higher, at over 2%, or $155.6mm
  • guiding to $3/share core earnings for 2021
  • also to mid-high single digit loan growth (excluding PPP)
  • deposits were up 21% to $10.8b yoy
  • expect funding tailwind from $466mm of CDs that mature at YE and will reprice down significantly – that is close to 5% of interest bearing deposits
  • saw loan growth of $6b, to $16.6b – of that $5b were PPP loans, so about $1.6b of loan growth outside of PPP
  • this just seems too low to me: we are trading at about 43% of September 30 book value and only at about 4x 2020 and 2021 earnings.
  • on stock buyback:

are working on scenarios to shrink the balance sheet and have massive stock buybacks so that the appropriate valuation of the company is being reflected by — into the value of the organization.

  • I’m not exactly sure what this is but it’s a little concerning:

our specialty lending, lender finance business is the largest component of that. It’s an approximately $1 billion business for us today, and that will be driving majority of the growth. That’s a business that is predominantly at approximately 65% advance rates on a pool of collateral with collateral swaps in the event that there’s ever an issue. And as we’ve modeled it out, you’d have to be at a reception multiple times as big as a great recession to ever experience $1 of loss. So that’s the biggest component of our specialty niche businesses.

BankMobile

  • expected to close by YE
  • have “no intention of owning equity” in BM in long run
Research: Daseke

I’ve been following Daseke ever since they took over another company I used to own called Aveda Transportation (I think that was 2018?). There was a large contingent payout for Aveda based on EBITDA that quite honestly I think us shareholders of Aveda may have been screwed out of, but whatevs, that business basically imploded with oil and has been a disaster for Daseke so it turned out okay anyway.

Daseke put together another good quarter. That is two in a row. Some of the sequential improvement was one-time in nature but the new management team has clearly turned things around since the old founder Don Daseke was let go.

I don’t own the stock but I do own some of the old SPAC warrants which covert at $11.50 and expire Feb 2022. They remain a long-shot but I paid about 15c for them and it just seems like on the off-chance that Daseke continues to improve through 2021, maybe we get an infrastructure bill, maybe wind continues to take off (they ship a lot of turbines on their flatbeds) that the warrants are as good of a moonshot as anything else right now.

That said, while the quarter was good, it seems to have a lot of one-time tailwinds so I’m not sure how sustainable this stock move yesterday is.

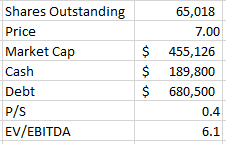
Here’s where we stand with share structure.

So based on TTM EBITDA I see them at about 6x. Its not incredibly cheap or expensive.

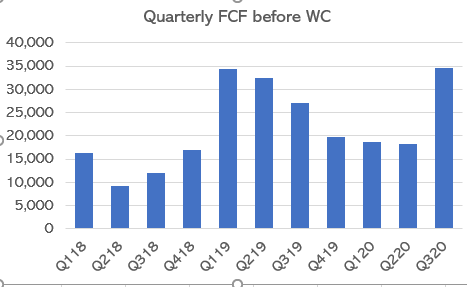
They did generate a lot of free cash again in the quarter:

The thing about the warrants is that because of the leverage, a relatively modest change in valuation or operational improvement can make a big difference to the stock price. So if they get to trade at 8x EBITDA instead of 6x EBITDA (or if, conversely, they can keep the EBITDA improvements coming and say, get to a $50mm per quarter run rate sustainably and a 6x multiple), the common goes to $12 and the warrants are in the money.

So its not impossible. Unlikely? Yes, but not impossible. A moonshot.

Below are the notes from the quarter as well as the notes from the Q2 that I had made previously and I don’t think I ever posted.

Q320

  • another big improvement to operating ratio – 92.5% for the quarter down from 96.5% in Q220
  • but sounds like this is a bit of one-time anomaly, not really representative of further business improvement
  • still focused on getting operating ratio below 90%
  • expecting OR improvement in 2021 over 2020
  • up to $15mm of net income – 22c EPS
  • aEBITDA of $56mm
  • have delivered $156mm of fcf year-to-date
  • net debt is now under $500mm – down $135mm yoy
  • they finished the divestiture of the Aveda shitshow!
  • still seeing lower freight volumes in flatbed
  • specialized revenue was flat yoy excluding Aveda
  • all the EBITDA improvement yoy was from specialized
  • had a big (one-time??) benefit from disruptions in wind and high security – this is a lot, $15mm added to EBITDA from these
  • kinda seems like these one-timers were all the uplift:

So Q2 was 96.5; Q3, 92.5 million, if I do the back-of-the-envelope math on the $15 million benefit you mentioned this quarter from nonrecurring items or unique items, I guess, this quarter, it implies virtually all of — kind of the sequential improvement was onetime in nature.

  • also saw tailwind from COVID cost reductions that won’t continue
  • tailwind from wind is contining at least in part in oct
  • very difficult to forecast wind – they don’t know how 2021 will look, too project based
  • expect insurance to be $2mm per quarter headwind in 2021
  • kinda guided to an okay Q4 but seasonality will kick in and make it down a bit
  • expect capex of $75mm to $80mm in 2021
  • still seeing many of their industrial markets trending down
  • seeing pockets of strength in roofing, pgysum, commercial glass
  • turnover: finished this quarter, I think, just under 62% in total turnover, which is down from a year ago and down sequentially as well. So we’re having a good year from a turnover perspective – I think its been around this level for at least 2 years now

Q220 results

  • they had an operating ratio for the combined company of 96.5%
  • best operating ratio since they went public over 3 years ago
  • yoy operating ratio improvement of 250 bps
  • divested Aveda Transportation and Energy Services – collecting $48mm from PP&E sales so far – but with winddown costs will be $7-$10mm cash drain
  • o&g exposure will drop to 2% from 13%
  • core business revenue was down 13% in Q220 excluding Aveda – EBITDA down 5% – EBITDA was $45.8mm excluding Aveda – Aveda was a drag of $1.8mm EBITDA
  • they actually showed an EBITDA increase in Q220, up 13%
  • are investing in their fleet – lowered average truck age from 3.8y to 3.4y from start of year
  • it wasn’t totally clear to me but sounds like avg age depends on specialized vs. regular flatbed fleet
  • of the 9 operating companies they have, several are operating at “sub-90%” operating ratios today
  • their specialized segment is what includes Aveda – it saw revenue of $221.5mm and EBITDA of $33mm – so it is a big driver of bottomline
  • their specialized segment OR is 90% – that is up 410 bps yoy
  • flatbed segment had revenue of $137mm – this was down 22% yoy
  • but EBITDA in Flatbed was $20.4mm – which was up a little yoy
  • they decreased net debt $118mm yoy – leveraged at 3x which is below 4x of covenant
  • they guided to capex of $60mm to $65mm – this must be $160-$165?
  • maintenance capital is in $75mm to $100mm range
  • their goal is to get operating ratio down to 90% across all the business lines
  • segments that were strong: lumber, wind, defence – while aerospace not likely to come back soon, metals is weak
  • July trends are flat – improvement through April, May, June but July is flat
  • they expect to see continued OR improvement through the rest of the year
  • CEO was “shocked” at resilience of Daseke model – how well freight held up in Q220

Research: Eastside Distilling

I think* that the market might be missing something here. It looks to me like the sale of Redneck Riviera (RR) yesterday should be a bigger deal than the stock price is suggesting today.

I looked at the stock a few months ago. I wasn’t totally convinced about the cash position and losses. They were turning things around but still losing money. But this sales changes that picture quite a bit I think. They are selling a money-losing, albeit new and growing (pre-pandemic) brand for, from what I can tell, around 3x revenue.

On their Q2 call they talked about their canning business (called Craft Canning, canning 3rd party bottling, canning, and packaging services for existing and emerging beer, wine and spirits producers). They said “A company of this nature typically is valued at 1.5x sales or 6x EBITDA.”. In the Q&A they qualified that as a valuation for a PE investor interested in this type of business.

I do the math on this and Craft Canning is probably worth $15mm to $18mm itself (Canning and Bottling was $2.56mm in Q220 at 30% EBITDA margins). Unless I’m missing something, that is more than the company is worth right now after they get the $8mm from RR.

I might be missing a piece, still digging (need to look at the share comp for Azunia still), but based on what I see so far, I think this stock should be higher.

Notes from last Q2 and from RR sale.

  • $1.9mm of cash
  • $5.7mm of debt
  • another $15mm of deferred consideration for Azunia which is just shares I think
  • 10mm shares outstanding at $1.40 is $14mm
  • so its an EV of $20mm roughly and that is before $8mm from RR sale – so $12mm now versus CC which is probably worth $18mm

Q220 results

  • cash burn cut in half from Q120
  • Craft Canning has dominant position in Pacific NW
  • CC revenue up 20% yoy in Q220
  • CC “doubled from first quarter to second quarter”
  • customer list for CC was up 30% since March
  • expect CC to have 35% EBITDA margins in Q320:

The current EBITDA margin from this business unit is well over 30% in 2020. We estimate the division can possibly reach $10 million in sales.

  • CC benefiting from pandemic:

“before the pandemic, 50% of beer was being put in kegs, and then it wasn’t. I would suggest this change has legs.”

  • they peg canning operation at 1.5x revenue, 6x EBITDA
  • CC was $2.56mm of revenue in Q220 – so even ignoring growth – is probably worth $15mm-$18mm+ on its own
  • are in process of downsizing overhead, made expense cuts of $2mm (annually?)
  • they do mention potential for outsourcing
  • Redneck Rivera revenue was down 30% yoy – from 10Q this was $0.2mm – suggests RR sales were about $670k pre-pandemic
  • Azunia revenue down 38% yoy because it depends on on-premise business and that was shut down
  • Azunia is relatively new brand – they acquired Azunia Tequila in Sept 2019
    • at the time had TTM sales of $3.5mm on 13,000 cases sold
    • sold into on-prem location in West and SE US
    • they said expect a positive EBITDA impact from Azunia in 2020
    • acquired as all-stock transaction
    • it looks like 850k shares up front, 350k shares after 18 months
    • another 1.5mm shares if Azunia ups revenue to $9.45mm in Y2
  • Portland Potato Vodka revenue was up 18% yoy
  • Burnside revenue up 4% yoy
  • Pacific NW beer + wine market is around $100mm, they have about 10% of it
  • on craft side they are only in Oregon, Wash, Colorado right now
  • had 11 delivery trucks heading into quarter, brought new one on in Q2, have another 2 on order

Sale of RR and Q3 Update

  • announced Q320 revenue of $4.5mm to $5mm – this would be up from $4mm in Q220
  • also further EBITDA improvement
  • selling RR for $8mm
  • so that alone is very good
  • RR was clearly a money loser, not sure how much
  • I think RR revenue was about $2.7mm or so pre-pandemic so they are selling it at almost 3x revenue

More on Fastly and Limelight

This whole Fastly situation is so interesting. I just don’t see what the market sees in this company (other than growth of course).

Last night Fastly reported earnings and they weren’t all that great from what I can see. Lots of interesting tidbits but the first is on Tiktok.

So they lost most of the Tiktok business in Q3 and it continues to leak in Q4. They aren’t even guiding for any Tiktok revenue in December.

If you remember, the basic question that started me down this whole wormhole was – if Fastly is so great and Limelight Networks so shitty, then why is Tiktok leaving Fastly and looking at signing a deal with Limelight?

Well Fastly blames the Tiktok loss on regulations (ie Trump), which kinda makes sense. But I don’t quite get why Tiktok would be ramping down Fastly when the US ban is on hold and we don’t even know if it will happen at all?

I thought this was an interesting exchange from the call. Fastly was asked a very simple question: Is Tiktok moving traffic as a temporary measure?

The right and easy answer to this question is something like: Yeah we hope so but we will have to see how the regulatory side plays out.

Instead, this was Fastly’s answer:

Yes, Robert, thank you for the question. I think this is a very dynamic situation. I come back to that. I think if you think about the time line over the last few months since we last spoke, a lot has changed. A lot that we thought was going to happen may not happen. So I think — I’m not sure we are in certainly no position to have any proprietary insight into any of this situation. I think what we would say, in general, is it’s very dynamic. We don’t have clarity on the process, and we expect the situation to remain unresolved for a period of time. And so I don’t have any more insight in terms of what that looks like.

 I think from the publicly available information that we see, it is very clear that it is important for any customer in this position to be able to continue to serve their customers if and when certain vendors are prohibited.

I think its a legitimate question to ask why Fastly didn’t just say we hope so and instead answered with the above gobbledygook.

Second point. Fastly made a fairly big acquisition in the quarter with Signal Science. It was like $775mm, so not inconsequential. SS is going to add $8mm of revenue this quarter. That is actually a sizable chunk of Fastly’s yoy growth in the quarter. It means without the acquisition they’d only be growing 25% yoy.

Did you know that Fastly only has 40 US patents (they do have another 47 pending)? About the same as Limelight.

I’m thinking more and more that the differences between the Limelight business and the Fastly business has a lot of smoke and mirrors to it (as well as some legitimate substance). Yes, Fastly is developer focused (as they tell us ad nauseam in their 10-K which btw reads like a marketing letter) and yes they have better technology and yes because of that they can charge higher margins (which are charged to mostly smaller players btw). But for the big traffic players (like Amazon, which is Limelight’s biggest customer by far, and Netflix, which Limelight lost the business of a while ago when they started their own CDN) what matters is price because at the end of the day these guys are just pipelines for data.

Meanwhile Limelight is getting into the edge computing side that Fastly excels at and is growing that business so it will be interesting to see how that piece plays out.

So no, Limelight is not worth a huge sales multiple and right now it doesn’t have that. I just think its fallen too far.

Fastly, on the other hand, does not seem to be worth 25x sales. Take a look at the chart. This was a $20 stock in 2019 and for the first few months of 2020. It didn’t do much of anything.

You have to think that this year, with everyone online, their pricing model (which is volume based) should be booming, yet their growth is kinda meh and the stock price, even after this collapse, has still tripled.

This isn’t a Limelight is better than Fastly argument. It is more a compare these two companies, which have similarities and differences, and ask if one deserves to be worth 12x more than the other?

I just don’t see it.