Skip to content

Week 39: Slipping

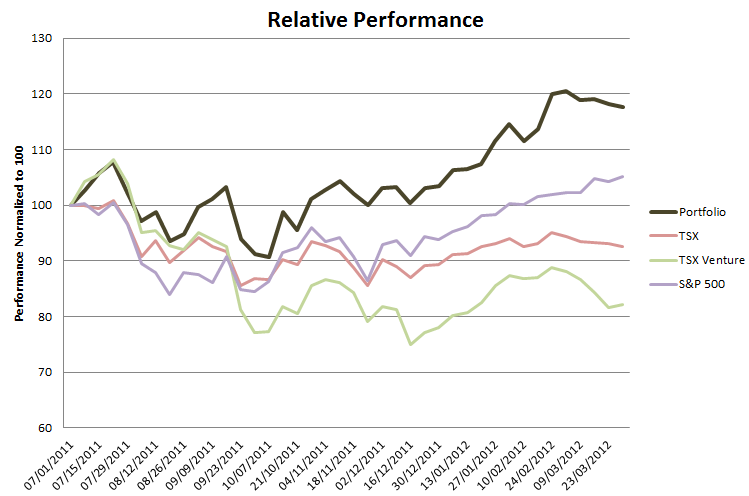
Portfolio Performance

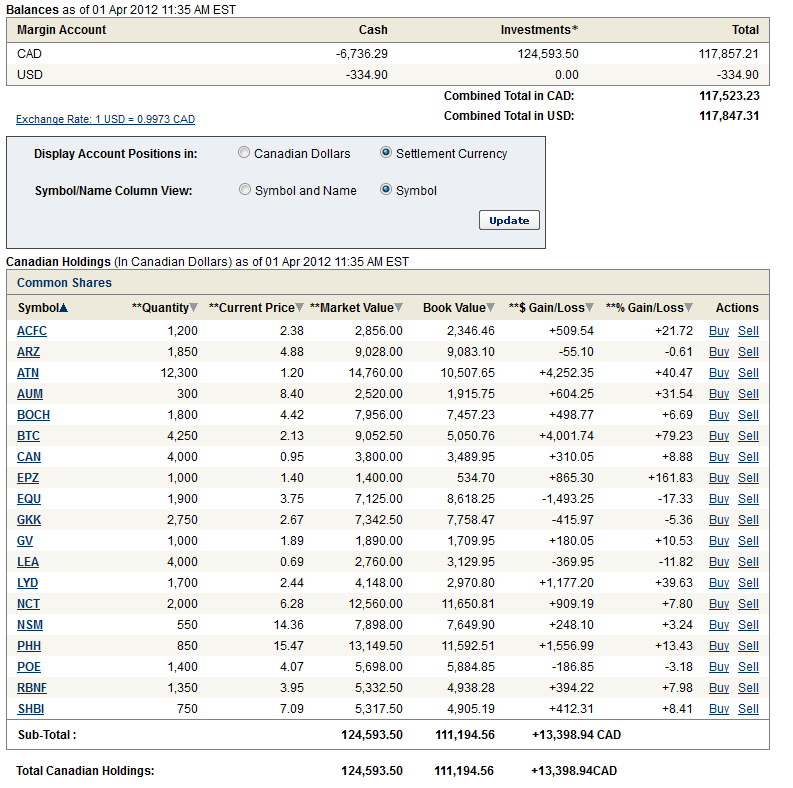
Portfolio Composition:

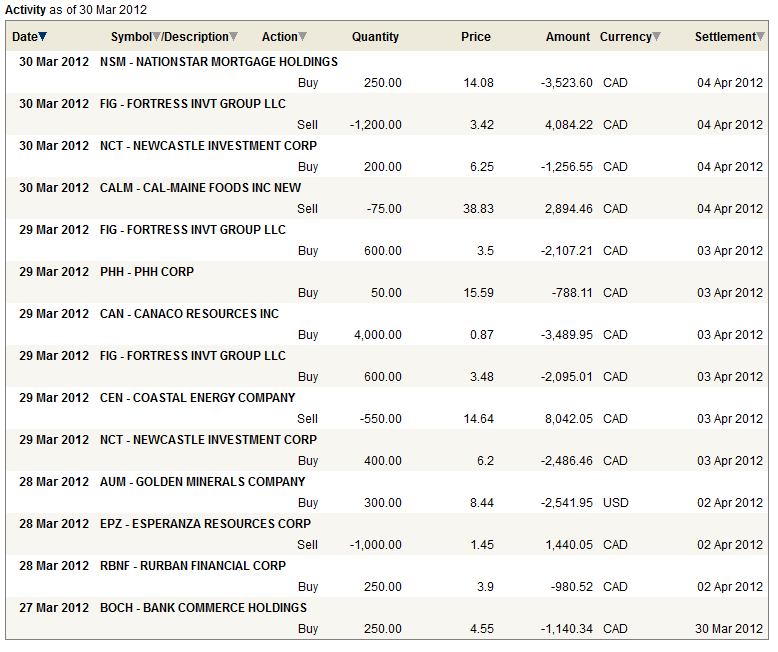
Trades:

The annoying theme that has punctuated my performance over the past few weeks has been the out-performance by my regional bank and mortgage financial service companies and their eclipse thereof by the under-performance of the oil and gold stocks that I own.

Some of the things I am doing are working.  Some of them are not.  Its time to go back to the simple axiom that I first heard from Dennis Gartman:  Do more of what works and less of what doesn’t.

That is exactly what I have been trying to do over the past month.  I have slowly (and probably less then efficiently) been reducing my gold and oil positions.  With each subtraction I add to my banks, my mortgage originators and servicers. I’ve also been looking to other places to invest.

No question I would be better off (financially) today if I had dumped the majority of my oil and gold stocks a month ago and focused on my current convictions in banking and mortgage servicing.  Unfortunately,my thinking takes more of a plodding pace, and I rarely am so quick to recognize the truth.  It took me a month to begin to recognize the impact of the LTRO.  It took me about the same amount of time to recognize that I should be out of all the golds and oils but the one’s I truly have conviction in.

This week I sold out of Coastal Energy. With the proceeds I added to Newcastle Financial, PHH Corporation and Nationstar Financial.  Earlier in the week I added to a couple of my bank holdings, Rurban Financial and Bank of Commerce Holdings, while subtracting a portion of Esperenza Resources.

I also returned to Canaco Resources this week.  I wish that I had done with my other gold stocks what I had the sense to do with Canaco a month ago.

As for the week that comes, I don’t see many more changes on the horizon.  I am comfortable with most of the stocks I own.  I have become heavily weighted to US Financials and to Mortgage originators and servicing.  Now it is time to wait and see if the scenario plays out in the way I expect it to.

Selling: Coastal Energy, after the mistake of buying back

Two weeks ago I looked pretty smart when I sold 2/3 of my position in Coastal Energy at a little over $18.  Last week I looked shrewd when I bought back that position at $16.50.  This week I looked stupid as the stock tanked and I sold.

Its quite possible that I sold at what will prove to be the bottom in the stock.  That would be unfortunate.   But while the timing of my transaction may have sucked, I believe the spirit and intent was right on the ball.

I sold out of Coastal on Thursday after they announced their end of year results.  They had also announced disappointing results at Bua Ban South on the same day (actually the night before) but that had nothing to do with why I sold.  I sold because the year end results showed a disturbing decline in production offshore.  The company did not address this decline very clearly in the news release.

Here is what the company said:

“2012 has also begun extremely well. We have drilled and tied in a handful of additional wells at Bua Ban North which have further boosted production. These wells were tied in during the month of February and brought average offshore production for the entire first quarter up to 21,100 bbl/d. Our current offshore production is 22,500 bopd.  

The  company had previously announced a little over a month ago that they had 26,000 boe/d of production offshore.

The Company has two more wells to bring online at Bua Ban North. Current offshore production is averaging 26,000 bopd, bringing total company production to 28,000 boepd. The rig is now being mobilized to Bua Ban South and is expected to spud the first well there by the end of February.

Now I may have gotten worked up over nothing, and I know of a few players smarter than I that used the dip as a buying opportunity.  $15 is a reasonable price for the production that Coastal has, and there is the opportunity that they will find much more.

Nevertheless, it was what I didn’t hear as what I did hear that made me sell.  I have been in too many situations that followed this script.  And more often than not, the reason that the reasons aren’t stated is because they are something to worry about.

Is that the case here?  I have no idea.  Maybe its operational, mechanical, one-time, short term, or some other adjective that can be dismissed and forgotten.  But the company didn’t say that, when they could have said that, and instead they didn’t say much at all.  So I took the approach that I will ask questions later.

Coastal has been a great stock for me.  Even though I sold out for good after a 25% decline (from $20 to $15) I still pulled off almost a 4-bagger.  It was probably my history with the stock that kept me in it as long as I was.

So of course I wish I would have sold it 3 weeks ago.   But I have learned that decisions need to be made based on current circumstances.  If you do not do what you believe is right today because of a mistake you made in the past and if you hope instead for a return to those past conditions to correct the mistake, you will get killed more often then not.

When I couple the uncertainty of the news release with the opportunity I see to redeploy that capital somewhere else where I believe the opportunity is greater (see my recently finished post on Mortgage Servicing Rights and my post from last week’s portfolio update where I stepped through the breakouts of numerous regional banks), it seemed to me the right thing to do.   Perhaps in a couple more weeks it will look stupid for having sold it when I did.  Be that as it may, you can’t forsee the future, you only have the past as a guide.

Buying: Back into Canaco Resources

I think things have gotten a little stupid with Canaco. It goes down and it goes down and it goes down.

I bought the stock on Thursday at 87 cents.

A quick look at the company’s March presentation shows that cash on hand is $110M.  The market capitalization of the company is down to $174M.  That puts a value on Magambazi of $64M.

As Steve T has pointed out in the comments, subtracting cash on hand from capitalization for a junior is not a best practice.  The cash will inevitably be eaten up by drilling.  But Canaco can do a lot of drilling for $110M and I don’t think its a terrible bet to think that they find some more gold before they go through the cash.

I still have concerns about the Magambazi deposit.  The fact that the resource is being delayed until May suggests that some of my original concerns are valid (I did a detailed analysis of the Magambazi deposit here).  The company stated it this way:

However challenges encountered with final assembly of the large volume of project data necessitates a revision to the completion date of the initial mineral resource, now anticipated by May 15, 2012.

If I were to read between the lines, final assembly would suggest to me that there has been some trouble outlining the resource, perhaps, as I noted in my original post, because it pinches out so abruptly in spots.

So things are not perfect.  But there is a price for everything.  The stock is down from $5 to less than $1.  Even when I was at my most conservative I figured they had at least 1.5Moz at Magambazi.  Its still a decent deposit and it has the opportunity to get bigger.  The market clearly overreacted to the upside in the stock last year.  In my opinion, it has now overreacted to the downside.

Atna Resources: Why I haven’t sold a share

A couple of weeks ago Gecko Research (which seems to be, oddly enough, a Swedish based, Canadian Gold junior company research firm) put out a report on Atna Resources.  The report is available here.

Most of the report is full of your typical fare.  These are their properties, this is their management, yada, yada, yada.

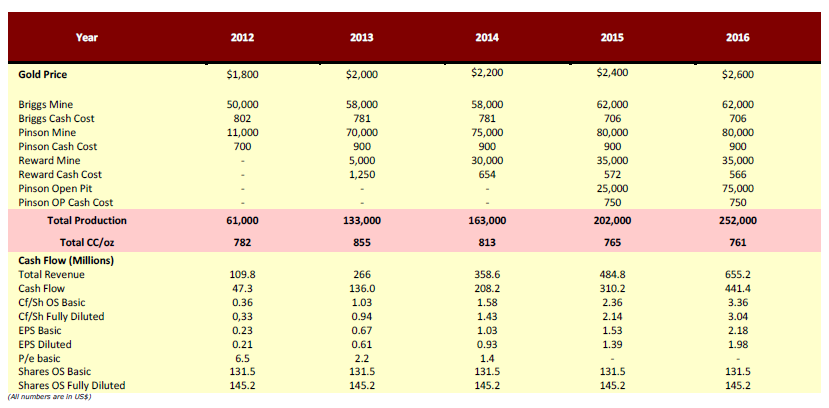
Then I got to this table:
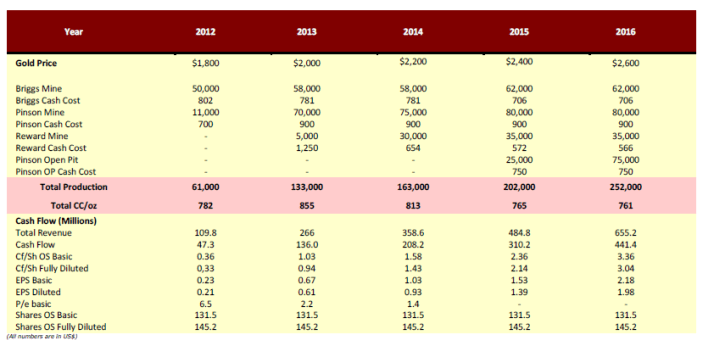
I did a double take when I looked at the 2013-2016 cash flow numbers.  $1 per share in 2013?  Is that possible?  Could Atna really generate that much cash flow that quickly?

The work I have done

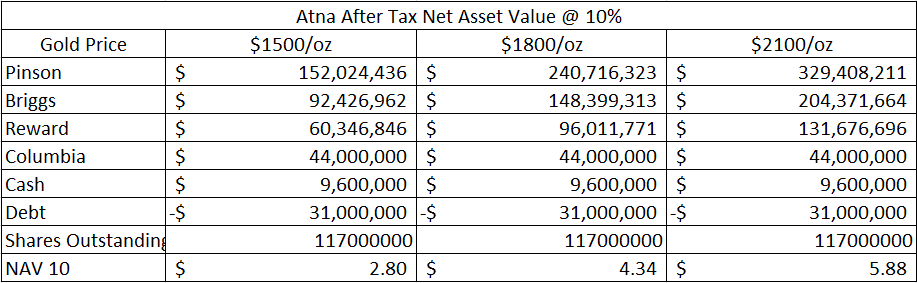
When I looked at the table and contemplated the numbers it occured to me that I had never actually looked at the year by year cash flow that the company might generate once Pinson is up and running.  What I spent quite a long time looking at was the net asset value of the company.  I did that analysis right before Christmas.

What I found out was this:
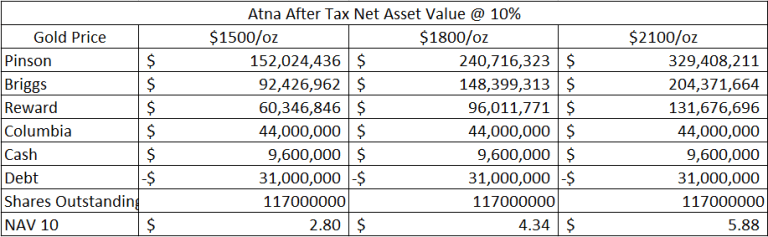
After I came up with the NAV estimates I basically wrapped up my analysis  and put it under the Christmas tree.

See, I don’t have oodles of time to do miscellaneous research.  When I get a set of numbers like the one’s in the table above, where the only conclusion that can be drawn is table pounding buy, I don’t tend to spend too much more time splicing out the details.  Atna is going to make a lot of money and that is not baked into the price of the stock.  End of story.  Go buy the stock.

Anyways that was my thinking at the time.  So I never really looked at the year by year cash flow in any detail.  Until I read the Gecko report and that made me curious.  Could it really be that high?

Looking at cash flow

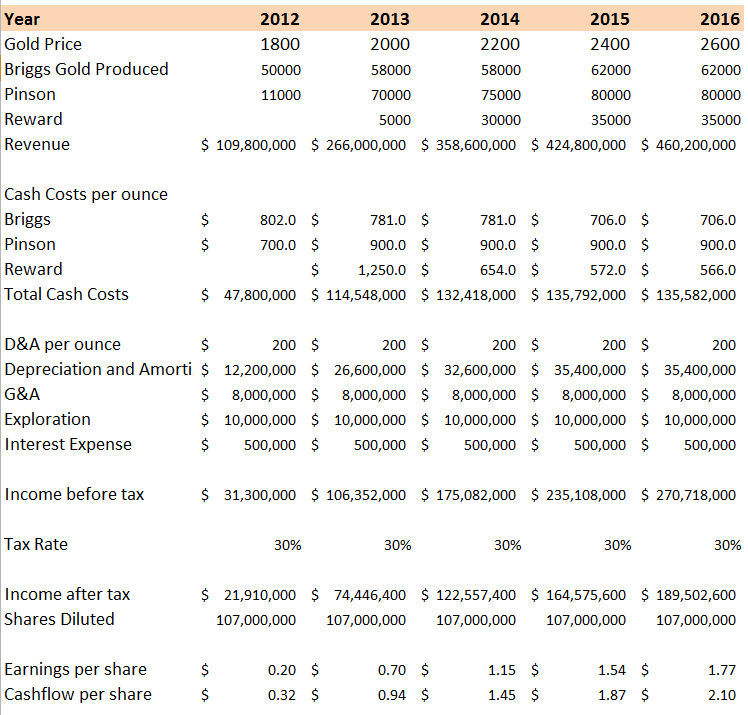
The best way to check the numbers is to run them yourself.  I took the inputs Gecko provided and created my own little cash flow spreadsheet.

The first thing that should be pointed out is that Gecko is using, to put it mildly, optimistic gold prices.  I don’t think there are any analysts out there using $2600 per ounce gold for 2016.

Second, I had to make some assumptions. For D&A I assumed a constant $200/oz produced which I think is likely going to be on the high side.  For G&A I used $8M per year, which was based off of the average of what I saw from some other companies (Argonaut, Aurizon, Allied-Nevada, Alamos), and no I did not intend to only compare the company against other companies that started with the letter A.

Exploration was assumed to $10M per year, which may be on the high side but Atna has a lot of other properties so I wouldn’t be surprised if they start working on them once they have the cash.

Taxes are based on the nominal rate provided by the company.

The results I came up with were not too far off what Gecko did.
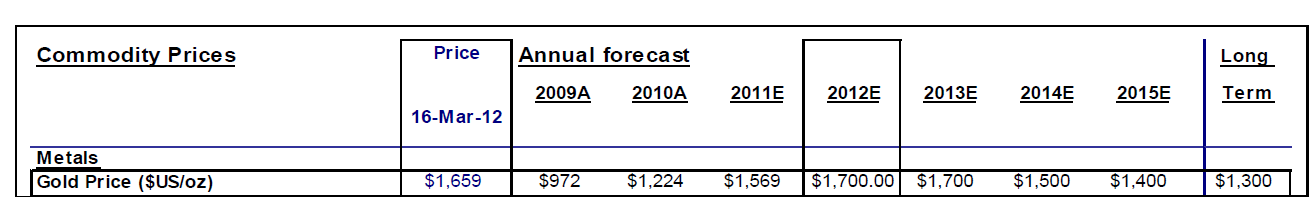
And using the BMO price deck…

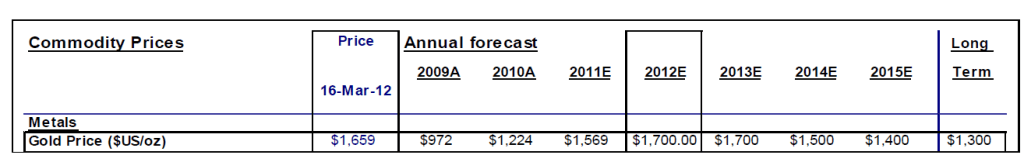
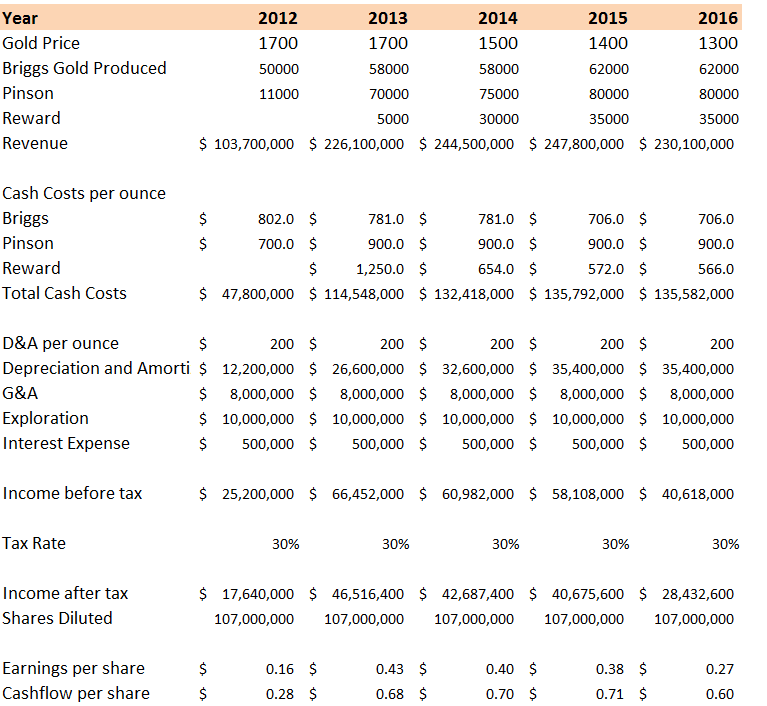
Since I had the spreadsheet built I started to look at other scenarios.  Probably the most illustrative was to look at what Atna might be generating based on the BMO price deck.   The BMO price deck could be considered to be a “realistic” price deck, with the term realistic being defined as generally accepted until it is proven to be horribly wrong.

But that is for another rant.

BMO is predicting the following gold price going forward:
You still get some pretty gaudy cash flow numbers:
Financing?

Another point that was brought up in the Gecko report was the chance of a financing.  Gecko thinks this is going to happen.  I hadn’t really thought about the possibility too much until they brought it up, but I can see the logic.

Even though Atna has the possibility to grow only from internal cash flow, we think that Atna will raise money through an equity financing some time during H1/12, likely during Q1. We believe C$20 million will be sufficient to take Atna through 2012 with the development of Pinson and to fast track the studies of Pinson Open pit. This will also assure that long lead-time equipment for the Reward Mine will be ordered in time. We assume an equity raise will be done at C$1.50 by issuing 13.33 million shares.

It’s a fair point.  While they can probably squeeze by without one, they don’t have much cushion.  As long as its done at a high enough price, I have no problem with it

Haven’t sold a share

Over the past month Atna has gotten its butt kicked along with the rest of the gold sector.  It probably went too high too fast and now its come back to earth.

I don’t love gold right now. With the economy improving I can imagine that selling pressure will remain on the metal.  My favorite sector right now, the regional banks, are the antithesis of gold.  Its hard to imagine both going up together.

Yet I haven’t sold a single share of Atna.  I bought more shares when it dropped into the $1.12-$1.15 range late last week.  I don’t really expect much upward pressure on the shares until they begin to announce more news about Pinson.  In particular I think the full permitting of the project would be big news.