Skip to content

Shadow Inventory and how an improving US Economy begets an Improving Housing Market begets and Improving US economy begets….

FT Alphaville did a nice piece on Friday talking about shadow inventory in the United States. To sum it up:
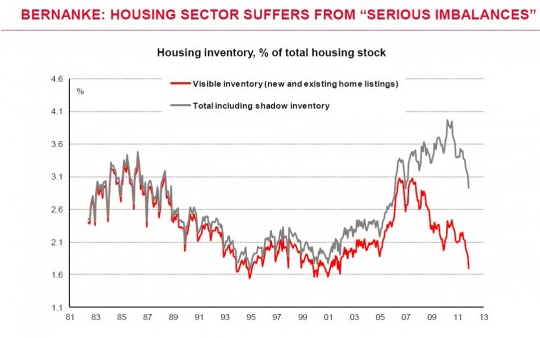
Two things about this graph.

  1. Visible housing inventory is approaching a low not seen in 30 years.
  2. You can’t take a shadow inventory number at face value.  You have to understand how it was estimated.

First a little bit about shadow inventory

I want to talk for a second about shadow inventory. I wrote this explanation about shadow inventory in Letter 23:

Laurie Goodman (who I first learned of from ftAlphaville fame) pegged shadow inventory at 11M (which is an amazing 20% of housing mortgages outstanding).  Mark Fleming pegs it at 2M.  Both analyts are using the same data…How is this possible?  Its all in the assumptions.  Shadow inventory is really just houses that are expected to go into default at some point.  There is nothing particularly nefarious about the concept, even though the name suggests it is some sort of inevitable flood of housing supply.  It may be, but it may not.  It depends on what happens.  Laurie, to come up with her 11M number, assumes a fairly large number of prime mortgage defaults, including some that are currently with LTV (loan to value) of less than 100%.   Laurie also looks at 60 day past due as her “bucket” from which to extrapolate current nonperforming loans.  Mark on the other hand, uses 90 day past due, and does not include currently performing prime mortgage defaults.

I did a bit of investigation and the number used in the above graph is the CoreLogic number, which is the lowball Mark Fleming estimate from the above quote.  According to CalculatedRisk that number is comprised as follows:

Of the 1.6 million properties currently in the shadow inventory, 770,000 units are seriously delinquent (2.5-months’ supply), 430,000 are in some stage of foreclosure (1.4-months’ supply) and 370,000 are already in REO (1.2-months’ supply).

The thing about the shadow inventory is that if what you see is what you get, then we are almost through the worst of it.  Looking at the above categories that comprise the shadow inventory estimate, they total about 1.6M homes.  If there was a little bit of confidence in the housing market, and you began to see sales returning to pre-crisis and pre-boom levels, you would run through those homes quite quickly.

As well, it must be kept in mind that the month-of-supply number is assuming a continuation of a level of sales that is a historically low level.  Rising sales would help eliminate shadow inventory and real inventory much more quickly than the monthsof-supply number might suggest.

The most basic point here is that shadow inventory is not an inevitable houses-on-the-market number like visible inventory is.  Shadow inventory is a “houses that are likely to go on the market” number where the definition of “likely” is a function of whether those home owners have jobs, how low interest rates are, whether the refinancing market is liquid enough to let home owners with high interest rate mortgages refinance to low interest rate mortgages, and probably most ambiguously, what homeowner think about the future prospects of the housing market.

Laurie Goodman and her firm Amherst Securities have some of the most pessimistic numbers on shadow inventory.  She does an excellent job describing the methodology they use at her firm on this conference call.  Amherst ends up with the following estimate of shadow inventory:
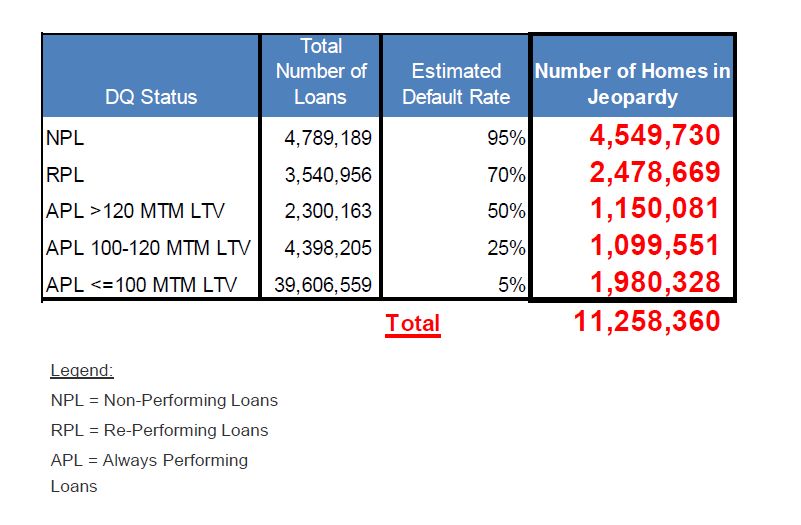
This is a huge number.  Much bigger than the 1.6M number that CoreLogic is using.  If Goodman is right then we are years and years away from a housing recovery.

But lets go through this.  Amherst uses 60 days past due to define nonperforming loans.  Reperforming loans are loans that were in default before but aren’t now.  MTM LTV means mark to market loan to value, so a 120 MTM LTV is basically saying that the loan is worth 120% what the house is worth.

I would say that you can make vastly different assumptions about how many loans in each of these categories will default depending on whether you assume the housing market is improving or not.

Somewhat paradoxically the true amount of shadow inventory is going to be determined by the perception of just how much overhang exists in the housing market.  To put that more bluntly, would you walk away from your house right now if you saw the housing market turning up?

You would be a lot less inclined to I think.

And all of this brings us to the US economy

I have two graphs here to prove my point.

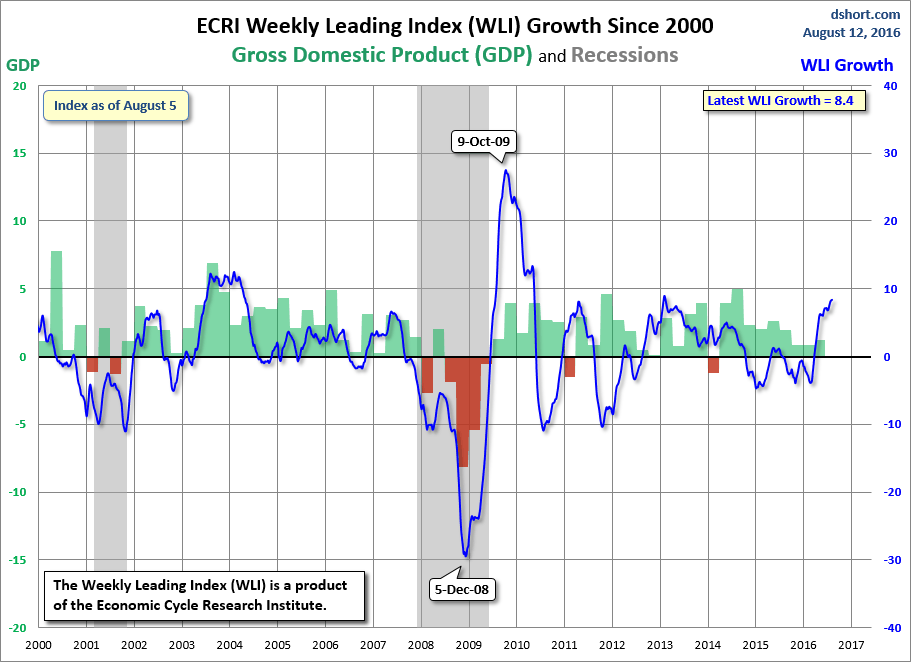
When I started dumping stocks and raisigng cash in the late summer and earlier fall it was partially because of my uncertainty about Europe.  But it was also partly because of my concern that the US economy was slowing down again. The big reason for my concern was that the ECRI leading index was falling again.  I am reluctant to be too invested in stocks when this indicator is dropping.   Once it starts to drop, I’m not all that sure that anyone knows when its going to stop.  It could stop and turn around relatively quickly, suggesting a soft patch in  the economy, or it could fall precipitously, indicating a sustained move back into recession.

The move down ended at the end of the last year, and the last few weeks the uptrend has shown itself to be persistant.  Such persistance must be noted.
The second graph is simply jobless claims.  Jobless claims are the single best indicator of the health of the economy.  You simply can’t deny that claims are heading down, and that the trend down is accelerating.

Growth in an economy builds on itself.  Growth begets growth.  Taking it back to the housing market, I think that these early signs of true growth in jobs could begin to snowball into a housing market.  Jobs beget stabilizing housing prices which begets greater housing activity, which begets rising prices, which begets falling inventories (and non-materializing shadow inventories), which begets the need to build new homes which begets more jobs. And so on.

Economies as large as the US economy do not turn on a dime.  But when they turn a lot of the viscious cycles that had amplified the downturn become virtuous cycles that amplify the move up.   I am of the mind that we may be in the process of making such a turn right now.
PHH and one way to bet on a turn in the US economy

PHH is one of those stories where the more I look at it, the more it makes sense to me, and the more it makes sense to me, the bigger the position I am willing to take.

I love to add to a rising stock.  I think its truly the best way to make money.  You buy a start position, the stock begins to move up, you add to that position, it moves up again, you add again.   The market is telling you that you are right and so you listen to the market, and to use a phrase of Dennis Gartman’s “do more  of what is working”.

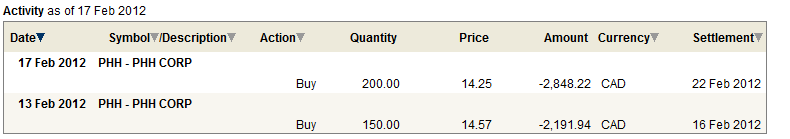
In the last week I basically doubled my position in PHH:

I wrote my basic thesis on PHH 3 weeks ago.  I love that the company is involved in mortgage origination and servicing.  I think that mortgage servicing rights represent one of the best investments you can own right now (I’ll put out a post a little later where I’ll discuss the upside of the mortgage servicing business along with another new investment I just made; in Newcastle Investment).  I also love that the company trades at about half of tangible book and at around 4x a core earnings number that truly does represent the core earnings metric that should be used to evaluate the company.

What I had kind of ignored up until this this week was the company’s Fleet business.  It seemed like it was making money, it wasn’t really a core part of my reason for owning the company, so I just disregarded it as something that wouldn’t necessarily hurt the investment thesis but was not really something I wanted to focus on.

What is Fleet Management?

The best definition I could find as to what the business of fleet management is all about came from wikipedia:

Fleet management is the management of a company’s vehicle fleet. Fleet management includes commercial motor vehicles such as cars, vans and trucks. Fleet (vehicle) management can include a range of functions, such as vehicle financing, vehicle maintenance, vehicle telematics (tracking and diagnostics), driver management, speed management, fuel management and health and safety management. Fleet Management is a function which allows companies which rely on transportation in their business to remove or minimize the risks associated with vehicle investment, improving efficiency, productivity and reducing their overall transportation and staff costs, providing 100% compliance with government legislation (duty of care) and many more. These functions can be dealt with by either an in-house fleet-management department or an outsourced fleet-management provider.

So what’s so great about that?

This week I ran a quick set of earnings numbers on the PHH Fleet business:

If you average earnings over the last 6 years you get average earnings of $0.83 per share of PHH.

Think about that for a second.  Here you have a business that has shown the ability to earn money consistently, even through what was probably the worst recession of our generation.  What would you value such a business at?  10x earnings?  12x earnings? 15x earnings?

If you start running the numbers at those kind of multiples on the average and peak earnings numbers, you realize pretty quickly that the Fleet business could be worth something pretty close to the current stock price.  Or in other words, when you are buying PHH you are buying the mortgage business for very little.

Moreover, as one would expect, the fleet management business is going to improve along with the economy.  As per last year’s 10-K:

The fleet management industry continues to be impacted by the relative strength of the U.S. economy. As the U.S. economy improves, we expect to see continued improvement in the industry. We believe that improvement in the economic conditions will be reflected in continued growth in our service unit counts.

If I am right about my previous speculation that the US economy is improving, the Fleet business could turn out to be a cash generating machine for PHH.

One last point.  When you see the value that appears to be unrealized in Fleet you have to wonder whether there could be a spin-off of Fleet from the rest of the company at some point.  There was a question on the Q4 conference call that alluded to this possibility.  Management did not deny it, saying only that it wasn`t an appropriate topic for a public forum.  Meanwhile, what better way for a cash strapped company to raise cash then to spinoff a somewhat unrelated business that isn’t being realized at fair value anyways.  For those of you not familiar with spin-offs I would recommend Joel Greenblatts excellent and terribly titled book,  How to be a “Stock Market Genius”.  While there is no guarantee that a spinoff of Fleet will occur, the cards are all aligned.

Letter 32: Sacrificing to the gods, the story of gold demand, Atna’s Pinson disappoints (slightly)

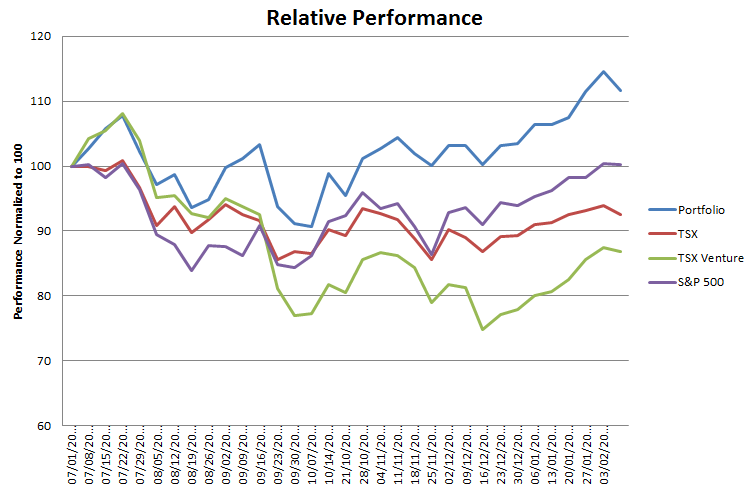
Portfolio Performance

 Portfolio Composition

Shaking it up

Things weren’t exactly peachy for me this week.  Rarely have I felt more confused about what sectors I should invest in then I do right now.

One of the best gauges of just how divided I am is the number of stocks I have in my portfolio.  This got up to 20 stocks on Thursday this week.

20 stocks is silly.  I’m not running a mutual fund.

Anyways, on Friday I sacrificed a number of these positions to the trading gods.

A sacrifice to the trading gods?

A sacrifice to the trading gods can be anything from selling a few shares of a single company to wiping out a number of positions in a sort of sacrificial blitzkrieg.

When things aren’t going my way and I am feeling confused and disordered, quite possibly the cause of such troubles is that I have upset one of the trading gods.  In such a case, it is necessary to appease these gods by “sacrificing” one or more positions as atonement.

On Friday, in the midst of another crummy looking day, I did just that.

In my actual account I also liquidated Second Wave Petroleum.  I came within a hairs breadth of selling OceanaGold, Golden Minerals and Canaco as well, but I decided to stick with them (for now) because it just feels to me like gold is on the verge of a move up.  There may be a second leg to this sacrifice yet.

So what is this superstition all about?

Well on the one hand the sacrifice is about gods and reconciliation and bowing to the higher power.  You don’t mess with the supernatural.

On the other hand, there is a method to this seeming madness.

Let me tell it like this.  I was listening to Radiolab this week.  Help!   That was the title of the program.  The episode had a story about a young man who had “lost his life to a coin toss”.

What, you say?   Well that was what the reporter that overheard the remark said, and so he set out to track down the poor, life-less man that uttered those words and to find it how it was that a life could be lost by such chance.

As it turned out the young man managed a massage parlor.  It had been his fathers business and he had taken it over.  A number of months (maybe years) before his father had come to him and his brother and told them that one of them had to take over the business.  The father didn’t care which boy took it over, but it had to be one of them, and the boys had to figure out which one would be it for themselves.

Neither of the two brothers was very excited about the prospect.  After sitting on it for a few days, hanging over their heads, finally the one son couldn’t take it any more.  He proposed to his brother that they make a bet on who had the most tea leaves float to the top of their next cup of tea.  The one with the most tea leaves would walk away clean.   The loser would take the business.

Well the bet was made and the tea leave floated.  The brother who lost the bet was despondent at first, but he begrudgingly took his place.  He had to be dragged to the massage parlor for work by his father, and he had to be forced to work on his own father’s feet until he became proficient enough to work on the clients.  At first he hated it, but over time his attitude changed.  Soon he began to like the interaction with people, the sense of performing a service, he felt good about having happy clients with happy feet.  He began to relish his job, coming in weekends and working late nights.  He no longer regretted his decision.

Now here’s the interesting part.   When he was asked about the bet by the report, he replied that it was luck of the draw.  But his brother said something enitrely different.  His brother said he would have never have let that bet decide for him whether he would take over the business or not.  The bet wasn’t going to make the decision for him.

But not so for his brother.  He believed that the bet was never about him anyways, it was always about his brother.  His brother, he says, deep down wanted to manage the massage parlour.  He couldn’t admit to himself, and definitely couldn’t bring himself to admit it to his father.  The tea leaves helped him along, gave him the reason to do what he should do but did not want to come to grips with.

The reporter went back and confronted the brother now running the massage parlor with this theory. He didn’t deny it.  On the one hand he wouldn’t say that he set up the whole gig with the tea leaves just to have an excuse.  Of course not; he couldn’t say that.  But he also wouldn’t deny that the tea leaves had led him to act as he really wanted to act.  “I probably couldn’t have done it without the tea leaves, he says, but once the tea leaves had spoken then I had no other choice.”  The tea leaves made him do what he knew needed to be done.

And that’s why you make sacrifices to the trading gods.

Weekly Trades

The story of gold supply and demand

A couple of weeks ago I said that I needed to get a better handle on the supply and demand dynamics that were driving gold.  I thought it would help me from my constant waffling of late; into and out of the gold stocks with every move up or down in the price.

Well it remains to be seen how much it helps with my waffle (I was pretty darn close to dumping OGC, AUM and CAN on Friday morning), but I did the work and here are the results.  I used data from the World Gold Council for all the estimates.

Its all about Asia

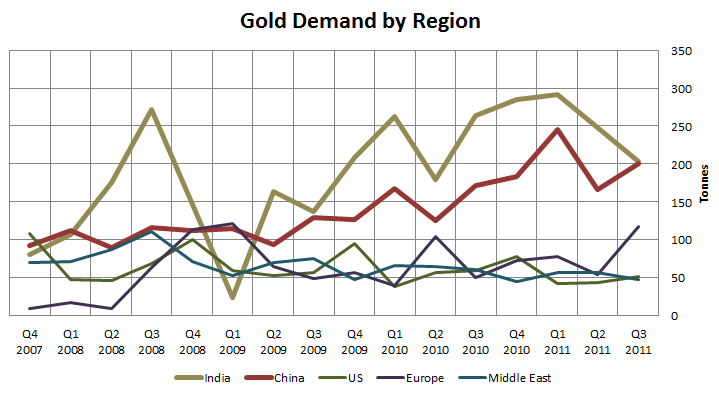
So the first thing that I was a little surprised by was by just how much India and China mean to the market.  I mean for all practical purposes, India and China are the market.  Take a look:

Maybe this helps explain why when gold keeps getting hammered down intraday here in North America, those moves to the downside can’t gain any traction.  When you think about it, the big, sustainable moves down of late have all come overnight.  The main reason I didn’t include a number of my gold stocks in my sacrificial orgy on Friday was because it seems to me that someone is doing their best to bring gold down, and isn’t having much luck with it.  The outsized influence of China and India on the demand side show why.

The other point to make, just in passing, about the above chart is that Chinese demand is a lot more stable than Indian demand.  If I had to pick out who was at the margin here, I’d have to say it was the Indians.

The jewellery buffer

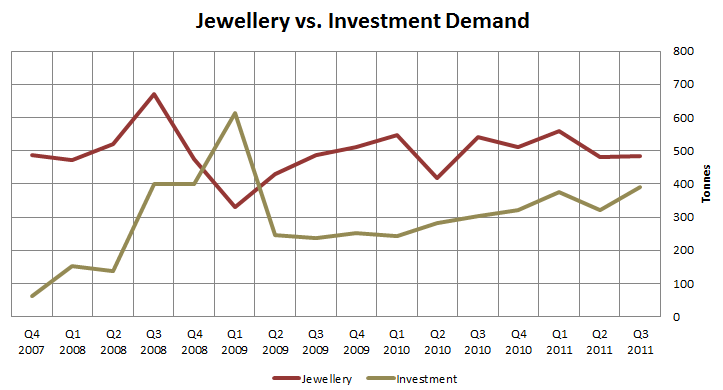
This second chart isn’t really telling a surprising story. Its just confirming the one we know, and that is that investment demand is driving demand increases.

A couple of more nuisanced comments about the chart.  First, the chart is in tonnes.  So what you say?  Well if jewellery demand is flat in tonnes it is “to the upper right” in dollars.

Look, when you go out and decide to buy a piece of jewellery you don’t say to yourself “well I think I will by a 0.1 oz gold ring.”  You say, “I think I will buy a $300 gold ring”.  The point is that the key metric for understanding jewellery demand is probably not mass.  Its dollars spent.  And if demand in tonnes is flat, then demand in dollars spent is going up pretty substantially.

If you put this together with the previous fact that much of the demand is coming from developing Asia, you are left with the conclusion that there is a rather firm underpinning of jewellery demand brought on by the rising wealth of the Chinese and Indians.  If the gold price ever stalls out for a year, or heaven forbid goes down, I would expect to see a substantial uptick in jewellery demand as those increasing “dollars spent” buy more gold.

I think you can look at jewellery demand as a big old damper.  If prices go up too fast than the dollars spent number isn’t increasing in concert and so you see a reduction in demand from jewellery.  If, on the other hand the price goes down the opposite happens, and jewellery demand puts a floor under price as the same dollars spent buys more tonnage.

Mine supply versus recycled supply

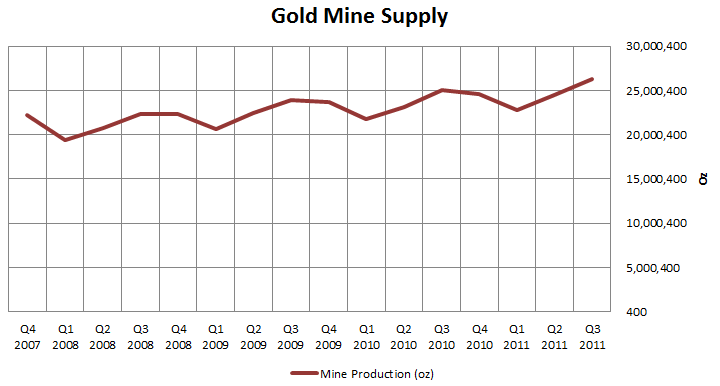
Last chart.  Mine supply.  First thing about mine supply is that all the data is in tonnes and no one I know thinks about the amount of gold a mine produces in tonnes, so this chart is in ounces.

Does anyone else think its kind of wild that there are only 25 million ounces of gold produced every year.  You could basically fit a whole years production of gold into one of those big 500 tonne mining trucks.

Second, supply is growing.  It is growing, but mine supply alone does not match demand.  Mine production was 746 tonnes in the third quarter.  Recycled production was 427 tonnes.  So recycling of gold makes up almost 50% of the total supply.

Again this is all about what is the drive at the margin.  Clearly its the recycled gold that is going to come when gold prices go up and go away when gold prices go back down.  Just as with jewellery demand, this is another great dampening factor.  Somewhat more intriguingly, one has to wonder if a point will be reached where the recycling has run its course, or at least all the easy recycling has been done.  No signs of a drop so far, but one could point out that even with vastly higher gold prices, recycling has been pretty flat for the last couple years.