CLIQ news out today looks solid. Sales accelerated a bit in Q320 over Q2. I think it is only going to improve with the trajectory of cases we are seeing in Western Canada and the restrictions just put in place in Edmonton.
Oct Update
selling 8 stores for $21mm – $2.625mm
these stores contributed $1.9mm of profit in 2019
lower volume stores – though they were profitable ones
SSS for liquor accelerated to 15% yoy – was 13.4% yoy in Q220
Cannabis SSS increased 33% which is decent as well
said available capital resources is $70mm so that is down from August but that probably means increased inventory which could be a good thing
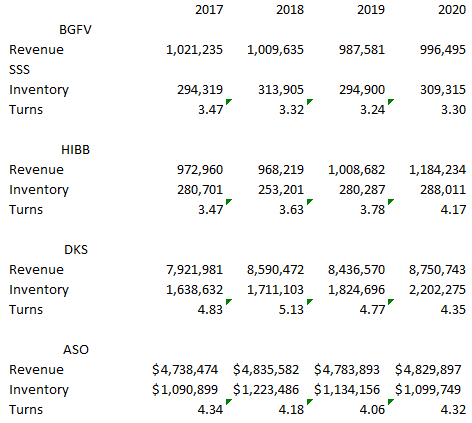
ASO IPO’d on Friday. It was below their target of $15-$17. I bought it under $13. Sports retailers are still doing quite well. BGFV has finally moved. ASO is not as cheap as BGFV but it is more comparable to DKS and HIBB – it is a better business. You can make legit arguments that BGFV does not turn over inventory as fast, that it has no online presence, and that SSS have been much worse than the competition. With ASO they compare favorably to DKS and HIBB, and the FCF they generated in H1 was really good. I imagine they generate almost all of the $760mm of FCF in Q220. Another quarter that is even close to as good would be a signifcant percentage of the market cap and close to enough to pay down the rest of the debt. A couple of charts to demonstrate the comps. I’ll post up some notes on it later.
DLHC is a stock I bought in April and sold later in June or July and now I bought it again on Monday.
They have some debt that they took when they made a big acquisition last year, and they aren’t in a great business or anything – this is basically staffing and project deployment. And they have some customer retention issues – as you’ll read there is a small business set aside that could bump them with the VA, but from what I read they would still end up as a sub-contractor anyway so its not as big of a deal as it sounds.
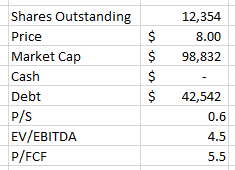
Its a cheap stock, and really that’s the thesis. It trades at 5.5x FCF. The larger staffing companies trade at 8x to 10x EBITDA. It is not going to the moon but I think it should be worth more than this.
market cap of $98mm at $8
trades at 4.5x EV/EBITDA, 7.1x P/E, 5.5x FCF
revenue is expected to grow if analyst estimates can be believed – 34% growth yoy in 2020
they provide professional healthcare and social services
geared at: large-scale federal health and human service initiatives
over 1,000 employees
100% of revenue is from Federal gov’t
agencies they service include: VA, HHS and DoD from their legacy business
also NIH and CMS from the SSS business they acquired last year
revenue last year can be divided between 3 markets within the Federal govt:
Defense and Veteran Health Services – 45% of revenue
Human Services and Solutions – 20%
Public Health and Life Sciences – 35%
before they acquired SSS the VA was 65% of revenue
it isn’t just contract labor, they do provide labor but also are responsible for delivering some processes,services on behalf of the gov’t
these services are to gov’t – to Veteran Affairs, Health and Human Services, DoD
there is definitely contract risk though – before renewing they had 9 contracts with the VA that were coming due in Oct 2019 – so a loss of these would have been devastasting
there were some contracts that they were precluded on bidding on at renewal because they were supposed to go to small business
but the RFP for the renewal is off the table, at least for now, this is what they said on Q3 10Q:
As previously reported, a single renewal request for proposal (“RFP”) had been issued for the nine (9) pharmacy contracts that required the prime contractor be a service-disabled veteran owned small business (“SDVOSB”), which would have precluded us from bidding on the RFP as a prime contractor. We had joined a SDVOSB team as a subcontractor to respond to this RFP. However, the government has canceled the previously issued RFP for these contracts. The government has neither indicated nor announced its future procurement strategy. Due to the time required to conduct a procurement process, we expect these contracts to be further extended
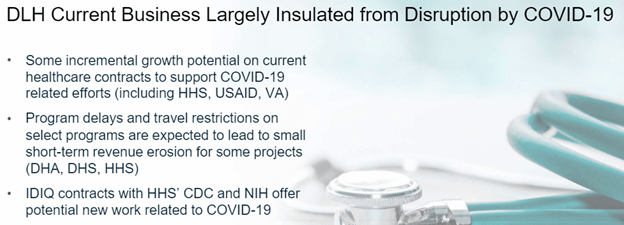
They aren’t impacted much by COVID. In March 25th presentation they said:
– since then have actually won business due to COVID in Q220
– they do have net debt of $42mm – this is down from $55mm at beginning of year – and from over $63mm at time of acquisition
– they took on debt in the large SSS acquisition last year
Q120 Results
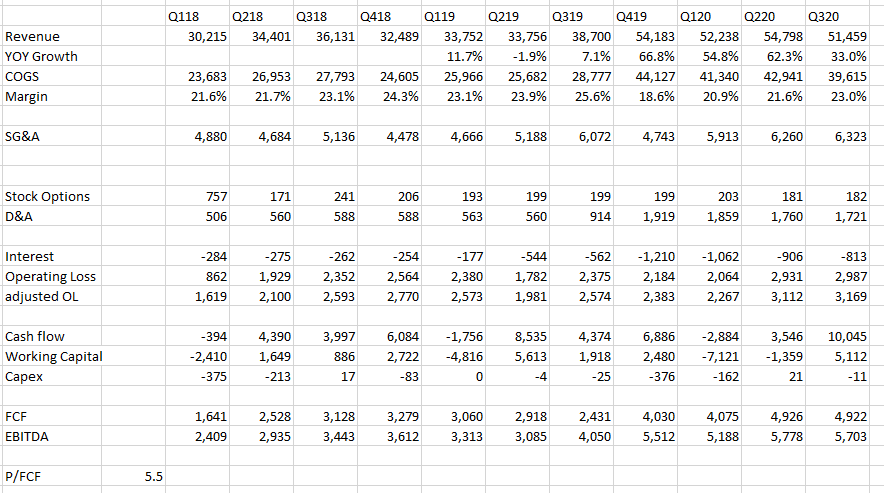
they had $5mm EBITDA in Q12020
reduced debt by $4.8mm in January
said past 6m are good benchmark for going forward – had $106mm of revenue, $6.5mm OI, and $10mm EBITDA in last 6m
not surprisingly operating margins are tight – 6% in Q12020
Q12020 results were EPS of 13c, cash flow from ops before WC of $4.2mm, capex is minimal
if I go back to F2019 – EPS was 44c, $13mm of cash flow before WC, $0.4mm capex – so trading at 4x FCF
debt was only $7.2mm in FY2018 – so it was all debt for acquisition
Q220 Results
Q2 was a little weaker
revenue was down a little because of COVID – the revenue they get includes “accommodation” so travel of employees, expenses
saw some organic yoy growth but they didn’t qualify how much
they didn’t get this in Q220 b/c of COVID
but almost all the rest of revenue is directly related to their contract workers:
numbers of workdays and slight things like that, that represents about 93% to 95% of our revenue quarter-in, quarter-out. The remaining 5% to 7% is comprised of what we would call accommodation revenue, so things that you would not independently seek to bid on
still had EPS of 16c per share, $5.5mm of EBITDA
also generated $10mm of cash
debt down to $44.5mm – expect reduction to $40mm by YE
received contracts to assist the National Institutes of Health in their fight against infectious diseases – in this case, COVID-19. With recent awards expected to generate approximately $15 million in calendar 2020
this is related to COVID trial – so I think they are administering the trials, so the amt and timing depends on the progress of those trials
could be additional revenue from other yet to be announced COVID programs – its changing all the time
Social & Scientific Systems Acquisition
provide healthcare staffing
to: Department of Health & Human Services – including the National Institutes of Health (NIH) and the Centers for Medicare and Medicaid Services (CMS) – along with other healthcare-related institutions
400 employees
paid $70mm for acquisition of Social & Scientific Systems, Inc – $63mm net of cash that they would receive from tax rebate
expected that they would contribute $65mm of revenue annually
had a backlog of $346mm at time of acquisition
Acquisition of Irving Burton Associates
acquired for $32mm
provides government healthcare research and IT services to clients including the US Army Medical Research and Development Command, the Telemedicine and Advanced Technology Research Center (TATRC), and the Defense Health Agency.
increases DLH’s overall portfolio of services
likely improves the company’s contract bid prospects relative to competitors in the government healthcare services space.
company’s current revenue run-rate is ~$25M annually with a $143M outstanding backlog.
Rada has been a frustrating stock. The pullback in the stock is unwarranted from what I can see. Rada gets no respect. Even though Rada grew revenue 75% yoy in Q220, year to date order are up over 100%, revenue guidance increased to $70mm, announced another $10mm of orders recently, the stock has gone from $7.75 to under $6 over the last few months.
What can you do? Only buy more, which is what I have been doing.
This weekend I saw the article referenced below. The IM-SHORAD production deal looks like it is done. Rada has been delivering prototypes for testing over the past couple years – now production orders should be coming soon. Estimates are for at least $60mm of revenue from this next year (from Canaccord). Maybe the stock will get some respect.
Notes I’ve accumulated on IM-SHORAD below, including the article.
program is sold to through DRS relationship:
Leonardo DRS. DRS is a major player in the defense electronics market in North America, with a focus on tactical systems and radars. In 2017, we signed a cooperation agreement with DRS to market and sell our tactical radars in the North American market for counter-UAV, short-range air defense, and other solutions. DRS has acquired a few MHR radars and is actively promoting our radars as part of their system solutions. In 2018, DRS was selected by the US Army as the mission equipment package provider for the Army’s IM-SHORAD program, which includes our MHR radars as onboard search sensors
DRS is a prime on the product along with GD and Raytheon (from this article)
Rada delivers the radars, i believe 4 radars per set, 1 set per UAV
from July 2018: RADA Electronic Industries announced that its Multi-Mission Hemispheric Radar (MHR) will be integrated into the Leonardo DRS mission equipment package (MEP) solution for the U.S. Army?s Initial Maneuver-Short Range Air Defense (IM-SHORAD) capability
nine prototype systems will be the basis for a future production decision of more than 140 systems, beginning in 2020.
is a $60mm annual opportunity in 2021 and 2022 – Canaccord initiation report
From Q219 cc:
IM-SHORAD is the army program, the Marine Corp is named GBAD. The army program is not a typical program of record. It evolved as an urgent need to a very rapid program. And probably all of us, some of us have seen that in the U.S. — AUSA conference being depicted as from slide to prototype within less than a year. So I think everybody involved, including the U.S. Army, are very proud of this momentum. The program itself is a sizable program for us. It’s close to 150 vehicles. And if it goes as planned, then it is now — it was already published by the program executive officer that if it started testing, we do see revenue start towards end of 2020 or mainly, again, 2021. And again, the testing and validation typically takes quite a few months until everybody is settled.
from Q419 call:
IM-SHORAD is not yet in a deployable situation. However, let me describe a bit our understanding of the case here. Maybe you have followed and noted that the U.S. Military is actually closing down some forward operating bases and moving troops to centralized locations because they cannot protect and they don’t have enough means to sense and warn against the fires that they have been suffering from recently. So my understanding is that the US Army at least is using what they have already in the inventories. And this is typically the heavy equipment, the C-RAM heavy equipment.
from Q120 call:
We have delivered 7 sets, which is 28 radars, maybe 30 with some spares. We are delivering soon another set of 4. But these are prototype sets, and as we mentioned in the discussion, we expect to get the several production orders later this year.
in presentation estimate it at 600+ radars when all is said and done – maybe more, not sure but Rada references 3x to 5x potential at one point, not sure if that is referring to potential vs. the 600 known radars
The US Army announced last week that it has given the green light for initial production of an Interim Maneuver Short-Range Air Defense (IM-SHORAD) system
article titled: “Huge contract for Israel’s RADA: US Army procuring dozens of IM-SHORAD vehicles”