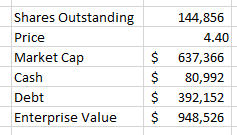Skip to content

Posts from the ‘Uncategorized’ Category

Research: PagerDuty into Earnings

So just like HOME, PD is going to report after a big move.  I reviewed the stock again to decide whether to sell some or all before earnings. With HOME I ended up selling 2/3 (should have sold it all).  I wasn’t planning to but the stock went crazy yesterday which forced my hand.  Same thing looked like it was going to happen with PD but it reversed so fast today I’m not sure whether I will sell or not any more.

General

PagerDuty

  • collect machine generated data from any software enabled device, combine with human response data and analyze it
  • their tech sits on top of company’s technology system
  • takes in data from underlying applications and applies automation and machine learning to orchestrate actions of experts to fix problems it has identified
  • so PD can look at incidents, compare to past incidents, address severity on past, route to proper DevOps person
  • in an abstract description:

you need solutions to understand how that technology is operating, automatically use software signals to detect whether something is having a problem or not. And then getting those software signals turned into actionable work and routing that work to the right people in the right moment to solve a big problem at the right time is super important.

  • ingests all of the incoming alerts from monitoring tools, analyzes and whittles them down to ones that require responses
  • it’s a way of detecting issues quickly through data analysis:

ROI

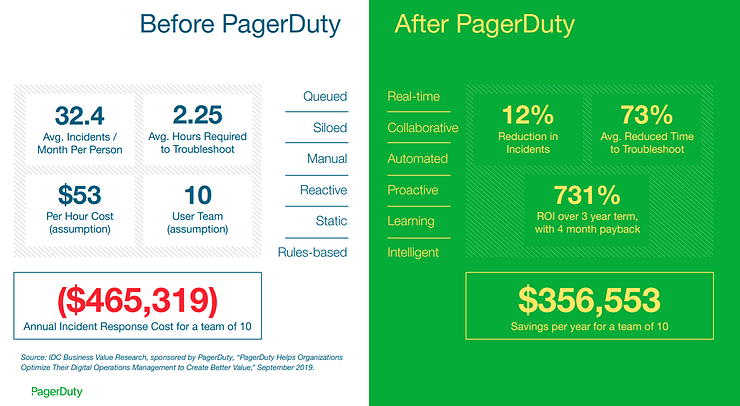
  • they claim IDC has identified 731% ROI for customers over 3 yearrs – by reducing number of incidents, time to resolution
  • the ROI is tied to down time or disruption time – makes it quantifiable
  • example of a large retail bank in the U.K. that’s got millions of customers and thousands of employees. And when they implemented PagerDuty, they saw an 85% reduction in the number of nonactionable alerts that were coming their way
Developer Focus

  • product has been focused on software developers – on DevOps – so resources that are focused on issue investigation
  • have many large developer focused customers – Twilio, Zoom, Box, Elastic, Datadog, Okta, Cloudflare
  • platform is cloud-native
  • can drop PagerDuty into a small team and have it up and running in 10 minutes
  • one primary products (on-call management) and 4 add-on products:
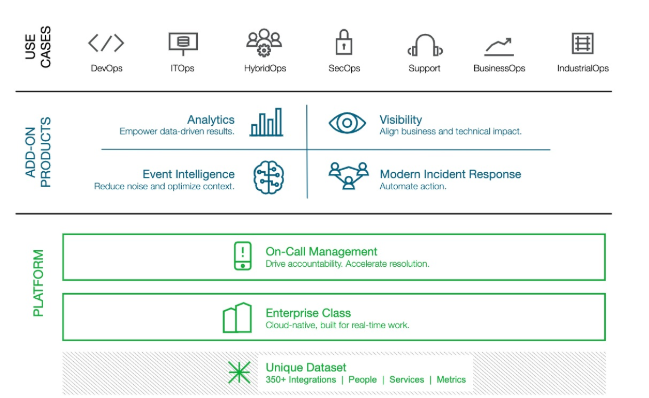
  • they are tied into data sources like: AWS, Datadog, HashiCorp, New Relic and Splunk
  • also have bidirectional integration into Atlassian, Microsoft VSTS, Salesforce, ServiceNow, Slack

TAM

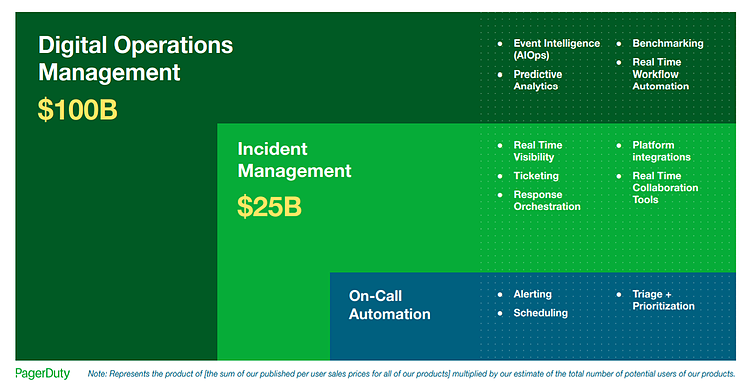
  • they estimate their addressable market is $25b
    • based on 85mm potential users x $295/y in revenue
    • this is the size of the DevOps or incident management market, which is their traditional market
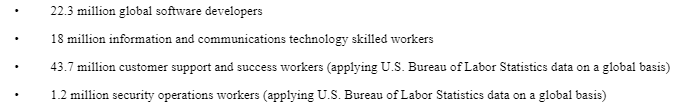
  • the 85mm users comes from this:

  • right now PD has 348 customers with $100k+ ARR
  • reason for smaller deals is likely b/c
  • 12,000 customers – 1/3 from Fortune 500
  • 16% of those customers are outside of DevOps

New Market Penetration

  • so traditional market is targeting DevOps in incident management market
  • trying to enter a broader enterprise market – where apps would be built on their platform
  • they estimate the size of this market at $75b, so much bigger:
Digital Operations Management

  • examples of enterprises using PD for Digital Operations Management:
  • Box uses PagerDuty to help ensure that its services are always available to its customers, leveraging PagerDuty Modern Incident Response to run automated response plays that enable teams to mobilize faster and take action in real time.
  • GoodEggs uses PagerDuty to enable warehouse operations and development teams to analyze signals from refrigeration units to ensure food stays fresh for deliveries.
  • Petoton – have been using it for application development and track issues but are starting to use it to track shipments with customers
  • The Gap – uses PagerDuty to directly connect product and IT teams as well as distribution centers, creating smarter, more streamlined approach to handling incidents. We estimate that this digital operations upgrade will save Gap millions of dollars per year.
  • large oil and gas organization uses us to manage the efficiency of their fuel trucking terminals.
  • We have a payments customer that uses us for their physical security team as well as legal.
  • We have a large software company that uses us to manage the real-time workflow across the legal team when they’re trying to finalize contracts across business units
  • have a significant number of customers who have adopted us primarily in — for the security use case, particularly as you see DevSecOps taking hold in organizations; and also customer service, where increasingly, the reason customers are engaging with companies, because they’re having a difficult time, tends to be rooted in an issue with technology, the mobile app, the digital app, I can’t finish this e-commerce transaction, I can’t find the pricing that I thought


Competition

  • saw expansion rates decel from 140% plus in 2019 to sort of 122% – I think this was the big negative on the stock over the last number of months
  • primary competition is OpsGenie by Atlassian and VictorOps by Splunk
  • OpsGenie had 1,396 customers Q2 2019 when Atlassian acquired it
  • Atlassian did a new release of OpsGenie with integration with Jira, Bitbucket in June

From William Blair (June2020):

  • vast majority of our new customer acquisitions are uncontested
  • Let’s touch on competition. It comes up all the time, and you guys probably hear this a lot. But there’s a couple of competitors out there that, certainly, if you take — they’ve cut pricing, some very dramatically.
  • in response Tejada notes 95% retention, that they are integrated into 275 of most popular and important apps, not worth ripping out for 10-15% opex savings
  • also on enterprise: And then the last thing that I would just mention is we’ve made a significant effort that has really paid off in moving to enterprise, right, in that — we really don’t see any competition in enterprise per se
  • she also mentioned lack of competition on enterprise in Q1cc
  • they said their churn in SMB in Q120 was macro related

Impact of Covid

  • been a mixed bag
  • grew ARR in Q120 by 55% – that is an acceleration
  • strong quarter with largest customers
  • weaker with SMB
  • saw deals take longer
  • also customers seeing 2x to 11x number of incidents
  • seen an acceleration of digital transformation activities that would have taken them years being pulled forward and now being completed in months
  • an acceleration to cloud adoption and cloud migration
  • know that when PagerDuty is deployed with a cloud migration initiative or cloud adoption initiative, that initiative goes faster, a factor faster (inaudible)
  • we think that these are tailwinds that long term are going to continue to be very strong for PagerDuty.

Convertible

  • sold $250mm of 1.25% convertible
  • price on convertible is $40

RBC on PagerDuty (Aug 28th)

  • believe that estimates are reasonable
  • SMB is 20% of ARR which is going to be a headwind – saw higher churn in Q120
  • feels to me like a beat is almost expected here because the consensus revenue number ($50.7mm) is conservative
  • job posting data for PD hasn’t been great – negative QoQ in both Q2 and Q3
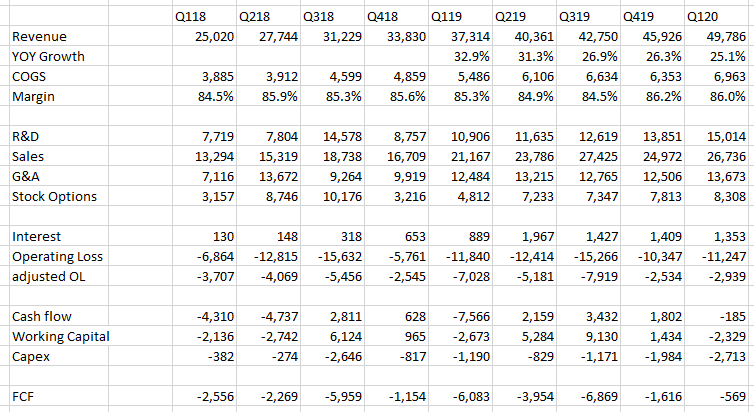
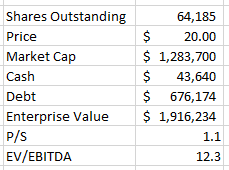
  • They aren’t quite as reasonably priced as they were when I bought – 15x P/S is a lot more than 9x
  • I’m also not sure they really benefit that much from COVID – their pricing is seat based so its not like more incidents from their customers means more revenue
  • Finally, OKTA and TEAM seem to be putting on a pricing war
  • On the other hand the damn stock crapped out today on a sector rotation – if it was $37-$38 still I think I’d sell at least 2/3
Research: Apollo Health and Beauty

  • 73.8mm shares outstanding at $2.78 for market cap of $205mm
  • there are another 20.9mm warrants outstanding but they are way out of the money at $11
  • they used to be called Acasta Enterprises – beginning July 2018 had operating sub called Apollo Health and Beauty
  • amalgamated with Apollo Apr 2020 – changed name to Apollo…
  • Apollo has been around since 1991
  • employs 500 people
  • one of largest private label personal care product manufacturers in NA
  • develop and manufacture branded and private label products for retailers
  • products sold across 10,000s of stores in NA
  • was a breakeven business in 2019
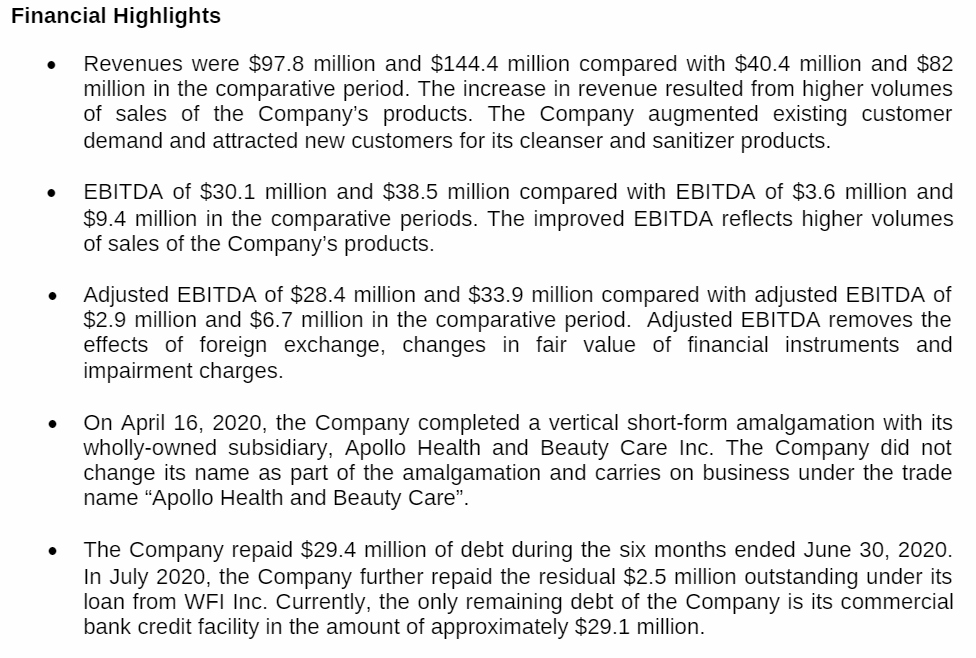
  • I guess its their sanitizers and cleaners that are selling:

  • they kind of allude to what is going on in Q220 MD&A: The Company attracted new customers and augmented existing customer demand for its cleanser and sanitizer products
  • it is actually kinda surprising how little info or promotion of these results there are in the filings or PRs

Q2 Results

  • debt at end of June was $35.7mm – they paid off about $29.4mm of debt in June
  • EBITDA in June quarter was $30mm
  • SG&A was quite a bit higher too though – up from $2.5mm to $7.9mm yoy in Q220
  • also a pretty big increase in professional fees and general office expenses
  • EPS in the Q220 was 35c
  • it’s a pretty crazy increase in results:Stan Bharti is chairman of the board (?!?) but he actually doesn’t own any shares according to circular, which seems odd
  • run by Charles and Richard Wachsberg
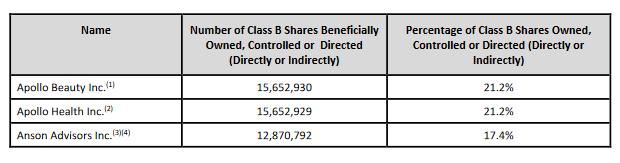
  • these Wachsbergs own a lot of shares:
  • another 2.5mm shares owned by Carlo LiVolsi, a director
  • this does not seem like a scam or promo to me, just looks like they are in the right place at right time
  • probably limited to COVID but really, should have pretty good results for a number of quarters, maybe 3-4 I’d guess, which would nearly would match the market cap
  • revenue has been pretty consistent up until this quarter
  • these are the last 10Qs of financials.  They actually appear to have been turning the corner in Q1:

  • it looks like they changed CEO and cleaned out the board a over a year and a half ago:

Acasta Enterprises Inc. (TSX:AEF) (“Acasta”) announces it has agreed with Charles Wachsberg and Richard Wachsberg, who together own approximately 36% of Acasta and are the co-founders of Apollo Health and Beauty Care (“Apollo”), to replace the Board of Directors (the “Board”).

The current Board and the Wachsbergs were not able to agree on strategy going forward and, accordingly, Geoff Beattie, Robert Schwartz and Jay Swartz have stepped down as Acasta directors and Ian Kidson has stepped down as Interim CEO and director.

Stan Bharti, Carlo LiVolsi, Jeffrey Spiegelman, Richard Wachsberg and Charles Wachsberg have joined the Board. The new Board has appointed the Wachsbergs as co-CEO’s of Acasta.

Research: Ribbon Communications

  • 110mm shares at $4 for $440mm market cap
  • $81mm of cash
  • $391mm of debt
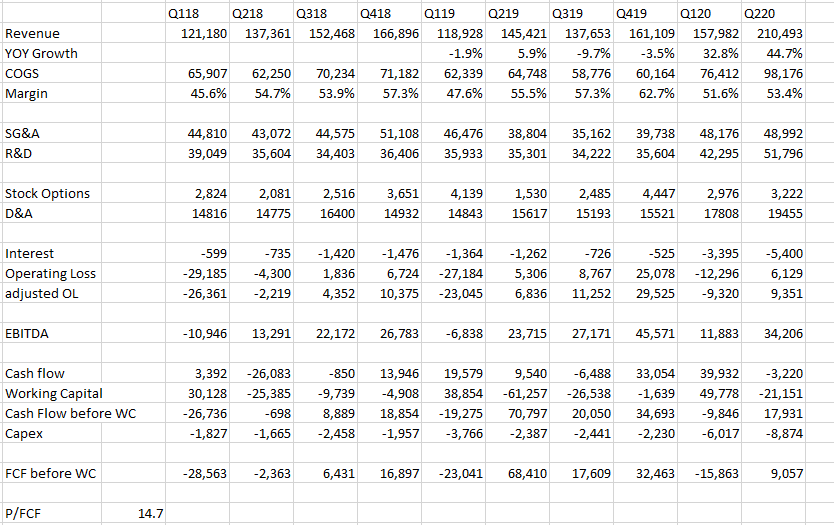
  • cash flow was okay though $37mm in H120 $22mm fcf in H120
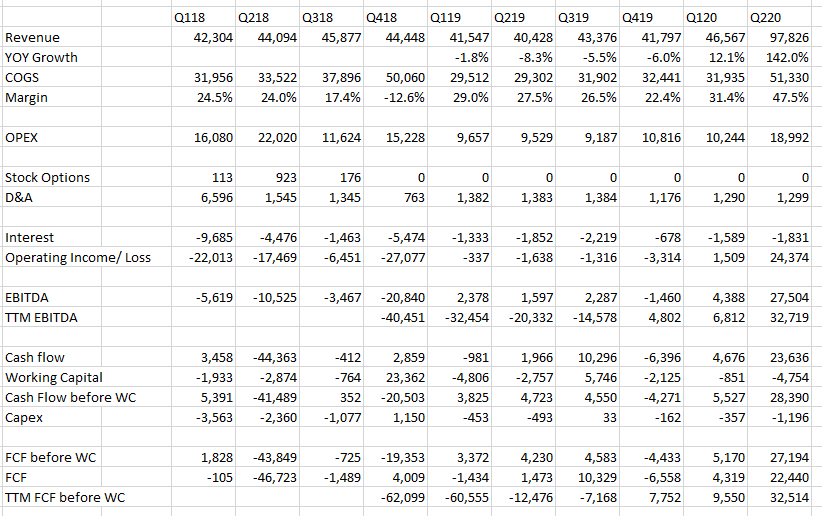
  • company seems to generate a fair bit of FCF – see table at the end
  • this is one of those companies where their business description is all jargon which is a flag of sorts
  • software solutions provide a secure way for our customers to connect and leverage multivendor, multiprotocol communications systems and applications across their networks and the cloud
  • here it is in a nutshell: their products help CSPs and to lessor extent enterprises upgrade legacy infrastructure to cloud, IP-based networks
  • 70/30 split with CSPs/enterprise
  • software is about 50% of product revenue

Their business is focused on:

  1. providing software to modernize network to IP
  2. providing IP network security
  3. providing edge solutions
  4. providing NFV solutions

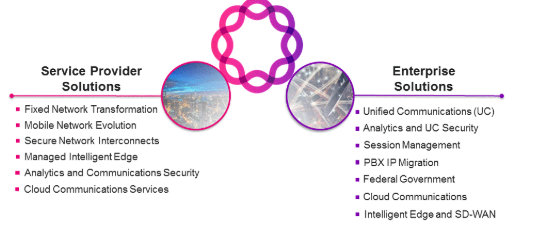
here is how they break down what they are providing in the 10-K:

  • sell mainly to service providers – both fixed and wireless, MSOs, ISPs
  • I’m not sure if I have ever made money on a company selling to CSPs 😛
  • secure cloud-based delivery of UC solutions
  • use direct and indirect sales channels
  • These guys are a merger and acquisitions machine, making it even more complicated to look at

Competition:

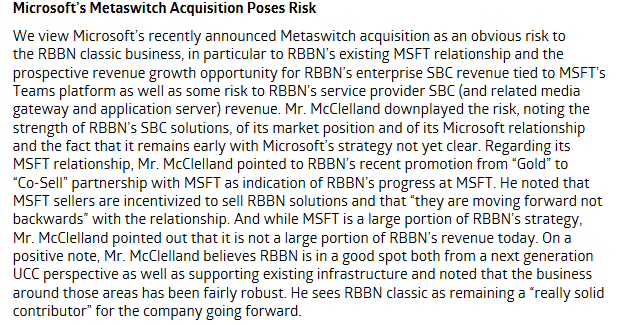
  • Network transformation: AudioCodes Ltd., Mavenir Systems, Inc., Metaswitch Networks Corporation, Oracle Corporation (Session Border Controller) and ADTRAN, Inc (also MSFT recently bought Metaswitch)
  • Security and Analytics: SecureLogix Corporation, RedShift Networks Corporation, Empirix Inc. and Oracle Corporation.
  • A concern I see in transcripts is they are competing against much bigger companies, I guess referring to Oracle and Microsoft

Acquisition of Anova Data

  • Feb 2019
  • provides advanced analytics solutions (wtf is that?)
  • acquired Feb 2019
  • has something to do with big data analytics and machine learning

Edgewater Networks

  • Network Edge Orchestration for the distributed enterprise and UC market – well at least I can understand what that one is
  • software leader in session border controlers
  • allows RBBN to get into SD-WAN market

GENBAND

  • not really clear what product these guys sell but improves RBBN position in move to IP networks and cloud-based networks

ECI Telecom Group

  • merger in Nov 2019
  • issued 32.5mm shares to ECI and $324mm of cash
  • leading packet optical solution provider
  • address markets like NFV and SDN
  • had $25mm EBITDA in 2018, $27mm EBITDA in 9m 2019
  • 50% of ECI revenue comes from India and Russia
  • There’s some sort of adjusted revenue accounting problem in India right now with major CSPs and that is impacting the India business
  • the Cowen guys don’t think a lot of ECI
  • According to RBBN merger presentation ECI does have a big TAM – not sure if its growing much though

Kandy

  • this one was a divestiture
  • received 13mm shares of ACVtechnologies for Kandy
  • Kandy was a provider of deployments of UCaaS, CPaaS, and CCaaS for mid-market and enterprise
  • so these Kandy guys are competition to RingCentral, 8×8, Vonage
  • they had a slight loss in Q220 – revenue was significantly higher yoy though

This is from Cowen about the risk of competition now from MSFT:

  • Metaswitch portfolio is similar to RBBN both have session border controllers (SBCs), media gateways, voice applicationservers, and software under the Unified Communications
  • There is also an interesting point alluded to on last CC – asking whether UCaaS is going to be against headwinds
  • It seems like a lot of elements of their business are under headwinds
  • Makes you wonder what real reason was for acquisition of ECI

Cash flow

  • working capital was about -$30mm though so that would be something to look into more

Conclusion

  • while the stock is pretty cheap, I’m not sure its worth buying
  • The Cowen guys note on a number of pieces that they are going up against larger, better capitalized competitors
  • Would probably want to see that they can succeed first, esp with ECI acquisition
  • doesn’t really seem like they are in a good place, competing against very large competition, MSFT just bought up a smaller player to add to that competition, so I don’t know… seems like a pass for now

Research: At Home Group

I bought these guys at $12 and at $20, and with them reporting Tuesday, I’m taking another look to see if I should sell.

  • EBITDA is from their fiscal 2020 EBITDA (this quarter is Q2 F2021)
  • We know Q22021 is going to be very good.

Stock still seems reasonable and I would imagine their Q32021 guide will be okay.