Skip to content

Posts from the ‘Uncategorized’ Category

Research: Alcanna

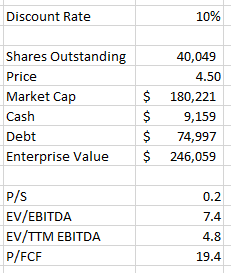
  • ~$180mm market cap
  • have a fair bit of net debt – $9.1mm of cash and, debt of $75mm
  • largest retailer of alcohol in Canada
  • top 3 in NA
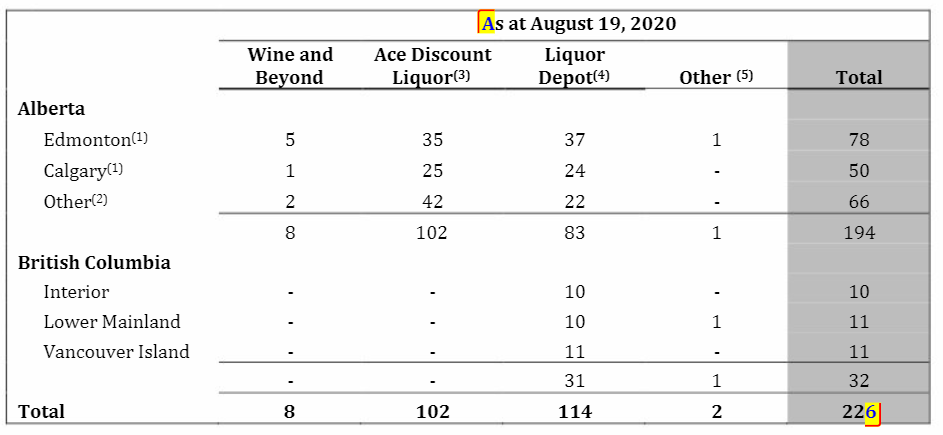
  • operates 226 stores in AB, BC

  • these are their brands:

  • brands are: Wine & Beyond, Liquor Depot, Brown Jug
  • they are mostly on the discount side
  • operate in big box stores and from what I see next to groceries a lot of the time
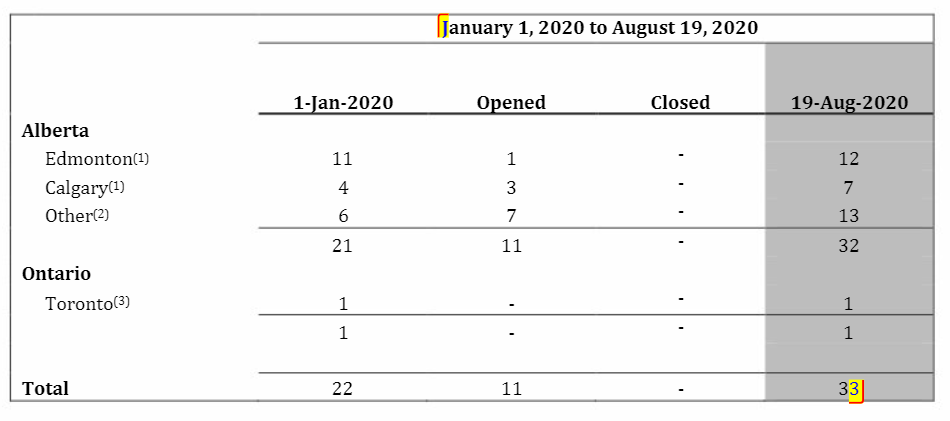
  • operate Nova Cannabis business (retail cannabis)
  • here are cannabis stores:

  • was 25% owned by Aurora Cannabis – I think they may have sold their stake though
  • on June 24, Aurora sold 9.2mm shares at $3
  • that was all of Aurora’s shares according to the MD&A

Sale of Alaska business

  • sold for $27.2mm
  • using proceeds to reduce debt

Q220 results

  • SSS were up 13.4% yoy
  • gross margins were up to 22.7% from 22.1% yoy
  • frequency of visits was down but avg basket size up substantially
  • cannabis retail sales inline with expectations
  • total cannabis sales up 64% – from $8.8mm to $14.4mm
  • GMs in cannabis were $4.9mm – that is 34%
  • plan to open 2-4 new Nova stores in AB
  • opening 6-7 stores in Ont

Q2 CC

  • our results since May and right through till sitting here today have not changed
  • Anecdotally, we’ve heard that even people who do go to restaurants are not staying. They’re eating fast, staying — in and out, stay for an hour, and — which the restaurants are encouraging to try to get some business in their limited-capacity footprints now. Not ordering the second bottle of wine. Not having the predinner drinks or the cocktails or the after dinner, and — all of which, I think, is playing into our belief — our strong belief that this is not just a onetime blip, it’s a trend and societal and consumer behavior trend that will be in place for the foreseeable future.
  • Our company has shifted, quite dramatically, its focus, and we’re essentially, for the most part, a discount liquor company now
  • our Ace banner has 102 stores, whatever it is, and Liquor Depot is 79 now. So — and Wine and Beyond, which is our large-format store, which does have luxury products but it’s not a luxury store, its margins are more or less the same as Ace
  • on cannabis margins: That’s pretty much standard for the industry, as I understand, reading some other people. And we just — we obviously go comparison shop our other retailers. Most people are — started getting around 34%, 35% margin right now.
  • more on cannabis: Our stores have been extremely stable on a sales-per-week basis because we’re in good locations. But ones who are in terrible locations, which is the vast majority of them, are just having more and more stores sharing tinier and tinier pieces of their part of the pie. And the only competitive response people in that situation can do over time, if you look at any retail 101, is drop prices
  • we don’t anticipate margins staying in the competitive environment at this level for too much longer in Alberta – sounds like AB cannabis retail market is saturated but so is wholesale so prices just overall will come down
  • But it’s 35%. 35% is just not sustainable for a long time in any retail. It’s just there’s too much — you do very well at 35% in a retail environment
  • on liquor side they can’t keep inventory: The other place that we’ve increased inventories is just we have some stores that are just doing gangbuster numbers, and we needed to put more inventory in there to support those increased sales. And then the third place, as you pointed out, is there’s been some great deals on some LTOs from the vendors, and so we’ve stocked up to keep our margins healthy and remain competitive in the marketplace.
  • step up in inventory buying in Q220 was deliberate: We made a deliberate — we sat down with our operating team, and they asked, and they had a well-thought-out plan for — wanted as much as — at the high point, as much as $10 million to $12 million extra dollars to invest in inventory because of the LTOs they saw coming and the conversations they’ve been having with vendors as to what might be possible. So it was a very deliberate thing we did. And you’ll see the benefits of that on the income statement over the next quarters because it’s purchased now, but the pricing is — it will have the impact on — positive impact on margins going forward. So yes, it was strategic. It was carefully done
  • more on store sales: some of the stores, especially the Wine and Beyonds, we just literally couldn’t keep — the shelves are running out every single weekend. Those stores are doing Christmas-like numbers week after week after week, and we just couldn’t literally keep it on the shelf.
  • in strong position for lease renewals: like 10%, give or take, whatever, of leases every year come due. So yes, no, absolutely. I think we can say with almost certainty there’s not going to be any rent increases, for sure. And it’s situational, case by case. If you’ve got some of our great Liquor Depots in — which have restrictive covenants in a grocery-anchored mall, which do very well, and we wouldn’t have the same leverage you might think we’d have with the landlord because we — if you say no, they get somebody else.
  • more on leases: other situations, we do have tremendous leverage. Obviously, one of the very few retailers right now who is not only able to pay the rents but very comfortably able to pay the rents. So we’re a very desired tenant. Always have been, but even more so now
  • if we’re patient, to get some extremely attractive real estate for very extremely attractive rents to build Wine and Beyonds, especially, in places where so far we’ve had trouble, namely Calgary and British Columbia

Insiders

  • been buying a lot of shares
  • bought around 100k shares in Aug/Sept at around current price
  • Before that, in June-July had bought about 175k shares at a little over $3

Financials

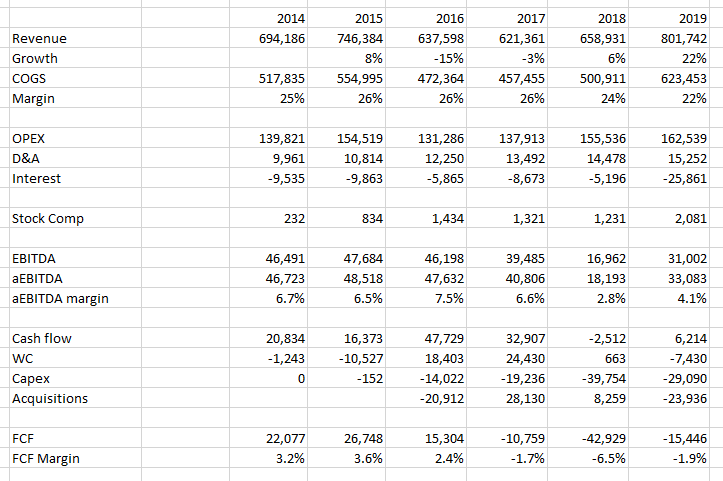
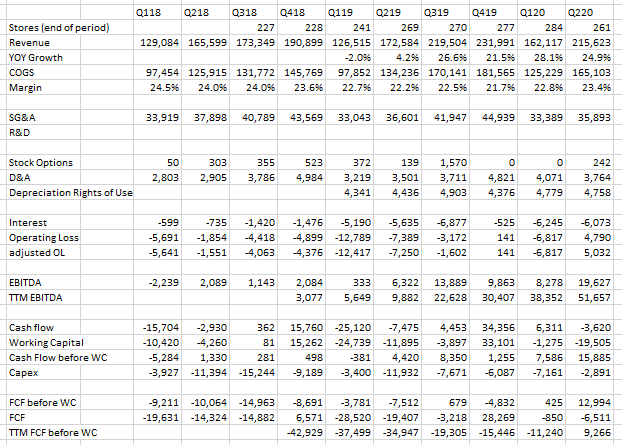
  • Long term:

  • Short term:

  • business really accelerated last quarter – no surprise
  • FCF last quarter was negative b/c they built inventory – before WC FCF was $13mm
  • I kinda like this one – seems to me that cases in BC and AB are going up not down, BC just shut down their bars and clubs, AB maybe not but who is going out right now – tailwinds for a few more quarters at least and this stock isn’t pricing in that like other pandemic stocks

Research: Mako Mining

  • market cap is $327mm @ 50c – 583.7mm shares outstanding before offering, 654mm after offering
  • have cash of ~$28mm and debt of $10mm
  • $5.1mm of debt
  • they just did an offering at:
    • 30,000,000 units of the Company (the “Units”) at an issue price per Unit of $0.40 (the “Offering Price”) for total gross proceeds of $12.0 million and a concurrent non-brokered private placement of an aggregate of 41,000,000 Units issued to Wexford Spectrum Trading Limited and Wexford Catalyst Trading Limited, funds managed by Wexford Capital LP (collectively, “Wexford”) on the same terms as the Bought
    • Deal Offering for total gross proceeds of $16.4 million
  • each unit has a share and a half warrant at 60c
  • they are 51% owned by some group called Wexford Capital:

  • Wexford is led by Charles Davidson, Joseph Jacobs – have about $2.5b in assets
  • they seem like they are just a big hedge fund
  • CEO Akiba Leisman also is consultant at Wexford – oversees their public and private gold portfolio
  • the whole team feels a bit more like a financial team than a mining team
  • it looks like they are trading at 6.7x CF based on expected production at San Albino
  • they aren’t really producing much yet
  • run by team that has built Santa Elena, El Gallo and La Trinidad

San Albino

  • high grade open-pit deposit
  • in Nicaragua
  • indicated resource of 150koz at 7.13g/t
  • inferred resource of 192koz at 6.78g/t
  • have a permit for 500tpd mill – are 65% complete
  • recently expanded permit to 1,000tpd – not sure if they are expanding actual capacity though?

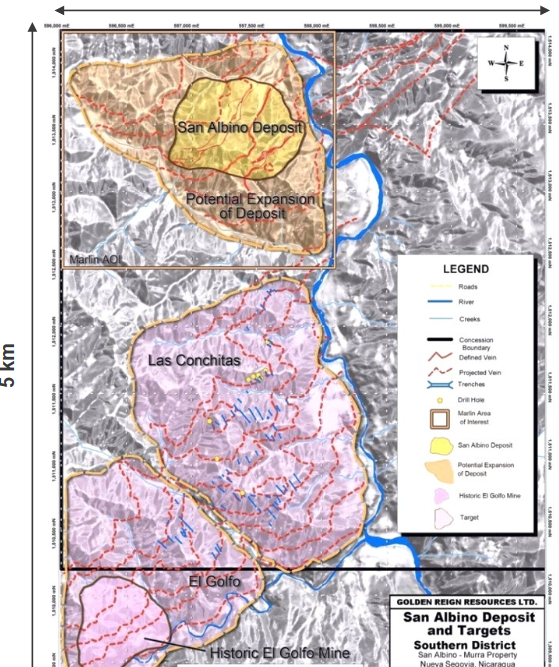
  • this is a very odd deposit for an open-pit – it’s a vein, its narrow (1-2m in a lot of places) and its as much as 50m away from surface as you go west:

  • capex on the mine is very low – $21.1mm
  • going to be low cost – AISC of $395/oz, cash costs of $359/oz
  • LOM ounces of 675koz – 41koz per year
  • about 800kt of the ore is oxide
  • recent drilling in May was 30.27g/t over 4.2m
  • most of the recent drilling is very high grade but narrow

Las Conchitas

  • had some high grade results – 84.6g/t over 1.6m, 32.7g/t over 3.1m, 56.8g/t over 1.4m
  • this is adjacent to San Albino

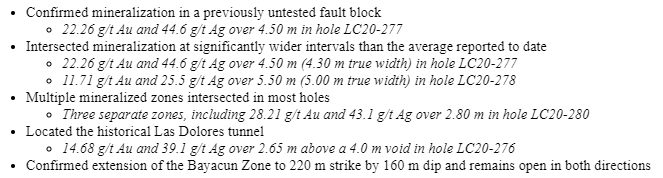
  • they have announced some decent results at Las Conchitas recently:

  • these results were from the end of August
  • they were widest intercepts at Las Conchitas so far
  • conceptual model for the mineralization encountered at Las Conchitas consists of multiple, parallel, gold-bearing quartz veins with a gentle dip to the northwest
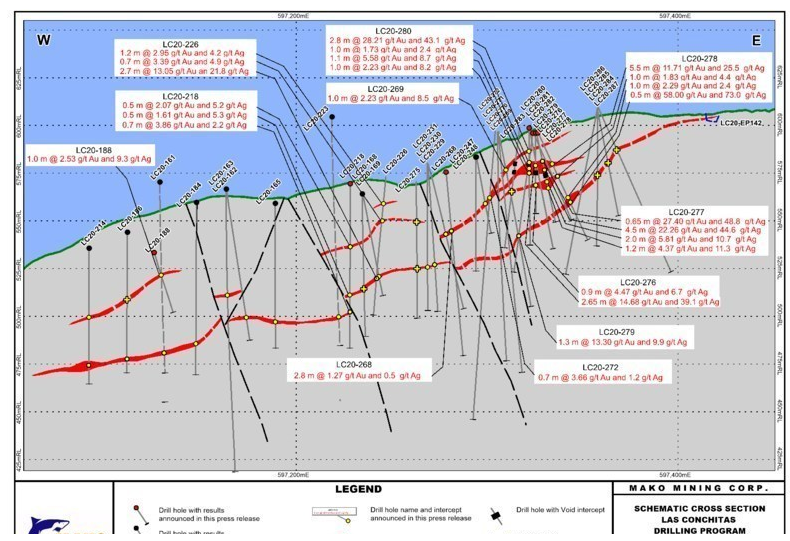
  • here is one of the cross-sections they give for Las Conchitas:

  • it looks pretty similar to Albino, narrow, high grade veins – though the grade is definitely lower than Albino

Potrerillo

  • this is a newly acquired property
  • to the NE of Albino
  • sounds like it is contiguous and along strike so they think there is a lot of potential

Permit

  • received permit for 1,000 tonnes per day operation in August 24th
  • the PEA is for a 500 tpd operation

I’m not sure about this one.  Its reasonable.  But it is such a weird deposit for an open-pit.

Research: Luby’s

  • announced this today:

has approved and adopted a plan of liquidation and dissolution (the “Plan of Liquidation” or the “Plan”) that provides for the sale of the Company’s assets and distribution of the net proceeds to the Company’s stockholders

the Company currently estimates, assuming the sale of its assets pursuant to its monetization strategy, that it could make aggregate liquidating distributions to stockholders of between approximately $92 million and $123 million (approximately $3.00 and $4.00 per share of common stock, respectively, based on 30,752,470 shares of common stock outstanding as of September 2, 2020).

  • this doesn’t sound like a new press release – they had this in the 10-Q:

On June 3, 2020, we announced that our Board of Directors approved a course of action whereby we will immediately pursue the sale of our operating divisions and assets, including our real estate assets, or the sale of the Company in its entirety, and distribute the net proceeds to our stockholders after payment of debt and other obligations. During the sale process, many of our restaurants will remain open.

  • I guess the new thing is putting numbers to it
  • have 30.7mm shares outstanding $31mm market cap at $1.05
  • another $63.7mm of debt
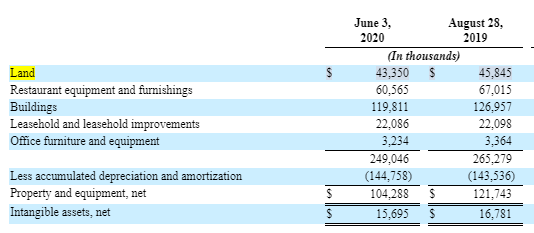
  • book value is $65mm – also intangible assets of $15.7mm
  • got a $10mm PPP loan but that is in those numbers
  • presumably the RE must be worth quite a bit?  Or maybe the brands?
  • this is the RE on the balance sheet, certainly if its closer to undepreciated value it is worth a lot:


  • this SA post seems to have it about right:

Bottom line: Luby’s owns the structures and land on over 90 of its locations. This property is on its books at cost, and many have been owned for decades. As an obvious consequence, there has been plenty of appreciation that is not reflected on the balance sheet.

  • they had appraised the properties previously: Luby’s, which on Friday had a market value of $39.4 million, said its remaining 74 properties were appraised at $211 million last year, according to its annual report filed with the Securities and Exchange Commission.
  • if the RE is really worth $200mm it seems like a pretty straightforward play

What they do

  • they own hamburger restaurants – Fuddruckers, Lubys Cafeteria and Cheeseburger in Paradise
  • own 31 Lubys and 8 Fuddruckers at end of Q220
  • are another 59 Fuddruckers franchises
  • In 2010, bought Fuddruckers for $61 million and three years later acquired Cheeseburger in Paradise for $11 million.
  • they also operate Lubys Culinary Service
  • their results haven’t been improving much – revenue has been declining
  • costs have come down some so they are fairly close to breakeven
  • in quarter before COVID sales were down 7% yoy, they had a slight cash flow loss
  • had 13 store closings and 7 transfers to franchisees
  • they closed 22 stores yoy in Sept quarter last year
  • total of 39 restaurants closed in year up till Nov 2019
  • the fourth quarter results were really not that good, the stock dipped that day to the $1.80s but then popped back up
  • though SSS were stabilizing – they were up a little over 1% at the cafeterias and flat at Fuddruckers – nothing to write home about but better than the past
  • before liquidation they were restructuring – transitioning accounting, payroll, reporting and backoffice to leading multi-unit residential outsourcing firm, blah, blah, blah
  • they have a special committee doing the strategic review
  • they are transitioning some company-owned Fuddruckers to franchises – have done 14 since Apr 2019  not sure what that means for RE?
  • I bought some at the open – seems like it is likely worth more than $1.80, not sure if I have enough info to say for sure its worth the $3-$4 the company is saying though

Research: Radcom Q2 Results

Radcom ACE

  • RADCOM ACE, which is a very advanced cloud-native containerized architecture product
  • an outcome of hard work of multiple years
  • already introduced this technology to some of our selective customers
  • early adopters of 5G are moving already to this cloud-native architecture

On 5G evolution

  • are now in really the very early adopter stage when we start to see the first operators globally
  • announcing they are moving to the next stage with their 5G networks and starting to invest in their 5G core
  • while we see operator announced their 5G and the 5G investment and some even nationwide,
  • most of them are still in a very early stage in their 5G investment, primarily focused on the radio side
  • most operators start with investments only on the radio side
  • still use their 4G network core in order to support this new radio connection
  • this is stage we are at, once they move to the next stage of 5G after the initial launch and want to go more strategically with that, they need to upgrade their network core
  • we commented all along that the time line for the 5G assurance solution is likely to be late in 2020 and primarily in 2021
  • expect to see contracts in the service assurance space, second part of 2020 and primarily in 2021, while the market is expecting to get to peak in 2022, 2023
  • early adopters will select their solutions in the next 6 to 12 months
  • vast majority of the carrier will select a solution of service assurance in order to assure that they get visibility

COVID slowdown:

  • despite the COVID-19, the transformation to 5G continues. Overall, it is going as planned. So we don’t see any significant effect
  • actually see some acceleration in some operators in terms of the 5G implementation
  • are very busy these days already to continue and build and increase the pipeline for 2021
  • this year is mainly about building the engagements, releasing the product that we are very excited to release and securing our contracts towards 2021

Competition

  • from Henderson, Needham: is the competition able to deliver a cloud-based architecture? Or are they still well behind you guys?“believe that our deep knowledge on virtualization, being engaged with the top carriers doing virtualization in the last 4, 5 years, giving us a clear advantage in this space. We were waiting for the virtualization technology to start, pick up pace. And we are very excited that in 5G, everything is going to be virtualized. So we believe our deep experience, including a very large scalable implementation in virtualization, which is going to come to play once we are starting to implement 5G. So yes, it’s definitely an advantage for us”

Overall commentary seems a little more bullish to me this quarter than in the past.  Nothing imminent yet but still seems like one to watch closely for an inflection.