Skip to content

Posts from the ‘Uncategorized’ Category

Research: Artemis Gold

Artemis Gold

  • at $4.65 has a $569mm market cap – 122.5mm shares
  • cash balance of $58mm as of Aug 24/20
  • these guys were spun out of Atlantic Gold
  • they just bought the Blackwater project from NewGold – closed today
  • payment is:
    •  $140mm
    • 7.407mm shares at $2.70
    • cash payment of $50mm after one year
    • secured gold streaming participation for New Gold – 8% of production at 35% of the gold price until 279,908 ounces, then reduces to 4% – so that’s like after 3.5Moz produced
  • they completed an offering of 64.8mm shares at $2.70
  • they announced the PP back in June, also announced Blackwater acquisition in June
  • this was the result of the 2014 feasibility study on Blackwater:

at US $1,300 per ounce gold, US $22 per ounce silver and a 0.95 US$/C$ foreign exchange rate, or CAD$1,368/oz equivalent (compared to current consensus of over CAD $1,900/oz. equivalent and current spot of approximately CAD $2,300/oz. equivalent), Blackwater had a pre-tax 5% NPV of $1,044 million, an IRR of 11.3% and a payback period of 6.2 years

  • IRR of 11.3% isn’t much to write home about at $1,300 gold
  • 8.2 Moz reserves, so-so grade of 0.95g/t
  • there is another royalty to First Nations, not sure how much
  • expected to have 17y mine life
  • construction of 2 years – cost of $129mm
  • located 160km SW of Prince George
  • I haven’t read all the background but it doesn’t look like this project was smooth sailing the last few years, probably b/c of economics
  • New Gold recorded a $218mm impairment in 2019
  • in the New Gold 2020 guidance they were hardly spending anything on exploration at Blackwater – $2mm of exploration
  • before buying Blackwater they had some copper-porphyry project and a 39% interest in a company called Velocity Minerals
  • this doesn’t seem that cheap to me – $569mm market cap is $70/oz which is fine I guess, but NG only had an EV of ~$1.5b for everything at the time they sold it, and New Gold sold it for $190mm but this stock is nearly triple that
Research – Supremex

Supremex

  • market cap of $31mm at $1.12
  • they have $100mm of net debt
  • in Q220 had earnings of 7c, EBITDA of $6.9mm, revenue of $47.7mm
  • revenue was flat yoy, envelope revenue was down 3.5%
  • net cash flow from ops was $10.7mm, up from $5mm yoy
  • they get $22mm of revenue from Canadian envelope segment, $10.6mm from US envelope segment
  • EBITDA was $14.6mm from H1 – so that is $30mm of EBITDA on a $130mm EV
  • leading manufacturer of envelopes and paper packaging
  • operate 13 facilities across 6 provinces in Canada, 3 facilities in US
  • manufactures stock and custom envelopes
  • corrugated boxes, folding carton packaging, e-comm fulfillment solutions
  • also these products: Conformer Products®1, polyethylene bags for courier applications, bubble mailers, Enviro-logiX®2and Tyvek®3and other related products such as RFID protective envelopes, X-ray envelopes, medical and file folders, repositionable notes, membership cards as well as labelling products
  • Q220 results
  • they have been developing new e-comm relationships
  • extracting synergies from Royal Envelope acquisition
  • they bought Royal Envelope for $27mm – had $30mm of revenue
  •                 margins roughly the same as SXP – from Q120 call
  • if I assume Royal had 15% EBITDA margins like SXP they would have bought it at 6x EBITDA – not exactly a steal if this is the case
  • they are planning to use Royal capacity to expand US business
  • said they can increase production 10-15% now without any more bodies
  • their envelope segment revenue is declining
  •                 down 4.7% yoy in Canada
  •                 down 1% yoy in US
  • revenue from packaging and specialty products has been up – 8.9% yoy
  • 54% of revenue came from packaging in Q220
  • I’m guessing that the stock tanked because of comments like this, though it seems like they’ve righted the ship and the stock is still down:

We announced with Q1 results that in April, we were experiencing a revenue decline of approximately 20% on the legacy business and 6%, including Royal Envelope. Fortunately, between the combination of continued onboarding of e-commerce wins and a general improvement in market conditions starting in mid-May and into June, we were able to finish the quarter at essentially flat for the corresponding quarter in 2019.

  • it lines up with the chart – stock was doing pretty well until May 14 when it tanked on earnings and then kept going
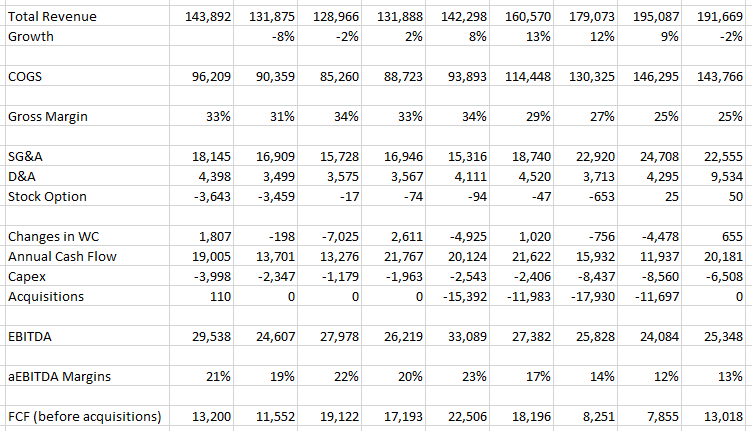
  • when you go back and look at last 10 years, it doesn’t really look like a melting icecube as a whole though the envelope side obviously is

  • they have been using acquisitions to grow/maintain the top line, so there’s that
  • even with the underlying envelope business shrinking, the fcf is still reasonably strong and this year’s FCF before WC is setting up to be $20mm+
  • EBITDA seems to have stabilized and it looks on track to be higher yoy even with the pnademic
  • so again, it may not be a growth business, but it isn’t a disaster and it generates a lot of cash
  • there has been a couple of insider buys around the current stock level – $1.27ish
  • I don’t really get why this stock is as cheap as it is TBH, the bad news from Q1 didn’t really come to pass but the stock never recovered from it
  • 1.5-2x 2020e FCF (I’m not including acquisition capex) seems a little low

I bought some of this one last week.  Not expecting the world but do think it can get back to $2.

Research – NatGas

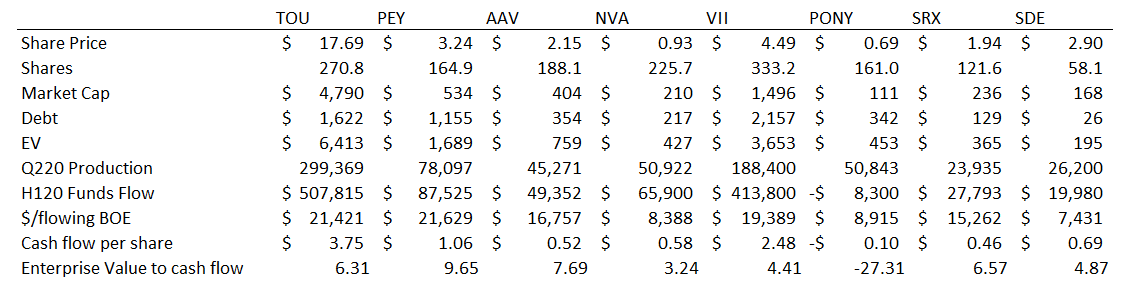
I have been in natgas stocks since shortly after the COVID bottom.  I mentioned it here.  They did well, pulled back (and I sold/chickened out briefly) and then took off again.  I’m in a basket of names.  Below is a comparison I did this week.  Rafi Tahmazian made some good points, particularly about how overlooked the Montney is, in a BNN interview a couple weeks ago.  Pretty much sums it up for me.  Meanwhile some of these stocks seem cheap even after the run-up.

Valuation:

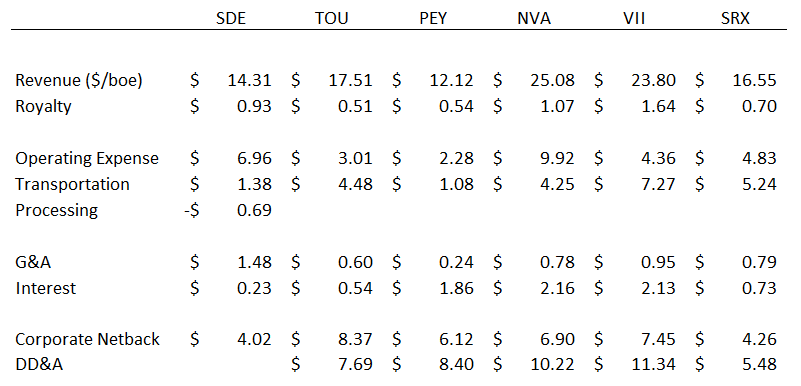
Costs (H1 results):

In addition to the usual suspects that I have already mentioned owning (PEY, AAV, PNE), I think Spartan Delta looks very reasonable, has good management, former BXE assets that I am familiar with and thus I like it a lot.  Nuvista is also interesting to me as more of a levered flyer on the Montney and the option that we get a full-fledged price recovery like what Rafi speculates.

Research – Broadwind Energy

I have decided to try out something new for the blog.  Instead of just doing my usual posts and company updates on a irregular basis, I am going to start posting what I am researching on a day to day basis.  Whatever name I have researched will be posted, likely in point form, as I am basically going to copy and paste my notes from the word document that I am already jotting them down in.  We’ll see how this goes.  Most of the stocks I will mention will not be one’s that I will buy.

Broadwind Energy

  • $58mm market cap at $3.44
  • $32.5mm of debt – they put total debt at $22mm in 10Q, not sure why
  • precision manufacturer – low margins
  • manufactures structures, equipment, components for clean tech
  • 72% of revenue comes from wind energy – provides steel towers and adapters to wind turbine manufacturers
  • have production in Manitowic Wisconsin and Abilene Texas – have combined capacity of 550 towers or 1,650 sections – 1,100 MW of power
  • gearing segment is gears and gear boxes for a bunch of different industries
  • also have industrial segment hat supplies combined cycle natgas turbine market
  • in 2019 they grew revenue 42% yoy
  • H1 revenue growth came from heavy fabrication
  • revenue was up pretty decent yoy – from $41mm to $55mm in Q220
  • it is low margin business with ~10% gross margins
  • 3c EPS in Q220, 9c EPS in H120
  • they had positive cash flow before WC – around $5mm in H120 – with capex of $900k that is FCF of $4mm in H120
  • but their own estimate of FCF was -$8.6mm for Q220 because of WC changes
  • their backlog was down quite a bit $112mm vs $144mm yoy and book to bill was 0.7
  • here is what they said about backlog being down:

We booked $39,558 in new orders in the second quarter of 2020, down from $104,612 in the second quarter of 2019 driven primarily by a $64,927 decrease in Heavy Fabrication orders as certain tower customers secured production capacity in the prior year in advance of historical lead times due to surging wind tower installation expectations in 2020.

  • saw weaker orders from mining and construction due to COVID
  • their Heavy Fab order yoy were down pretty significantly, from $96mm to $31mm
  • gearing segment down due to lack of orders from O&G
  • they did say they expect H220 to be similar to H120 so fcf should be strong in H220 – but then said they thought uncertainty from COVID would impact Q420 results
  • before COVID they did see strong orders – in Q419 they said orders in 2019 were double yoy and book to bill was 1.24 – backlog at YE was $142mm, up 80% yoy
  • honestly I don’t see why this stock is up so much, free cash seems decent and over the long run wind energy capacity grows but why the stock tripled from the bottom, I’m not sure, seems a little much, maybe why the price has peeled off