Skip to content

Week 28: Outperformance of the Regional Banks, Buying Xenith Bankshares, Gramercy CDO-2005 and I admit I was wrong (and originally right) about Argonaut Gold

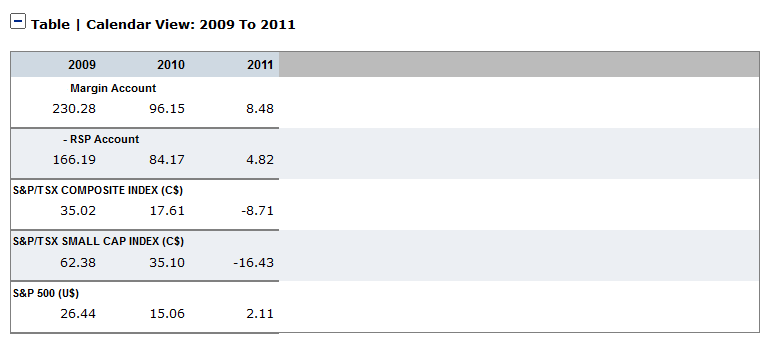
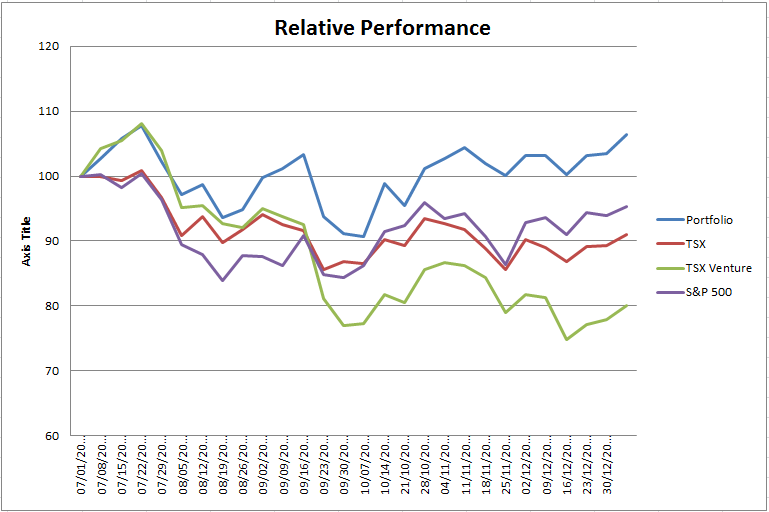
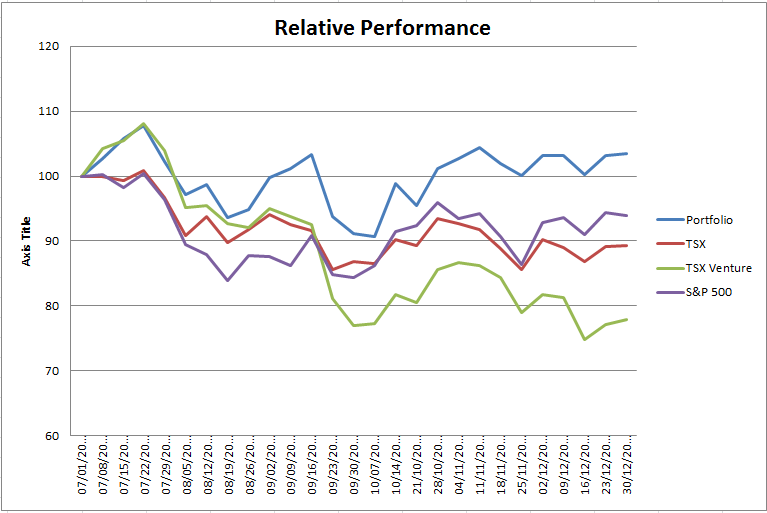
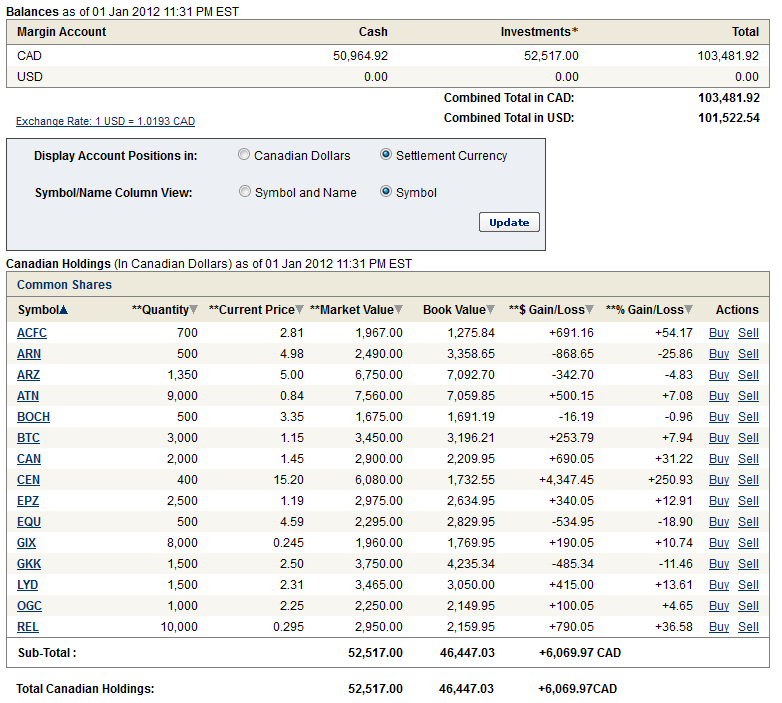
Portfolio Performance:
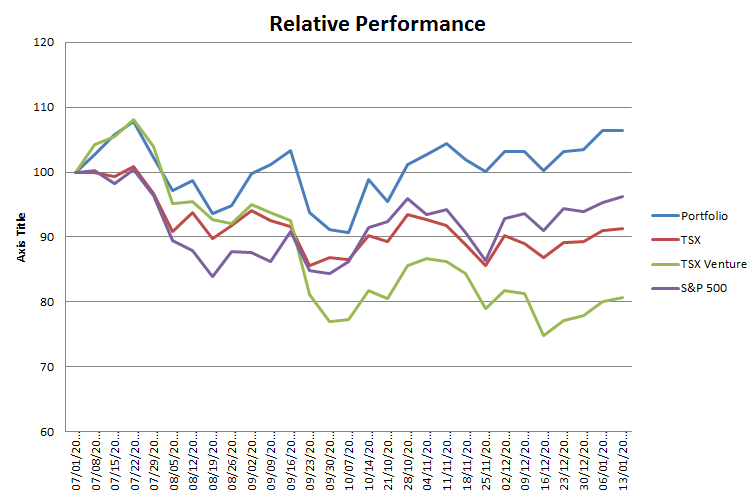
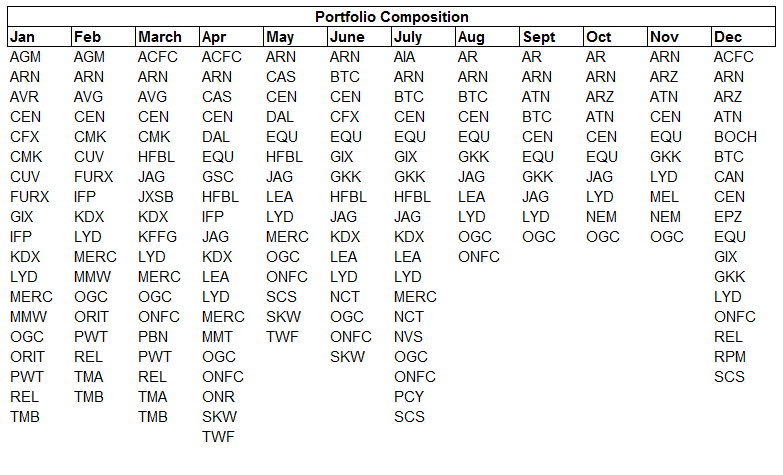
Portfolio Composition:

If the regional banks are outperforming…

Donald Coxe had a very good conference call last week.  To be honest, I think his calls have been pretty boring for the last 6 months.  He doesn’t have any better grasp on the Euro-crisis then anyone else, yet the situation in Europe is of such a systemic nature that any insight he provided on anything else, always became prempted with the caveat: Assuming all goes well in Europe.

Well last Friday he broke from this mold and made his first endeavour into the terrain of bullish sentiment in some time.

His reason?

The banks.

The main reason for his bullish outlook is the outperformance of the regional bank index, the KRE. As Coxe said:

When you get 3 months of outperformance while the S&P is itself recovering that is a powerful sign that the market has digested the bad news and that things will get better.

The KRE has indeed been outperforming.
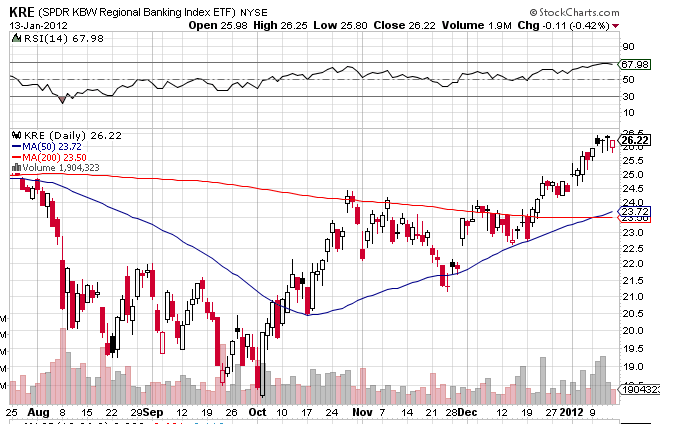
I must admit, I’m tentative to proclaim my outright bullishness just yet.  Tto be fair to Coxe, he qualified his own bullihs stance by pointing out that there was still a lot else that had to go right for the bullish call to play out.

I do admit, however, that the signs are beginning to accumulate.  Jobless claims are trending down, the ISM is looking more stable, news out of China (particularly that inflation has fallen) is starting to sound more positive, and heck, even the Italian and Spanish 10-year yields are trending down at the moment.

So what do you buy if you are bullish?

Well, on the conference call Coxe proclaimed (once again) the supremecy of the commodity stocks.  A bit of a broken record is he, but why stop with what works.  Well I am long oil, long gold, thinking about how I might get long copper or coal (but more on that below).  I have those bases covered.  Perhaps the more specific question you might ask, is what does one buy when the KRE is outperforming?

And the logical answer to that?

…buy the regional banks

I’ve been accumulating the shares of a number of regional banks over the past few months.  What is my thesis?

  • The lows of August felt like a bottom
  • There is volume in some bank stocks that typically have had no volume whatsoever (is somebody starting to care?)
  • The housing market in some regions is bottoming
  • The write-downs at many of these banks has peaked
  • How much further below book value these businesses can go?

I’ve been listening to this mortgage broker and originator podcast called Lykken on Lending on my bike ride into work for the last 3 months.  Its interesting stuff.  The first thing that’s interesting is just how intertwined real estate is with regulation.  They actually have a regular segment on this show that is dedicated to new legislation being considered by congress or the senate. Its crazy!  Second thing that is interesting; there is starting to be some signs of life in the mortgage market.  For the first time we are seeing private lenders getting back into the game.  They had a company on a couple weeks ago that was funded by Lew Raneiri (the godfather of securitization) and that is looking for loans that are just below the level of what passes for the GSE’s.

It’s starting again!

In this short clip below, Jim the Realtor, prominently featured on CalculatedRisk, makes out the bull case for a barn-burner spring.  Says Jim: “I think we get into spring time – if rates are still this low – it’s going to be a real frenzy.”

Kyle Bass and MGIC

Another favorite of mine, Kyle Bass, recently bought a large stake (just under 5%) in MGIC.  I stepped through MGIC over Christmas and will review the work I did another time,  but to make a few brief conclusions I determined the value certainly might be there but I just don’t understand the business (the mortgage insurers are hugely levered companies with massive amounts of housing liabilities against them) well enough to pull the trigger.  Specifically, the solvency of MGIC and the rest of the insurers seems to depend as much on the ability of the insurers to mark their liability per payout (in other words how much they owe for the foreclosure they insured) as anything else, and that appears to be a bit of black magic to me.

Nevertheless, MGIC has moved substantially higher since that time, something that seems unlikely if the housing market were about to (triple?) dip again.  Here is what Bass had to say about MGIC and the housing market a couple of months ago.  From the WSJ:

Mr. Bass said that while the housing market was still around two to three years from firmly “bottoming out,” he said any future price declines would be quite modest. “I don’t anticipate a huge decline,” he said.

I think he’s right.  Residential housing is closer to a bottom then a top.  And its bottomed in some markets.

The Housing Market Turns?

Residential housing is the lifeblood of most regional and community banks.  A turn in those markets could turn the fortunes of these companies.That’s why I’ve picked up shares in the following stocks over the last couple of months:

  • Oneida Financial (ONFC)
  • Bank of Commerce Holdings (BOCH)
  • Atlantic Coast Financial (ACFC)
  • Community Bankers Trust (BTC)

Apart from Oneida, these stocks are not for the faint of heart.  I know there are plenty of well capitalized but fairly valued banks out there that can return you 10-15% per year in all likelihood.  I want a bit more than that though.  So I am willing to step out on the limb a bit further to get it.

Xenith Bankshares and the problem with RBC practice accounts

I’m going to get into Xenith in a second but first let me say something about this RBC practice account.

Great idea.  The idea to be able to put fake money into an account, to have it count commissions and to be able to make buys and sells in real time is super.

The problem lies in the execution.  First there was the problem placing orders.  This started back in September.  I wrote them about it. They said they would fix it.  They wrote:

Here we are in January, I still have to do this clugey workaround where before I can place an order I have to start it through my margin account and then at the last step switch the practice account.

Now, just yesterday, another problem.  Apparently I can’t place an order for select NASDAQ stocks.  In particular those that are NASDAQ:CM (capital markets).  This just started.  I phoned RBC.  Luckily I’m on their gold plus customer plan or whatever its called so I get some service.  They look into it, see what’s wrong, but now they have to send it to their “back office people” to fix it.

We shall see.

Thus it is that while I own XBKS, I do not own XBKS in my practice account.  I don’t know when that will happen.  If any of my readers knows of another better service for tracking a mock portfolio, please email me.

Anyways, that’s the story, onto the stock.

My latest bank pick: Xenith Bankshares

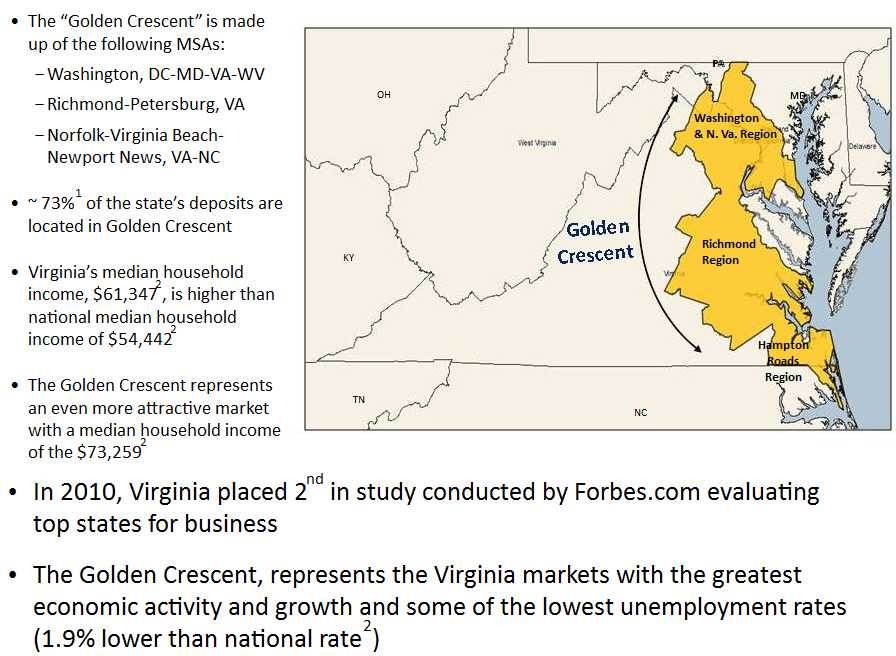
Xenith Bankshares is a community bank centered out of Richmond Virginia.
The bank specalizes in making commercial loans, which make up some 88% of their loan book.
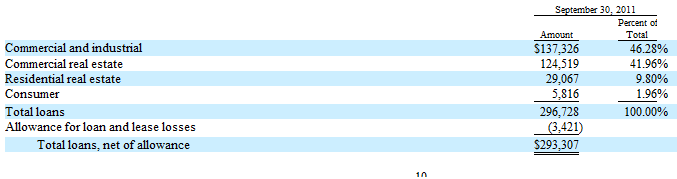
Xenith was involved in two transactions during the summer, buying banks from two other distressed Virginia lenders (Paragon Community Bank and Virginia Business Bank or VBB).  In the case of VBB, the bank was bankrupt and the transaction took place through the FDIC.  In the case of Paragon, Xenith just took over the Richmond based operations of the banks.  In both cases, the company is only responsible for the performing loans on these banks books.

The history of Xenith and these two transactions have already been written up in two excellent posts on a website called Frog’s Kiss, here and here.  I will not dwell on the details of the bank to much further, because all the information is there.

Why Xenith?

Xenith is aggressively growing their loan book in Virginia, both through transactions like the above, and organically through new loans.  They have done a good job of making loans, and so far nonperforming assets are not a significant threat.
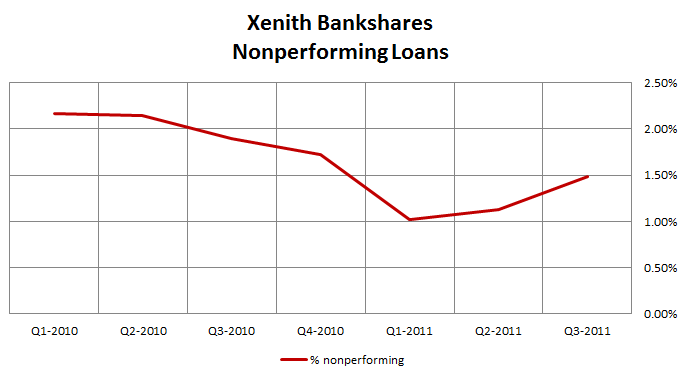
And yet you aren’t paying much for this growth.  The company has a tangible book value of a little over $65M, whereas at the current share price of $3.70, the market capitalization is a little under $40M.
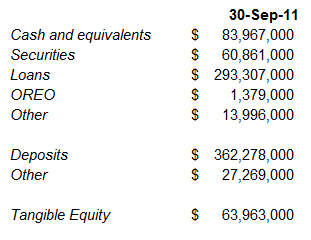
Why so cheap?

Well for one, the bank isn’t profitable yet.   Xenith has been losing about $1.5M per quarter all in for the last couple of years.  For two, it is a bank and after all no one wants to own a bank, right?

Of course that might be about to change.

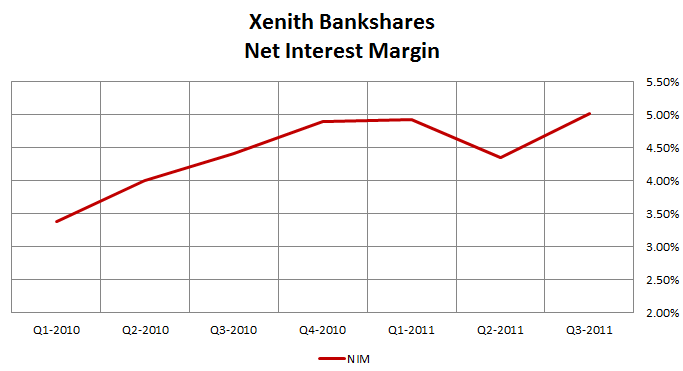
Part of the bet here is that the management at Xenith can integrate these recent transactions and bring their profitability up to the company’s standard.    The company was created originally with a takeover of First Bankshares.  This was a sleepy little commercial lender that had a fairly weak interest margin.  The management at Xenith have been successful in increasing the NIM significantly since that time (see below).  The expectation is that they will do something similar with the newly acquired loan and deposit base.
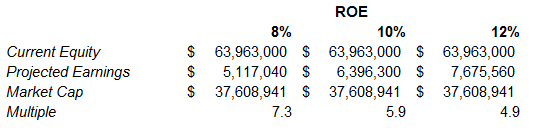
The second part of the bet is that Xenith has a lot more room to grow.  The company’s tangible equity (as noted above), is about $64M.  Loans and securities and other risk assets are about $360M.  So the company is only employing about 6x leverage.  They should be able to raise this to around 10x over the course of the next year.

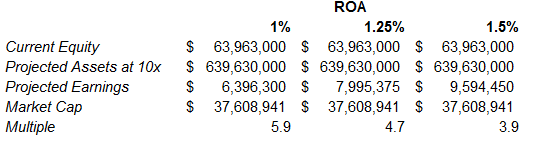
If they do, and are successful in their lending endeavors, you might expect the company to deliver a return of somewhere around 1% to 1.5% return on assets.  Taken another way, you might expect the company to deliver somewhere between 8% and 12% return on current equity when its all said and done.  Projecting either of these metrics leads to a fairly cheap earnings multiple (somewhere between 4x and 7.5x earnings depending on their success.   This suggests that as this plays out over the next couple of years, you could expect the stock price to at least double (and optimistically quadruple if the banks become loved again) from current levels as they move ahead.
Gramercy Capital: CDO-2005 passes the over-collateralization test?

With Gramercy, as much sleuthing that I am doing of the company, I feel like I do almost as much sleuthing of other investors.  With Gramercy, one of the best to follow is PlanMaestro.  He posts a blog called Variant Perceptions, also posts on yahoo, investorshub, and corner of berkshire and hathaway.  In this case the relevant piece comes from the latter.  Says Plan:

Jameson Inn was already written off 100% for OC purposes and CDO 2005 passed again its most recent test .

As those of you that read last weeks letter would know, I pointed out that CDO 2005 was unlikely to pass any time soon if it was only curing its undercollateralization with interest payments.  To have passed again, one of two things must have happened.

  1. About $100M of the assets held were paid back, with the proceeds being used to pay out the senior CDO holders
  2. One of the written down loans began to reperform

To discuss the possibility of the latter, there was news this week that the Vegas Hilton, which is in receivership and which has been 60% written down by Gramercy in CDO 2005.  For some time now Goldman Sachs, which holds the mortgage on the LVH along with Gramercy and another party, have been trying to convince the courts to let them run the hotel and gaming operations while it goes through the foreclosure process.  The problem is that the gaming license is owned by the previous owners Colony Resorts.  Colony Resorts had been fighting back saying that if their gaming license was used by the receiver, they could be liable without having any oversight control.

The issue was very recently brought to the court, which ruled that the receiver would only have non-gaming authority.  But then the Nevada Gaming Commission passed its own contrary verdict, allowing for the casino to operate under the existing license.  The matter went back to the courts and just last week news came out that the ruling was in favor of Goldman.

Given the information I have, I can only speculate that this contributed to the change in the collateral test.  The loan sat on the books of CDO 2005 at about $29M as of March.  It was apparently written down 60%, though I have no confirmation of that figure.    CDO 2005 was about $18M short as of last October.  Putting that all together, it seems very unlikely the loan could have had that big of an impact on the collateral test.  Still its an interesting exercise to go through, and a positive development both that the CDO 2005 is now passing, and that the LVH loan is likely accruing some interest again.

Argonaut Gold Pulls together a Strong PEA

This whole short Argonaut Gold trade didn’t exactly work out..  In fact, I don’t know what I was thinking.  I need to start reading my own press clippings.

To recap, two weeks ago I shorted some Argonaut against part of my long of Aurizon Gold. My reasoning was that if gold continued to fall Argonaut, being much more highly valued then Aurizon and at the same time having less cash, would have further to tumble.

I’m a little embarrassed that I made this suggestion. It was only two months ago that I had been arguing that Argonaut was one of the better gold stock investments out there.  I had it right originally. That thesis, which is available here, was that Argonaut had very strong growth opportunities and those growth opportunities could be accomplished with minimal CAPEX. If there is one thing the Street loves, its growth. If there is another thing the Street loves, its not having to put up a bunch of cash up front to get that growth.

Today the company released the PEA it had completed on the La Colorada project.

The PEA showed the following highlights:

  • Initial Capital Expenditure for the project is estimated at $14.5 million with a Sustaining Capital of $11.7 million.
  • Operating costs of $620/oz over the LOM, including $1.50/t mining costs, $2.36/t processing costs, and a 3.4:1 strip ratio
  • Gold equivalent production of 53,000oz per year over 9 years
  • Pre-tax Net Present Value (“NPV”) of $278 million using a 5% discount rate at $1500/oz gold

Overall the numbers would be mediocre if it were not for the capital costs, which at $14.5M is chump change for a project this size.  This is even less than the my estimate of $25M to which I commented: There are not many companies that can boast near term production potential with so little up front costs.

When I had shorted Argonaut against a portion of my Aurizon long it was with the idea that the quarterly results might show disappointment and the idea that the gold price might be susceptible to an even bigger pullback. El Castillo has underperformed the last couple of quarters, and with a mine that is of as low a grade as El Castillo the operators run a very fine line between success and failure.

That could still be the case, but having witnessed the stocks continuing rise I am reluctant to wait and find out. I got out Monday when the PEA came out.  At this level ($8) the stock is too expensive to buy.  I have to just admit I made a mistake by selling it in the first place (I owned both Aurizon and Argonaut back in October, but sold Argonaut after poor 3rd quarter results), and move on.

Is Aurizon a Value Trap?

How bad was that decision I made back in October to sell Argonaut and hold Aurizon?  Well, I owned both stocks until the middle of October, when I sold Argonaut after less than impressive 3rd quarter results.

[cid:image001.png@01CCD208.8AEC6020]

This is a painful chart for me to look at.

Nevertheless, pain is a necessary condition of learning, and it helps some time to agonize over your own stupidity for a while, just so that its really grilled into you not to do the same thing again.

With that in mind, what did I do wrong?

Aurizon Mines: Visions of Joanna someday

In contrast to Argonaut, Aurizon does not seem to be in much of a rush at all to bring Joanna into production.  This timeline says it all:

May 12th 2008

Aurizon first commissioned a pre-feasibility study on Joanna.

November 11, 2009

Aurizon finally received that pre-feasibility study and proceed to a full feasibility study.

September 14th 2010

Aurizon notifies shareholders that the original recovery process assumed (called the Albion process) would show lower recoveries and higher costs than first anticipated. Additional metallurgical test work would be done and the study delayed until mid 2011. http://www.aurizon.com/English/News/News-Releases/News-Releases-Details/2010/Aurizon-Reports-On-Progress-Of-Joanna-Feasibility-Study/default.aspx

August 11, 2011

Aurizon delays the feasibility study for Joanna again, saying: “the projected capital and operating costs appear to be significantly higher than previously anticipated. The increased scope of the project, as a result of the expanded mineral resource base, has increased capital costs, including those associated with an autoclave process. The costs of ore and waste stockpiles, tailings and of materials and equipment have also all been trending higher, along with the gold price.”

January 11, 2012

Another update giving an ETA: Feasibility study work on the Hosco deposit will continue in 2012 with completion of the study anticipated by mid-year. The feasibility study will incorporate a reserve update based on the increased mineral resource estimate announced on June 13, 2011, together with results of metallurgical pilot tests, a geotechnical study, updated capital and operating cost estimates, and other relevant studies.

Its been almost 4 years since the original pre-feasibility study on Joanna was complete! At this rate they should be mining by 2100.

As is obvious from above, there have been some metallurgical difficulties with Joanna. Was I too optimistic with my analysis?

To compare, the original pre-feasibility study assumed $187M in CAPEX. The operating costs were estimated at $434/oz. My analysis assumed $215M CAPEX, and operating costs of $717/oz. I think I have been safely conservative on the operating costs. I may turn out to be less so with the CAPEX.

The more fundamental point is that when I invested in Aurizon I strayed from my usual criteria for choosing mining companies in a couple key respects. Both of these have come back to haunt me:

A. Look for miners with a strong pipeline of growth. The market likes growth. It does not always appreciate value. The reason there is supposed “value stocks” is because the market does not appreciate value in itself.

B. Capital costs must be low and mining methods must be simple. The best mine to invest in is a simple heap leach deposit. High capital costs tend to get higher. Complicated mining and recovery processes tend to underperform to plan.

So what am I going to do about it?

Unfortunately there is not much I can do. Argonaut is $8 and Aurizon is $5. Most of the move in AR has been done. I’m not going to chase it at this point. Aurizon is probably much akin to OceanaGold, which I have played much more intelligently by buying the stock at $2.20 and selling it at $2.70 again and again. With Aurizon those numbers are probably around $5 and $6. Indeed I did sell some Aurizon around the $6 range the last time it was there but I think that its time to recognize that without a strong feasibility study for Joanna, that $6-$7 is about all you can expect here.

Portfolio

I’m getting too many stocks in my portfolio.  I am also seeing my cash position dwindle because I keep picking up new stocks without selling old ones.  I am still extremely cautious about Europe, and being so, I am getting uncomfortable with both of these trends in my portfolio.  In the next couple weeks I am going to reevaluate what I own and start paring where I need to.  The problem, as it always is, is that I like the prospects of all the stocks I own.  Unfortunately, as I think I showed rather clearly in my last post describing my 2011 performance, I am just as often wrong about that as I am right.  The likelihood of my own fallibility must never be underestimated.
Letter 27: My Deutsche Bank Short, Increasing my Gramercy Capital Long, and trading in OceanaGold for Golden Minerals

Why I am Short Deutsche Bank

Its been a while since I talked about my shorts.

I typically wouldn’t have much in the way of shorts.  At the most they would make up a couple percent.  I don’t have a great track record of predicting when companies are going  to fall.

I tend to pick them too early.  I think its a classic trap of a value investor;  you see an overvalued company and you conclude that it has to go down.  Unfortunately that is not the way the market works; until there is a catalyst a stock can continue to become more overvalued to the point where you as an investor have no value.

Right now, however, shorts make up a fairly significant percentage of my account.  About 15% (though not the practice account I post here because shorting is not supported by RBC).  These are extraordinary times.

I have a small short in Argonaut Gold that I mentioned last week.  I continue to have a short in Salesforce.com that has done quite well as the cloud computing phenomenon has come back down to earth.  I have a short on Tourmaline, an albeit well managed but highly valued natural gas producer in an environment of dismal natural gas prices.

The biggest short I have is in Deutsche Bank.  It makes up about 8% of my overall portfolio.   I added to it over the last week as DB made yet another failed attempt to stay above $40.  Together with a smaller short in UBS, it makes up my “at some point Europe is going to go down the toilet” bet.

Why Deutsche Bank?  Simple thesis – it is insanely levered.  Here is a snapshot of the European banks common equity to assets.  Note the location of Deutsche Bank on the x-axis.

Since that time Dexia blown up.

Jim Grant makes the same point on Deutsche Bank about half way into this interview on CNBC.

[gigya src=”http://plus.cnbc.com/rssvideosearch/action/player/id/3000038647/code/cnbcplayershare” type=”application/x-shockwave-flash” type=”application/x-shockwave-flash” allowfullscreen=”true” allowscriptaccess=”always” bgcolor=”#000000″ height=”380″ width=”400″ quality=”best” wmode=”transparent” scale=”noscale” salign=”lt” ]

Wholesale Funding

The other thing about Deutsche Bank, and to a lessor extent UBS, is that they are not strong depository institutions.  What that means is that they do not have a large base of deposits to fund their assets.  Particularly in the case of Deutsche Bank they go to the market and borrow money from other banks, from money markets, from pretty much anybody who is willing to lend it, and this is the money they use to fund their lending.  When times are good this is a great strategy.  Deposits are a more expensive (higher interest rate) form of funding then these wholesale channels (wholesale is kind of the catch-all term that defines all these short term lending sources).  But when times are bad, these channels dry up a lot faster then deposits.  They can be called quickly in the event of a loss of confidence.

A good proxy for the degree of reliance on wholesale funding is the net stable funding ratio.  FT presented the ratio, along with the following graph, in an article a few months back.

One good proxy for this reliance is the net stable funding ratio (NSFR) we have regularly discussed in all our recent sector and company reports. Currently, CASA and SG are among the Euro banks with the lowest NSFR, together with Bankia, UniCredit, Commerzbank + Intesa.

While Deutsche Bank isn’t the worst of the bunch, it is far from the best.  Combine that with high leverage and you have a recipe for instability.

All the Devils are at Deutsche Bank

I mentioned last week that I was reading “All the Devils are Here”.  Towards the end of the book there is a chapter on the demise of Countrywide.  Countrywide, like Deutsche Bank, was not a depository institution.  As a result, like Deutsche Bank, Countrywide depended on the wholesale funding markets to fund their assets (in their case mortage loans).  It was pointed out by Kenneth Bruce, the Merrill Lynch analyst that followed the company at the time, that “liquidity Is the Achilles Heel” of Countrywide.  Said Bruce:

“We cannot understate the importance of liquidity for a specialty finance company like CFC.  If enough financial pressure is placed on  CFC, or if the market loses confidence in its ability to function properly, then the model can break.”

The difference, at least so far, between what happened to Countrywide and what has happened to Deutsche Bank is that Countrywide went to the Federal Reserve and pleaded with them to use their emergency lending authority.  The Fed refused, perhaps because months earlier CFC had switched away from the Fed’s regulatory oversight to the Office of Thrift Supervision (OTS)  because they saw greater advantages (read: less strict rules).

Thus far Deutsche Bank has been saved by the unlimited lending arm of the ECB.  They certainly would be struggling to fund themselves through their traditional wholesale channels.  We know that liquidity has dried up in Europe.  We know that the wholesale funding markets (money markets, collateralized repo’s) are getting harder to access and are acceptable less and less forms of collateral (read: German bonds are the new holy grail).

Meanwhile while DB has reduced leverage to the peripheral sovereigns over the last year, they still have fairly significant gross exposure.  This gets lost in the shuffle however, because the news tends to focus strictly on the sovereign exposure.  For example, this WSJ article points out that:

Deutsche Bank has a relatively low total of €4.4 billion in exposure to the sovereign debt of the troubled euro-zone nations. Its exposure to Italy grew to €2.3 billion at the end of the third quarter from €1 billion at the end of the second quarter…Deutsche Bank has largely hedged its Italian exposure, much of which was inherited as a result of its Postbank acquisition, from €8 billion at the beginning of the year.

True… but gross exposure to the region is significantly higher.   You have to look past the sovereign.  Below are estimates of DB’s gross exposure to credit in the periphery.  DB equity is about E53B for comparison.

Having significant exposure to financials, corporates and retail in Italy, Ireland and Spain is not a good thing right now.  Given the austerity measures being imposed how bad do you think the inevitable recession is going to be in these countries?  I think its going to be pretty bad.

You might also ask a question about what othe exposure DB has.  Given that assets total around E2.2t and periphery exposure is around E100B, clearly there are other things on the balance sheet.  Well as it turns out they have a fair bit of exposure to something nebulously called “credit market debt”.

As per a WSJ called “Old Debts Dog Europe’s Banks”:

Four years after instruments like “collateralized debt obligations” and “leveraged loans” became dirty words because of the massive losses they inflicted on holders, European banks still own tens of billions of euros of such assets. They also have sizable portfolios of U.S. commercial real-estate loans and subprime mortgages that could remain under pressure until the global economy recovers.

The Journal provided the following comparison of this “credit market debt” exposure for the various European banks:

Again to the Journal, this time speaking specifically about the make-up of Deutsche’s credit market assets:

Legacy assets are also haunting Deutsche Bank AG. The Frankfurt-based bank is holding €2.9 billion in U.S. residential mortgage assets, including subprime loans. It has an additional €20.2 billion tied up in commercial mortgages and whole loans. The bank says it has hedged nearly all of its residential mortgage exposure.

Analysts at Mediobanca estimate that Deutsche’s exposure to such assets amounts to more than 150% of its tangible equity—a key measure of its ability to absorb unexpected losses.

Deutsche Bank said it plans to let most of its legacy assets mature, so it won’t face losses selling them at discounted prices.

And don’t forget the fact that the main business of Deutsche Bank is investment banking.  With the seizing up of credit in Europe, that business has to be feeling some pain.  Indeed, after reporting 3rd quarter results the CEO Josef Ackerman said:

“During the third quarter, the operating environment was more difficult than at any time since the end of 2008,”  adding that the bank’s performance was “inevitably” hit.

Management Matters

One final point. Deutsche Bank announced back in  July that their long time CEO (Ackerman) was stepping down and would be replaced by co-CEO’s.  now getting back to the book All the Devils are Here, if there was a common trait that pervaded all of the worst of Wall Street in the years leading up to the 2008 crisis, it was turmoil within upper management.  Maybe the change over at DB will go swimmingly.  But co-CEO’s sounds like a recipe for secrecy and oneupmanship to me.  As the WSJ reported:

The bank is resorting to a dual CEO structure for the fourth time in its history, despite the potential for conflict and even a power struggle between the two, because handing the reins to Mr. Jain alone was seen as too much of a culture shock, according to people familiar with the matter...The bank has been working to diversify its earnings mix away from investment banking, which has recently accounted for about 70% of its profit. In the third quarter, investment banking accounted for less than 10% of total profit.

In the end…

Look  I don’t have crystal ball that says that Deutsche Bank is inevitably going to fail.  I’m sure there are plenty of analysts out there that understand the in’s and out’s of the company’s business better than I have time to do.  What I do know is that the evidence points to the conclusion that Deutsche Bank is a bank very dependent on the ECB.  The whole bet on Europe is, in my opinion, a bet of whether the ECB eventually steps up to the plate and starts bailing out the sovereigns (and either directly or indirectly the banks) or they don’t.  If they don’t, DB, being very dependent on ECB largesse, has to do poorly.  Thus, the hedge.

The Confusing Balance Sheet of Gramercy Capital (and yet I’m still buying more)

Gramercy has been in a bit of a free fall of late.

The decline in the stock price to the $2.30 area made me want to re-evaluate my position in the stock.  Not so much with the intention of liquidating my position mind you.  I was far more interested in whether I should buy more.

I began by stepping through the Gramercy third quarter 10-Q, followed by the recent filings, in particular the 8-K filing made on December 8th that detailed the pro-forma financials ex-realty.  Unfortunately, as tends to be the case with Gramercy, the review left me with as many questions as answers.

I have to say that Gramercy has some of the most difficult financial statements that I have ever seen.  I spent two years researching Dynegy and even with all their SPE’s and off-balance sheet transactions it was still easier to understand what they were up to then it is with Gramercy.  The problem with Gramercy is a combination of

  1. it being difficult to determine what is held at corporate and what is held in the CDO’s and until recently realty
  2. there being overlap between the holdings of corporate and the CDO’s and realty and so some items are netted out even though their liability is non-recourse to corporate
  3. the fact that the CDO’s are basically a black box unless you have access to the managers report and that is not public knowledge (I am still using the only publicly available report which is from March and so therefore somewhat dated)
  4. the company really doesn’t make much of an effort to clarify any of the above.

Anyways, with all that in mind, lets try to draw some conclusions.

Net Asset Value vs. Book Value

One positive of late is that for the first time it is relatively easy to determine the book value of Gramercy corporate.  Up until now the mess of CDO and Realty divisions made it a nightmare.  With Realty gone, proforma statements were released in mid-December and stated clearly that there are $260M in assets, $40M in liabilities, and $88M in preferred.

Book is $132M or $2.60 per share.  Done deal right?

Wrong.  Everything is more complicated then it seems with Gramercy.

The first complication is that Gramercy corporate owns a number of reasonably senior securities from their CDO.  Because these securities are also liabilities (in the CDO) they are netted out and disappear on the balance sheet.

“In addition, as of September 30, 2011, the Company holds an aggregate of $54.0 million of par value Class A-1, A-2 and B securities previously issued by the Company’s CDOs that are available for re-issuance. The fair value of the repurchased CDO bonds is approximately $40.3 million as of September 30, 2011.”

However the liability in the CDO is, like all else in the CDO, non-recourse, and so the asset on corporate is legitimately accreditive to book.  So even though the value of the notes are not on the balance sheet, they should be.

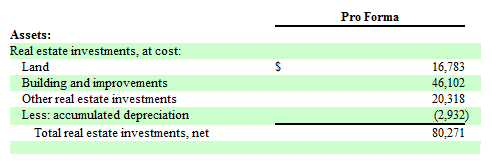
The next thing that is terribly confusing is what is included in the real estate investments.  According to the pro-forma those investments total about $80M at cost:

And maybe that’s the end of the story. The problem is that the company said in their last 10-Q (which is for the same period as these pro-forma results) that real estate assets after the transfer of the realty division was complete would total $121.3M with corresponding mortgages held in the CDOs:

“The Company anticipates that all transfers will be completed by December 31, 2011, after which, the Company expects to retain a portfolio of commercial real estate with an aggregate book value of approximately $121.3 million, encumbered by non-recourse mortgage debt held by the Company’s CDOs totaling $94.3 million, which mortgage debt is eliminated on the Company’s consolidated financial statements.”

The (unanswered) question that I have is whether the netting out of the assets and liabilities of these real estate assets includes is included in the above $80M?  My guess is that it doesn’t; that because the asset and liability are both on the balance sheet (with the liability being within the CDO) they are netted out just like the CDO notes.   But I’m not sure.  If I’m right, then the true book should reflect the extra $27M of the commercial real estate portfolio above and beyond the mortgage debt.

But what’s it worth?

The last, and perhaps most ambiguous question about the balance sheet  is what the assets are actually worth if they are sold.  As noted above, the real estate investments are recorded at cost.  I assume the $121.3M is a number also recorded at cost, though that is not clear.  But what could this real estate fetch today?  Is it substantially less then cost? It wasn’t clear in the pro-forma whether Gramercy chose cost because it was the lessor of cost/fair value, or because they just had to value them at cost.

As for the CDO’s, the notes are recorded at fair value, which means they are being valued at quoted market prices.  In reality the CDO debt is either worth all or nothing.  Either the CDOs have the cash in run-off to pay back the A-1, the A-2 and the B or they don’t, so its more likely the number is either $54M as they are fairly senior notes and so they are likely to get paid off.

To help make my point with the real estate investments take a look at one of Gramercy’s investments that you do have the information to analyze to some depth.

The joint venture 200 Franklin Square Drive, Somerset, New Jersey is carried at $558,000. Yet income from the property was $29,000 in Q3 and $90,000 for the first 3 quarters. So based on its book value it is returning 20%. I think the book value needs to be higher.


Now this is a case where the book is on the low side. There could just as easily be cases where the asset is booked on the high side. The point is, this whole valuing Gramercy is a ballpark game at best.

What is the deal with CDO-2005?

The deal is that CDO-2005 failed its over-collateralization test again in October after having passed it the previous quarter.

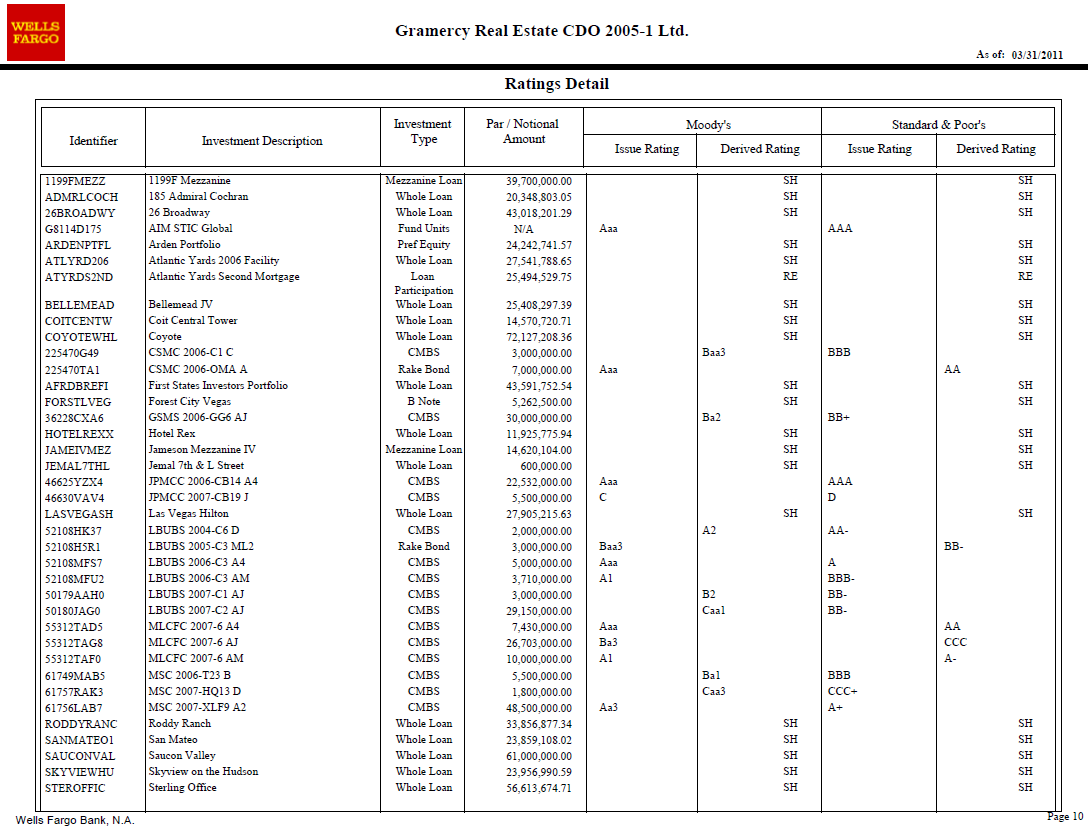
Presumably the main catalyst in the failure was the write down of whole loans to Las Vegas Hilton and Jameson Inns.  Together these loans were carried at $42.5M on the CDO books.

The question now is just how far underwater is CDO-2005 and will that CDO be able to cure itself and begin to paying out money to Gramercy again?  Well while I don’t have the most up to date data, I can still take a stab at answering that.

As of March 2011 CO-2005 had an outstanding note balance of about $741M.  Presumably in curing that balance the first time round (it was cured in July), the note balance was reduced somewhat, to lets say $700M.   Based on the current over-collateralization of 115.53%, that would mean current assets in the CDO are around $810M.  In order to pass the test with $810M of assets, the outstanding note balance has to be reduced to $686M.  In other words the company needs to see a $14M cash infusion to get the CDO passing again and begin seeing cash flow to corporate.

Where is that cash going to come from?  From the interest that is diverted to paying down principle for as long as the CDO is not in compliance.  As shown below, that interest, which was paid out in the previous quarter as the CDO was in compliance, is a little less than $5.5M per quarter.

The other possibility is that as loans within the CDO are paid off both the numerator and the denominator of the over-collateralization test drop (the assets decline as well as the notes that are paid off with the proceeds).  Eventually this would cure the CDO though it would take a lot more run-off, about $90M by my calculation.

The conclusion here is that CDO-2005 is not dead by any means, but that we should not expect to see cash flow from it for another couple of quarters.

Management Incentive

One of the concerns with any of these REIT’s is whether the interests of management are aligned with shareholders.  The concern is generally that management wants to keep getting paid and so they won’t necessarily jump at the chance to sell the company, instead preferring to live of the cashflow (and in a worse case the cash) to pay their salaries and bonuses.  I think this is the concern of Indaba, who as a large preferred shareholder is attempting to add a board member to get that cash used in share holders interests.

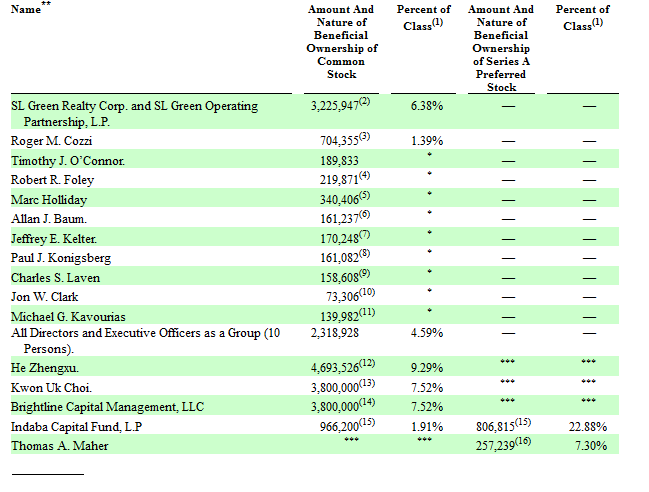
Along those lines though, it looks to me like recent efforts have aligned management fairly well. The have been provided with incentive to sell the company by the end of June 2011.  Below is a list of significant shareholders of the company published as part of a 14C on December 19th.  Executive Officers as a group own 2.3M common shares in the company, including over 700,000 shares owned by Cozzi.

What I Think

Adding it up, there is no question that there is a lot of question marks here in the numbers.  It is difficult to determine the true value of the real estate owned. It is difficult to determine when and if CDO-2005 will cure.  It is difficult to know with confidence whether there are loans in CDO-2006 that may fail, causing it to fail its over-collateralization test and thus putting the company in the position where there really is minimal cash flow coming into corporate.

The best I can do is to take the fact that the book is $2.40/share, that $150M of that book is cash, that there is another $50M off balance sheet that is invested in higher end securities in CDO-2005 and CDO -2006 that are almost certain to pay off at par eventually, and that given that the US economy appears to be stabilizing and not falling back into a severe recession, it is reasonable to presume that CDO-2006 will continue to pay out $7M of cash to corporate every quarter for the forseeable future.

Given all of this, I added to my position in Gramercy this week, and I will continue to add as long as the stock trades below the $2.40 level.  I was sad to see that we had a bump up in the price on Friday.  We will have to see if it sticks.  If not I will be ready to buy more.

Gold (and now Silver!) Stock Update

Apart from Gramercy, I made a few small changes to my portfolio this week.  I sold out of OceanaGold at $2.45.  I had planned on holding the stock until the $2.60 range again but I saw better opportunities but was reluctant to become even more leveraged into gold stocks at this point.

That better opportunity that I saw was Golden Minerals.  My broker told me to get in on a private placement of AUM back in the fall of 2010.  Nah, I don’t think so I said.  I think that placement was at $18.  The stock got as high as $24.  I bought it this week for $6.25.   Pays to wait.

Golden Minerals is another one of these junior explorers (though they do have a small silver mining operation in Mexico now) that has gotten obliterated in the last year.  The stock is down 75% off its high.  Luckily for the company, that private placement went through with some other poor bastards taking the brunt of it, and so the company is flush with cash.  With AUM you are paying $6 and getting a company with a little over $2/share in cash and an indicated and inferred resource of a little over 6Moz ounces of gold equivalent at a 50:1 silver to gold ratio.

The company’s producing mine in Mexico, Velardena, looks promising, but it remains to be seen if they can ramp up production as expected (they want to be producing 4,000oz of gold and 214,000oz of silver by Q4 2012).  More interesting to me is the project in Argentina, where they have a fairly high grade (300g/t) silver deposit that sits at 60Moz right now and looks like it has lots of room to grow.

At any rate, its another example of a beaten up junior that was worth a heck of a lot more a year ago then it is now.  It seems like a reasonable speculation that it will recover at least some of that value this year if gold and silver prices don’t crater.

Portfolio

Letter 26: A Move in ACFC, the end of tax loss selling for gold stocks, Mispricing of Aurizon Mines, and All the Devils are Here

All the Devils are Here (though most have probably moved to Europe)

Over the winter break I read the book All the Devils are Here, by Bethany Mclean and Joe Nocera. The book essentially traces out all the strands that culminated in the panic of September 2008. The book identified the following factors:

  1. A reliance on ideology instead of analysis. In particular this applies to the Federal Reserve and Alan Greenspan, whose ideological “market is always right” view permeated the decisions of the Fed and to some extent those of the other regulatory bodies. But more generally, ideology, specifically free market ideology, seemed to permeate through all the political and financial institutions to the point that it replaced a sober look at reality. Similarly, for many traders and investment bankers, an ideological reliance on “the model” often led to an ignorance of the potential risks of an outlier scenario
  2. The absence of regulation. For a variety of reasons (the power of the lobby groups, the political infighting between the regulatory bodies, the ideological free market view of the participants and the myopic focus on regulators on Fannie and Freddie) an attempt to regulate the subprime industry was hardly even contemplated until it was too late.
  3. The development of securitization. The most important consequence of the innovations to pool mortgages, to tranche pools, and then to create pools of pools (CDO’s) was that the lender and the borrower became further and further divorced by more degrees of separation. The securitization process created so many layers of intermediaries between the party who actually ended up with the loan on their books and the party that took the money that risks were easily lost in the translation.
  4. The rubber stamped AAA status provided by the ratings agencies. Some books focus on how the rating agencies didn’t understand what they were rating. Mclean and Nocera point out that the revenue structure of the agencies was doomed to be corrupted. A system where the raters are paid by the producers of the securities they rate might be considered to be an insane one. The result was that the agencies were played off against one another by the investment banks; market share went to the most relaxed rating. Add to this the fact that the agencies, particularly Moody’s, became focused on profits at the expense of their inherent conflict of interest, and you had a situation ripe for abuse.
  5. Greed. Politicians more concerned with their own campaign donations than with promoting sustainable public policy. Company executives intent strictly on their own promotion and profit. Mortgage originators with essentially no moral compass at all. The system was (and is) corrupt.
  6. A lack of understanding. The same characters at play as with greed. So few people saw the disaster coming. Sure some did, there were a few regulators and a few hedge funds that saw how unsustainable the leverage being piled on in the mortgage sector was. But the vast majority didn’t have a clue. Even the supposed smart money didn’t really get smart until 2006-2007.

It is this last point, the lack of understanding, that I think is most relevant to what we face today. It really surprised me how little the people in influential and powerful positions understood the concepts that they were making decisions with regard to. Even Hank Paulson, who is actually portrayed in quite a positive light, was completely blind to the corruption and leverage being amassed in the mortgage market.

This naturally begs the question of Europe: how many of the politicians and bureaucrats in the EU really understand the situation they are trying to navigate? Do they really know the risks inherent in the decisions that they are making? Do they even really understand the banking sector they are trying to protect?

The last 6 months for me has been an education in how the modern banking system works. I have been trying to read all that I can, all the boring, technical aspects. And I don’t think for a minute think that I’ve wrapped my head around it. There are so many moving and interdependent parts. It’s also not a very tangible subject. It simply isn’t something that is easily understood.

Thus I think it’s a legitimate question as to whether the bureaucrats of Europe have the understanding required to navigate the minefield of sovereign defaults and banking bankruptcies. As Lehman showed, it only takes one mistake to create a loss of confidence that spirals uncontrollably.

How can you take on risk with this in mind?

The end of (tax loss) selling?

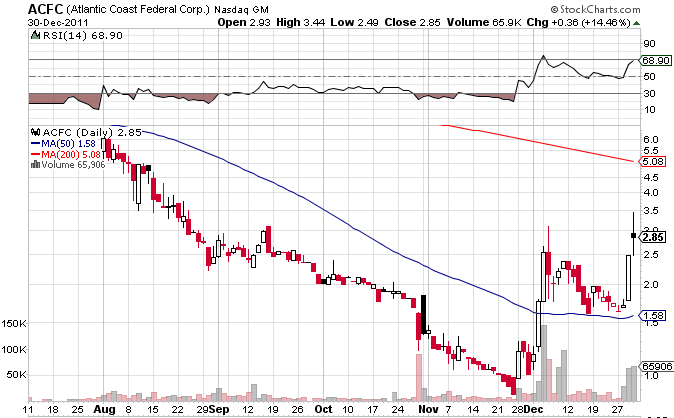
The week after tax-loss selling is always an interesting one.  It provides the first glimpse into whether a security has been facing unrelenting selling because of investors simply wishing to take their losses (and their tax breaks) and move on, or whether something more nefarious is at play.  Along the lines of the former, this week provided a rather marked jump in a number of the regional bank stocks that I have initiated a position in.  Most conspicuous of these moves was that of Atlantic Coast Financial.

A Take-over Imminent for ACFC?

ACFC had a rather astounding 50%+ move this week.  I really have no idea what precipitated the move.  To take it with a grain of salt, the volume for the stock this week was less than spectacular, though the same could be said for almost the entire move down.

As I pointed out last week the stock is a bit of a flyer; the bank is a mortgage lender in one of the most crippled mortgage markets (Florida), they have bad loans coming out their wazoo, and a stock that has fallen from $10 to $1 in less than a year generally does not do so on speculative panic alone.  Nevertheless, part of the story is the book value, which even with 3 years of bad loan write-downs lies at a rather surreal $19 per share (versus a share price of $1.70 when I bought it).

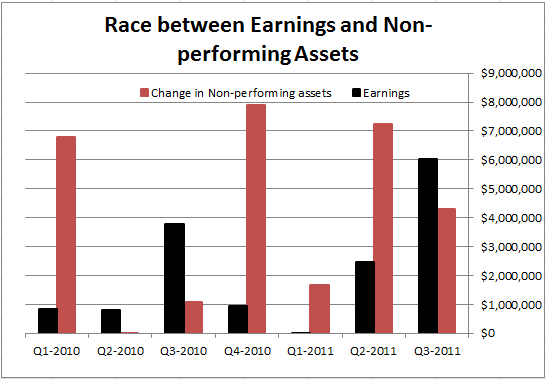
The other part of the story is simply the realization that what is going on with this bank (and many of these little community banks that got caught up in making bad loans at the wrong time) is a race between the write-downs of their past transgressions and the earnings of their current performing loan book.   With ACFC it is not at all clear to me that the bad loans will win out; in fact I tried to make the case last week that with a little luck (and an improving economy) the performing book may very soon be able to out-earn the losses on a consistent basis.  If this happens, the shares are clearly worth more than 10% of book value.  Even if it just becomes a possibility, a shrewd competitor may be tempted to take a plunge.  I constructed the chart below to try to see where ACFC is in that process.  The chart compares earnings before provisions (black) to the quarter over quarter change in non-performing loans (red).  Its basically a look at whether the company is out-earning the loans going bad each quarter.  The 3rd quarter was the first in four that the black won out.

Community Bankers Trust: Another Regional Bank with a Move of its Own

While ACFC was the best of the lot of regionals, there were others that showed signs of life.  Community Bankers Trust surged on Friday.  The stock remains at about 1/3 of book value.  If it were not for Europe and the ever-impending doom there, I would add more.  As well, Oneida Financial continues to push higher.  Unlike ACFC, BOCH and BTC, Oneida is a terribly boring bank trading at about book that is probably going to do nothing but increase in price by 10% a year and pay a 5% dividend until one day it gets bought out.  At some point I might get bored with with relatively low return, but in this environment, I am happy to take a reward with so little risk.

Will Gold Stocks Rise now that Tax-loss Selling is over?

As for the golds, Esperanza, Canaco and Geologix all are showing classic signs of a let-up in tax loss selling.  All are well above where I bought them.  Aurizon, on the other hand, continues to be sold rather indiscriminately.  Yes, I realize that the price of gold is getting clobbered on a regular basis.  I can appreciate that investors may be questioning the wisdom of holding gold as a hedge to anything given the fact that it seems to dramatically underperform on risk-off days.

Still, I scratch my head at Aurizon.  Here is a low cost gold producer that is comparatively less correlated to the price of gold than most of its competitors.   For one, if you are low cost you are by definition high margin.  Thus, a $30 move in the price of gold is of much less impact to a producer with $1000/oz margin (like Aurizon), than say a producer with a $500/oz margin.  Yet Aurizon regularly trades down MORE than your average gold producer on the down days.

Going Short Argonaut Gold and long Aurizon Mines

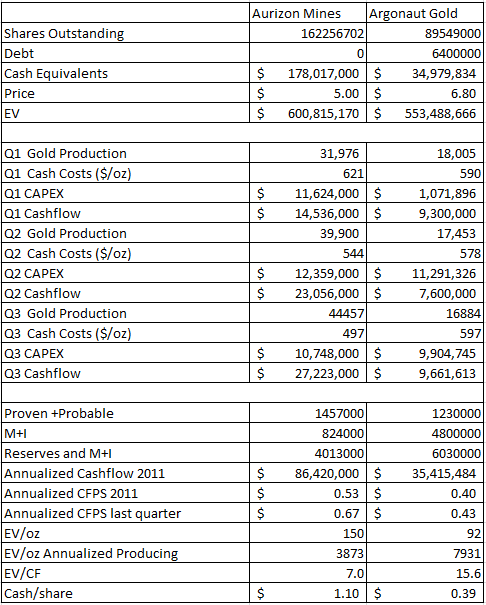
So confounded have I been that in order to hedge my risk with Aurizon I have decided to take a short position in a fellow gold producer, Argonaut Gold.  To be sure, there is nothing wrong with Argonaut Gold.  I wrote the company up rather glowingly a couple months ago.  However that was at $5, and now AR trades at $7, while in the same time Aurizon has fallen to less than $5. Below is a comparison of the key metrics of both companies.

So to briefly summarize the above, Aurizon produces more than twice as much gold, it produces over double the cash flow, and to top it off, Aurizon’s 3rd quarter was stronger than Argonaut’s.  Argonaut potentially has a better pipeline of projects, but this is more than nullified by the fact that Aurizon trades at almost half the price on a per producing ounce basis, produces those ounces at $50-$100 cheaper, and has over $1 in cash on its balance sheet while Argonaut has a mere 30 cents. It simply doesn’t make sense.

While I remain bullish the price of gold, I also remain wary that I am not very right in this bullishness at the moment, and so it seems like the prudent thing to do to short what seems relatively over valued and buy what seems relatively undervalued.  Anyways, that is what I did.

I also bought back OceanaGold for another run.  Its getting to be repetitive, but it has been a consistant source of profits.  Buy OceanaGold below $2.20 and sell it above $2.70.   I must have done this 3 times already in the last 9 months.

Portfolio