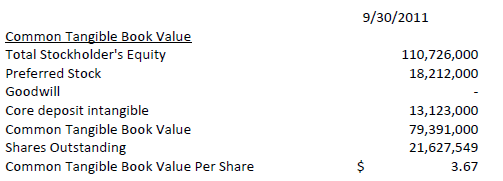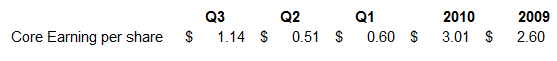Skip to content

The Canadian House Price Plateau (or cliff?)

I live in Calgary, Alberta.  The house prices here are high by most global standards.  The average sales price of a single family home in Calgary was $453,000 in December.

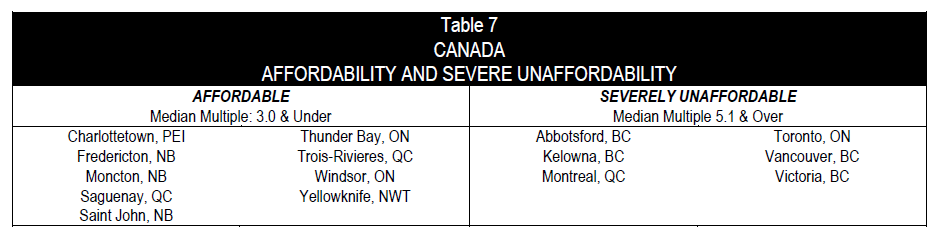
In Canada, Calgary is nothing special.  House prices in Canada are high.  I stumbled upon the following interesting research by the Demographia International Housing (DIH) that compared house prices across the globe.   Here is what they determined as being the unaffordable locales in Canada.

For those of you unfamiliar with Canada, Fredricton, Thunder Bay and Yellowknife do not represent a “hub” of Canadian population.  Vancouver, Victoria, Toronto and Montreal  do.

The above was taken from the DIH’s Affordability Survey (2012).   The methodology they use is to rank cities based on affordability is to use a ratio of the median home price in the city divided by the household disposable income.  The number gives a ratio, and a ratio of greater than 3 has traditionally been seen as creeping into the unaffordable category.

Whne I read through the report, my first question was, what exactly is household disposable income (HDI)?  From wikivest:

The amount of money that households have available for spending and saving after income taxes have been accounted for. Disposable personal income is often monitored as one of the many key economic indicators used to gauge the overall state of the economy.

In Canada, HDI is somewhere around $55-$65K depending on the source you use to calculate it:

While the DIH provided some interesting city by city numbers, I was able to dig up a Canada-wide number from a recent speech given by Mark Carney.  You have probably read sound bites from this speech before.  In particular the following shocking, over the top, end of the world type pronouncement about the Canadian housing market has been quoted widely:

Some excesses may exist in certain areas and market segments.

These central bankers are fear mongerers!

But not to worry, Carney also pointed out that overall the Canadian housing market is healthy:

Canada’s housing supply is relatively flexible, compared with other countries, and it appears to have grown at rates broadly consistent with underlying demand forces, the most important of which is the rate of household formation.

Of course, in the United States, in the time leading up to their housing collapse, Alan Greenspan and then Ben Bernanke said much the same thing.  One thing I have learned from reading all these books about the 2008 housing debacle in the US is that what a central banker says has more to do with the central bankers ideology is than the on the ground reality.

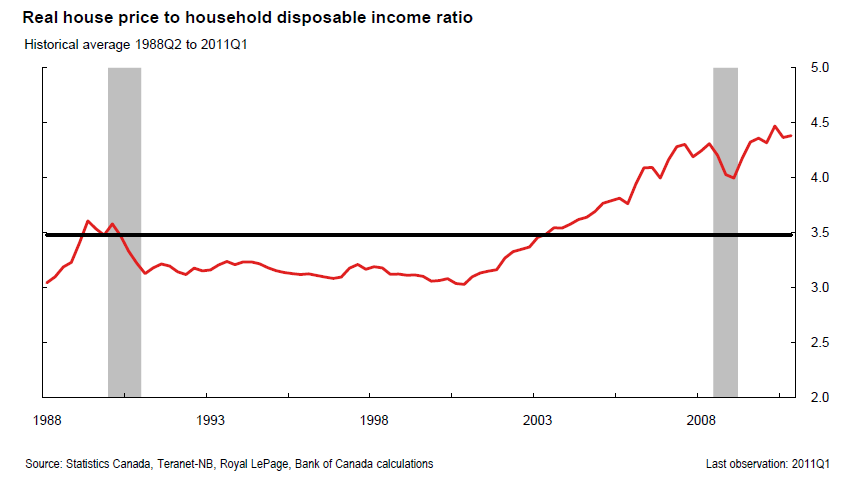
If you look at the data, you get a somewhat more worrying picture.  Below is canadian house prices to disposable income:

Overall the country is quickly approaching 4.5.  Using the DIH methodology, this would put the country as a whole in the “seriously unaffordable” category.

As for Calgary, with a ratio of 3.9, it is only “moderately unaffordable” (phew), though we are on the cusp of being “seriously unaffordable” (uh-oh). There is a really excellent analysis of how both house prices and household income have grown on the economic analyst website.  They posted the following comparison for Calgary in particular:

One more point about Calgary.   If you look at the median house price that is being used for Calgary by the DIH and others, you would be struck by the fact that it is $353,700 and not $393,000, which is median price reported by the CREB.  The reason for the discrepancy is that the $353,700 number includes  the “surrounding district” which means it includes Cochrane, Airdrie and some of the farming communities surrounding the city (Acme?).  If you include the metro Calgary area only, which is what the local real estate board does when they are reporting statistics (because they like to print higher numbers), it would put Calgary into the “seriously unaffordable” category.  I cannot find data on the area used to calculate the average household disposable income of the city, but I imagine it would be based on tax receipts and thus be restricted to the metro area.

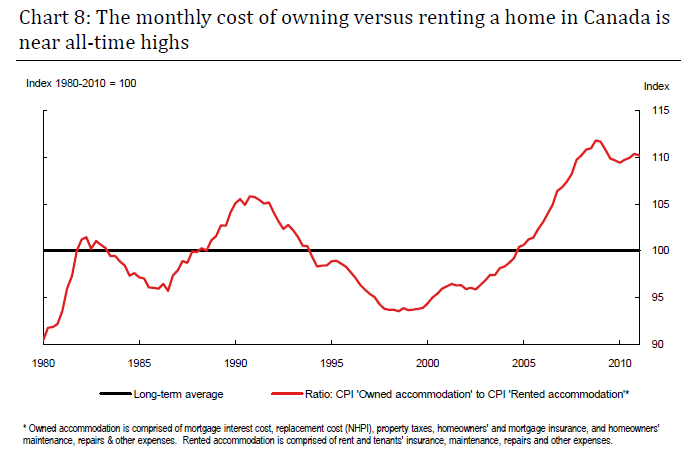
Back to Canada as a whole, price to rents tells the same basic story.

Its either a heck of a bull market or a bubble.

As an aside I was amazed to learn that the price to disposable income in Vancouver is a rather bizarre 10.6.  And that is using a $678,000 median.  If you start using the average home price in Vancouver, the ratio is closer to 15.

Of course none of this has to end until interest rates show some sign of rising.  Right now our househols pays prime -0.9% on our mortgage.  That works out to about a 2% interest rate.  Its rather insane.  Even if we had a $500K mortgage (we don’t) it still be affordable.  Of course if that rate went to 6%, it would be a different story.  Some day that might happen.

Opportunities?

So why am I writing about this?  Well for one, I think its an interesting study.  The Canadian housing market has defied all other housing markets that have crashed and burned in the last few years.   It has also defied most all metrics of affordability.  For all the bears out there that say that the US housing collapse was inevitable it seems a reasonable question to ask: “then why not Canada too?”

I am of the mind that these forever rising prices, particularly Vancouver and Victoria and the inner city area of Toronto, are going to end badly some day.   Everywhere else in the world the 3:1 ratio holds but Canada is different?  The different argument is a big circular one.  Because the different argument inevitably comes down to the fact that Canadians are inherently prudent and would not expose themselves to large risks. Which apparently means that this attitude allows Canadians to take on large risks.  Anyways…

I also bring the topic up as a potential area for short candidates.    Who would be hurt by a price fall?  Particularly Vancouver.

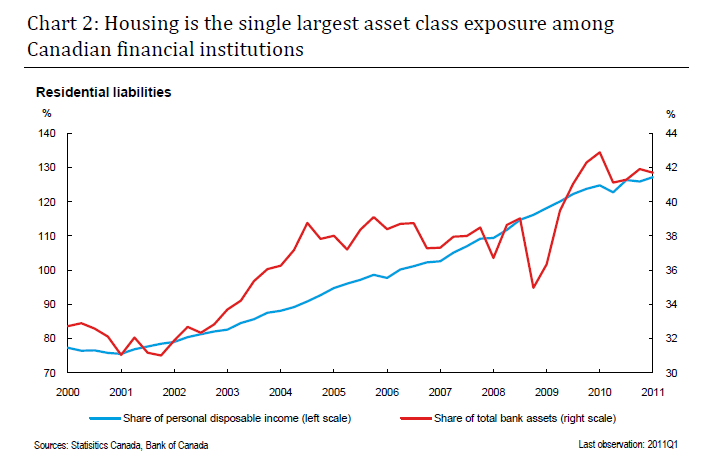
Well first and most obvious is the Canadian banks.  Mortgage debt makes up around 42% of the loans on the balance sheets of Canadian banks.  This number has increased from 31% in 2002.

Another name that comes to mind is Home Capital Group.  The company is always being praised on BNN by some expert making a top pick.  The stock appears to trade relatively cheaply, at less than 10x earnings.  But the business of the company is to make loans to people that can’t qualify for CMHC loans.  I don’t know if the loans they make are “subprime loans” persay, they probably aren’t, but the company fills the exact same niche that the subprime borrowers in the US did.

I don’t know enough about the company to make any more observations than that right now. But it intrigues me.  The company is worth a closer inspection.

And I’m open to ideas.  What other companies could potentially be left with their pants down in the event of a material decline in Canadian house prices?   I think there is plenty of time to gather  more information about this trade.  There probably is not much to worry about until interest rates begin to rise.  And that might not happen for another couple of years.  Please contact me with any suggestions, either by email or in the comments.

Week 30: Cognitive Dissonance, Canaco updates, Canadian house prices and the story of Community Bankers Trust

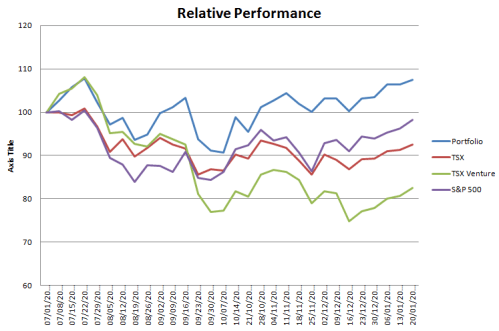
Portfolio Performance
Portfolio Composition

Trying to not be dogmatic

A few years ago I read a book called Mistakes were Made.  The book described our ability as human beings to remain convinced that we are right to the point where we ignore all evidence to the contrary.

Our predisposition to fabricate reasons why we are right and ignore reasons why we are wrong is based on a concept called cognitive dissonance.  As the book defines it:

Cognitive dissonance is a state of tension that occurs whenever a person holds two cognitions (ideas, attitudes, beliefs, opinions) that are psychologically inconsistent… Dissonance produces mental discomfort ranging from minor pangs to deep anguish; people don’t rest easy until they find ways to reduce it.

All symptoms I am all too well acquainted with.

Along the same lines, I came across an interesting piece on FT this week.  The following quote can be attributed to SocGen’s Dylan Grice:

But all is not lost. The bias towards thinking we’re more correct than we are isn’t driven by an inability to fully assimilate undesirable information but an unwillingness to do so. Therefore, the first step in removing the bias is to adopt procedures that foster a more honest acceptance of logical conclusions. Logic has no emotional content per se. There is no such thing as good or bad information; information is only true or false.

But because of our hardwiring, we only want certain information to be true. In particular, we want the information that confirms our prior beliefs and validates our belief systems to be true — about ourselves, about others, about the world. Thus, debiasing ourselves must involve an honest assessment of what we want: do we want to be right about everything, or do we want to know what’s true?

Let’s bring this back to what this blog is about: investing.  In my piece last week I stepped through the basic premises on which I am currently invested.  The tenants I stated were the conclusion of a somewhat anguished and certainly restless mental reevaluation that I had been running through over the prior few weeks.

As the market moved against me I  started to look at why I might be wrong.  In my spare time I tried to “assimilate the undesirable information” and paint the most contrary picture I could.

I especially went through the exercise with gold and with my rather significant precious metal stock positions (Aurizon Mines, Atna Resources, OceanaGold, Canaco Resources, Geologix, Esperenza Resources, Lydian International and Golden Minerals).  Gold is always easy to question (what does gold really do anyways?).  I attempted to soberly evaluate both the prospects of the metal  and the companys.  I looked for reasons to basically cut them loose.

I hemmed and hawed a lot, and at times began to convince myself that I was indeed wrong.   But in the end I was led back to the basic points of valuation and underlying conditions, which seemed to me to remain firmly in gold’s favor.

This is how I make decisions.  At times it undoubtably appears that I am flip-flopping.  I am sure that my weekly writings must have an aire of contradiction when read one after another.  A reader might wonder how it is that my point of view can go from one extreme to another in the matter of weeks (see Argonaut Gold).  Or at times even flip 180 degrees only to flip back a few weeks later (see Argonaut Gold).

In truth, this is the only process I know of that allows me to really question whether I am right.  If I can push myself to the edge, almost convince myself of the diametrically opposed point of view, and still in the end come back to my original conclusions, then well, that’s really getting somewhere.   At times I push myself so far that I actually begin to believe it myself (ah yes, see Argonaut Gold), but that is just a occasionally necessary casualty.  Far more often I leave the exercise with more clarity, and with that clarity comes the likelihood that I will act properly when the situation arises.

In the end I came away from my “anguished” analysis of gold more confident in my positions than I was when I started.  And this week, on Wednesday, when the Fed news hit the wire that interest rates would be low for time eternity, that gave me the clarity to act.

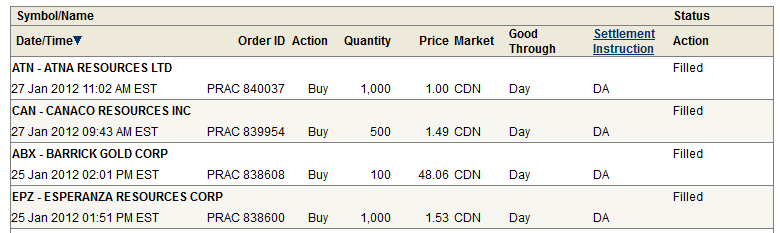
The moment I read the news I bought a position in Barrick Gold, and I added to my positions in Esperanza Resources and Golden Minerals (though I neglected to make the AUM trade in my practice account).  The next day I added to OceanaGold, and thta was followed by additions to Atna and Canaco the day after that.

In my practice account:

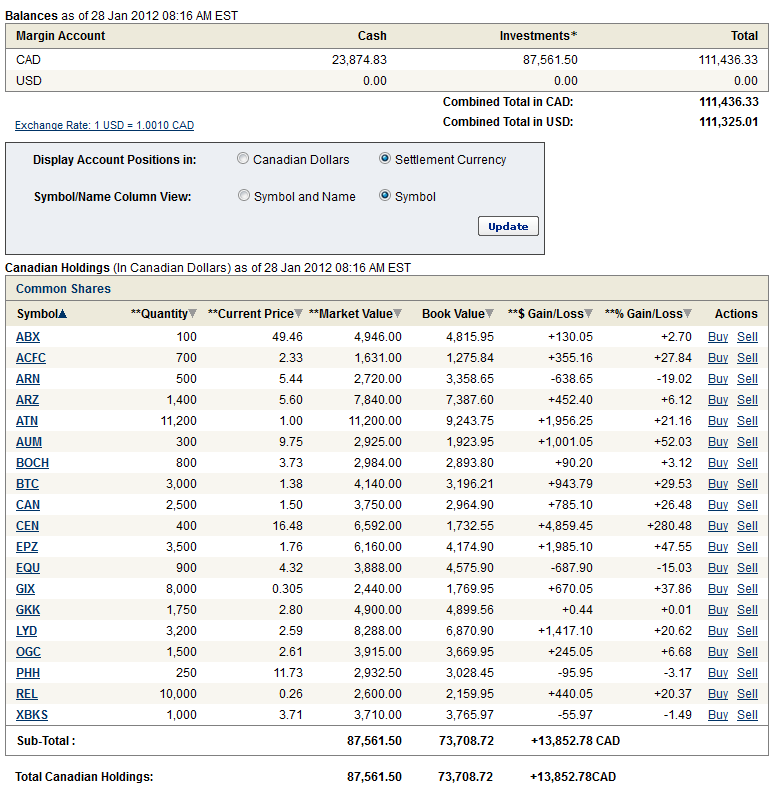
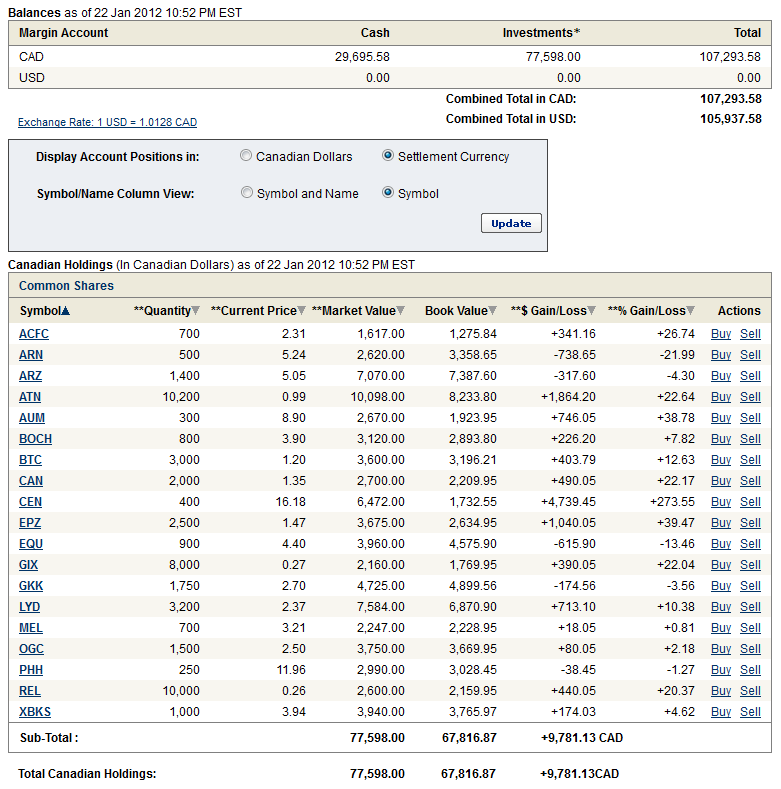
And in my actual account:

You do the work so that you have the confidence to act.  You put in the time learning and working through why so that when an opportunity makes its brief appearance, when Bernanke comes out and says “yeah we aren’t going to raise rates for a long time” you can recognize it for what it is and say “all right, I’m in” and you know what you have to do.

Had I not been stepping through the thesis of why gold and gold stocks remain a solid investment, I likely would not have had the conviction to buy into the rally.  At worst, I would have sold into the rally, because if you really don’t know why you are investing in something you tend to take the first blip after a long period of blah as a “finally I can get out” moment.  As it is, with the Fed putting interest rates on hold for another couple years, and with their actions maybe even foreshadowing a true QE event in Europe, I feel quite confident that I am positioned well for that fall out.

Speaking of Canaco Resources…

I bought Canaco Resources at the end of the year at about $1.10 as part of my “tax loss buying binge”.  A couple of things happened with Canaco this week.

First, the stock went up.

Second, the company updated us on its activities in Tanzania:

  • Expect a resource estimate by the end of March
  • Expect a preliminary economic assessment by the end of the third quarter
  • Expect further metallurgical testing results at some point

Third, Canaccord Capital came up with an updated price target, and more importantly helped give us a glimpse at what to expect from the upcoming resource estimate (hat tip to howestreetbull who posted this on Investors Hub).

  • Canaco has approved a US$35-40 million 2012 exploration budget, and is currently drilling 10,000 metres per month at Handeni with nine diamond drill rigs and one RC rig.
  •  Six of the drill rigs are focused on delineating the Magambazi resource in preparation for the initial resources estimate. Two diamond drill rigs are focused on the Kuta and the Magambazi North Extension targets. The remaining diamond drill rig is operating on the Majiri target, where previous surface sampling and RC drilling indicate a gold anomaly. The RC drill rig iscurrently operating on the Bahati target to test preliminary regional targets.
  • We are expecting an initial resource and metallurgical test results in Q1/12, and a PEA in Q3/12. We are expecting an initial resource of 2.3 million ounces of gold at a grade of 3+ g/t gold. Previous metallurgical testing indicates recoveries of 90+% using a conventional CIL process.

Valuation: with US$110 million in cash, we believe the company is in a strong position to continue to derisk and advance the Handeni project. Our peak gold price estimate of NAVPS (10%, US$1,750/oz) remains unchanged at $7.50. We continue to value Canaco based on a 0.65x multiple to our peakgold price estimate of NAVPS.

At the current price of $1.50 Canaco trades at a market capitalization of $300M.  Subtracting the current cash balance of $115M, the enterprise value of the company is a little less than $200M.  If the deposit does indeed contain 2.3M oz of gold, the valuation being given for those ounces is about $80 per.

This is a 3 g/t open pittable deposit that looks to be 90% recoverable with a straightforward metallurgical process sheet.  In my opinion (and apparently Canaccord’s as well) those ounces should be worth more than $60/oz.

To throw out a comparison point from a recent PEA, Prodigy Gold had a PEA done for its Magino gold property last March.  The PEA assumed a CIL recovery process, a 9 year mine life, producing gold from an open pit at a grade of 1.2g/t for 9 years to give a total mine of life production of 1,585,000 oz of gold.  The after tax NPV5 of the project was estimated at $259M at $1000/oz gold.   That works out to a value of $160/oz.

Albeit there may be better comparisons out there, but this one surely suggests that Canaco is undervalued.  Canaco’s Magambazi project is much higher grade than Prodigy’s (3g/t versus 1g/t).  The location is Africa, versus Canada for Prodigy, which probably suggests a bit of a discount against Canaco but not enough to make me change my opinion.  And while the Magambazi strip is as yest unknown,  the Magambazi deposit appears to be around a hill top, which should lead to a reasonable number (the strip for Prodigy’s Magino is 3.3).

Finally, the last bit of news was that Brent Cook came out with the following plug about Canaco:

“The funds were just jumping in on this thing – and they all bailed out as well – the stock got down to $1.20. During this time period they’ve been drilling and drilling and drilling, and the results continue to show me that they’ve got what I think is going to be a legitimate, decent size, decent grade, open-pittable deposit in Tanzania,” Cook says. “So we’re buying this stock at $1.30 with $115 million in the bank, and a $41-million exploration program. That, to me, seems like a good buy.”

Yup.

When the gold price broke out on Wednesday, Canaco was the first stock I added to.

and speaking of gold…

I came across this interesting piece of information regarding the appetite of the Chinese for gold.   This may be old news to some but I think it is still worth reporting.

The People’s Bank of China  research director Zhang Jianhua was cited as saying Monday in the central bank publication Financial News that gold purchases should be ramped up when prices drop, although he gave no indication of what proportion of the nation’s $3.2 trillion forex reserve should be allocated to investments in gold.

Apparently, Jianhua called gold the only safe haven left and said that:

“the Chinese government needs to further optimize China’s foreign exchange asset portfolio and seek relatively low entry points to buy gold assets…no asset is safe now.  The only choice to hedge risks is to hold hard currency – gold”.

High House Prices

I’ve been doing some research on house prices in Canada and in particular in my city, Calgary.  I plan to do a separate post on my findings shortly, but for the moment I just want to throw up a couple teaser graphs that gave me pause for thought.

The chart is taken from a speech given by Mark Carney to a Vancouver audience last June.  The methodology used is the ratio of the nationwide median home price to the median household disposable income. A ratio of greater than 3 has traditionally been seen as unaffordable.

It makes you think.

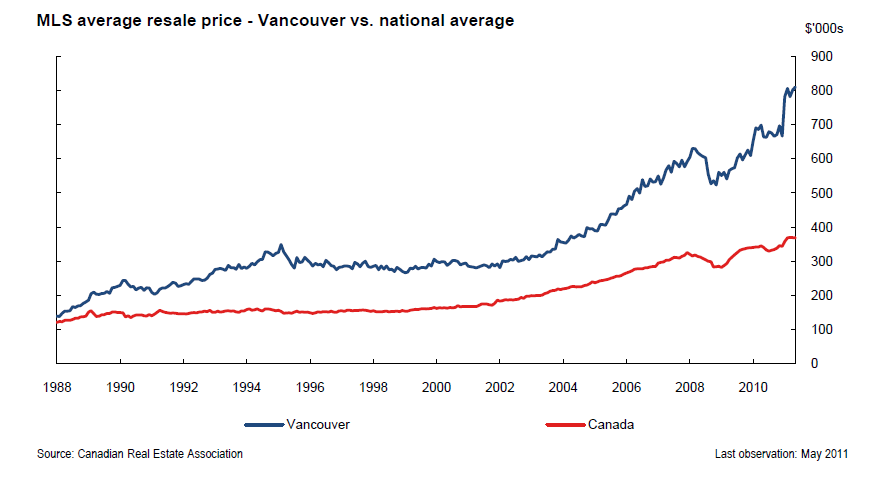
One other chart from the same report.  Below is the average house price in Vancouver:

Its either a heck of a bull market or a bubble.  To say it another way, I don’t know about house prices, but when a stock goes parabolic you typically know how it is going to end.

Anyways, more on this later.

Community Bankers Trust

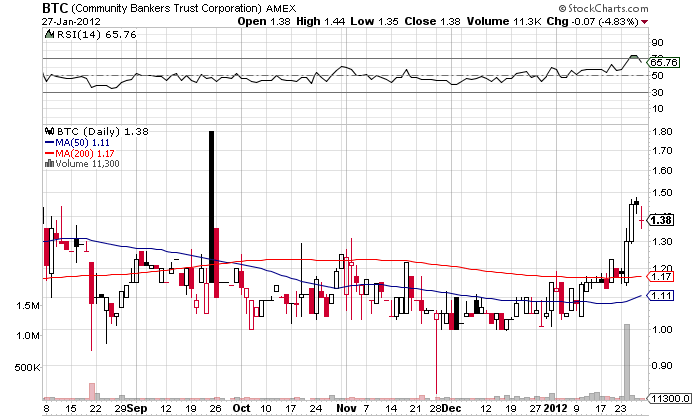
It was a good week for Community Bankers Trust (BTC).

Earnings will come out for the company on Tuesday.  Hopefully the company will put together another profitable quarter.

The BTC story

I bought BTC as a turnaround story.  Community Bankers Trust is a bank that has been trying to reincarnate itself after the first incarnation came close to an early death. My observation is that they have been successfully navigating this resurrection, and with the recent turn in profitability (and a helpful turn in the economy) the bank is on its way to realizing its earnings potential.

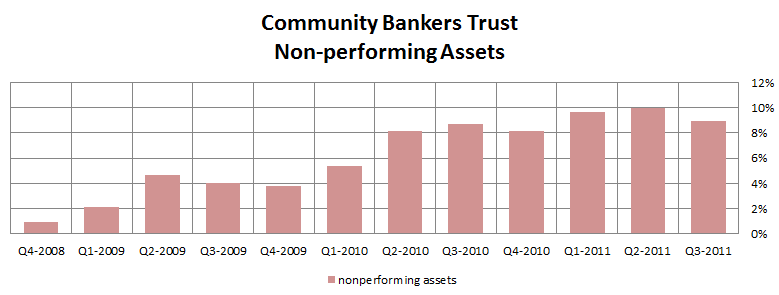
The bank was hit hard by the recession in 2009.  The company saw nonperforming loans skyrocket from 2% of total loans in the first quarter of 2009 to 10% of total loans in the second quarter of 2011.  Yet there have been signs that the efforts the company has been making to turn itself around are working, culminating with a profitable quarter in Q3.

Let’s hope they can keep that momentum.

How did they get to here?

The original strategy of the bank was, as far as I can tell at least, to simply buy other banks and get bigger.  Witness, the name of the original company was called Community Bankers Acquisition Corporation  (CBAC), so they weren’t exactly being subtle.  Along with the acquisition strategy, the bank seemed to have a “worry about the profitability later” strategy, which may have worked ok when the economy was growing but that fell flat when the economy didn’t in 2008.

As best as I can discern the acquisition effort was spearheaded by Gary Simanson. He headed up the original company CBAC, and then moved into a position of Strategic Vice President, a position I don’t think I’ve ever heard of with any other company. According to this article, Simanson was responsible for subsequent acquisitions.

In truth, the timing was what killed the acquisition strategy.  To quickly step through the timeline, in May 2008 the company began its journey by acquiring two local Virginia banks, TransCommunity Financial Corporation, , and BOE Financial Services of Virginia, Inc.  In November the bank moved ahead and acquired The Community Bank, which was a little bank in Georgia.  Finally in January 2009 they acquired Suburban Federal Savings Bank, Crofton, Maryland.

So you had 4 bank acquisitions in less than a year happening at the time of a 100 year financial tsunami.  How do you think things turned out?

Change in Direction

By 2010 Simanson had left the company and the direction of the company was changed to the more pragmatic “we need to get profitable before we go belly up” strategy.

This was described pretty bluntly in the 2010 second quarter report. CEO Gary Longest said at the time:

Our strategy has shifted from that of an aggressive acquisition platform, to one that meets the banking needs of the communities we serve, while providing sustainable returns to our stockholders. To this end, we are taking the necessary steps to return immediately to profitability. We are actively analyzing our market base to assess the contributions of all branches to our franchise value and will take the appropriate actions in the third quarter of this year. Additionally, we will make aggressive expense reductions, and will look to restructure and strengthen the balance sheet. We are confident that the analysis of these potential critical paths and the resulting execution of these initiatives will lead us back to profitability quickly.” “Our goal is an immediate return to consistent quarterly profits. To accomplish this, we have no alternative as a Company but to make clear and intelligent decisions in the next 60 days, no matter how difficult, to accomplish that goal as soon as possible. That is our full focus.”

 In a somewhat odd twist to which I’m sure there is a good story, Longest himself was gone only a couple months later. Nevertheless the interim CEO and soon to be permanent CEO Rex L. Smith took up the reins and has carried out the strategy quite well given the circumstances.

 Where are they now?

I already mentioned that the company had its first profitable quarter in a long time last quarter.  I don’t believe this was a one time fluke.  It looks to me like its the culmination of a number of initiatives put forward by the bank that have been geared towards making the bank more profitable.

The company has made an effort to lower the cost of its deposit base.  Time deposits, which are expensive high interest bearing deposits, have decreased from 73% to 67% of total deposits since the end of 2009.  As well, the cost of the time deposits has come down from 2.9% in 2009 to 1.6% in the third quarter.

The effect has been a steadily rising net interest margin (NIM) since the strategic direction change in 2010.

(note that this graph is a simplified version of NIM calculated as a percentage of all assets rather than the more common formulation of interest bearing assets)

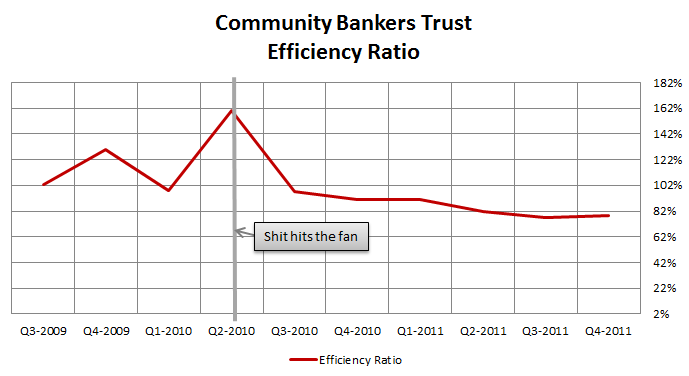
The company also undertook efforts to reduce expenses.  The most common way of illustrating the day to day expenses of a bank is through something called the Efficiency ratio.  The Efficiency ratio is simply the ratio of the total non-interest expenses at the bank (so the salaries, building costs, lawyer fees, pretty much everything except the actual cost of borrowing money) to the  net interest margin (so the amount of interest made minus the amount of interest paid).  The reason that you look at the Efficiency ratio is because it ex’s out growth, since growth should occur for both NIM and expenses in concert with one another.

The Effiency ratio of BTC has been falling consistently.

What’s it worth?

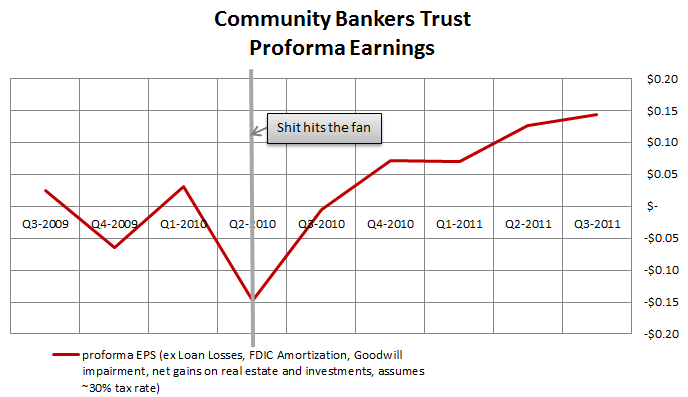
To get an idea of what the bank might be worth if it continues to pull itself together, I put together a proforma earnings estimate.  I stripped out all the provision for loan losses, the FDIC intangibles (from their earlier acquisitions) that the bank is required to amortize, as well as losses on real estate and gains of the sale of securities.  So basically I looked at the banking skeleton that is BTC.  Here is what I found:

What this clearly demonstrates is that if get rid of all the scabs, there is quite a profitable little enterprise here.

Meanwhile, the bank sports a tangible book value that is much greater than the current share price ($1.40 after last weeks run up):

What is left to be done?

The story that still needs to play itself out is the healing process.  The really big negative for the bank is that it still has an extremely elevated portfolio of non-performing loans.  There are signs that this is abating, and in truth part of the bet here is the same one that you make on any regional bank: the US economy is turning the corner, the Fed is not going to allow it to fall into another recession, and so the worst of the loan defaults are behind us.

But just to get an idea of the risk here, typically you wouldn’t want a bank to have non-performing loans in excess of a couple of percent.  Many of the best banks I’ve looked at have nonperforming loans of well less than 1%.  BTC, onthe other hand…

There are tentative signs that the peak has passed, but it will take a few quarters before we know for sure that further write-downs are not coming.

Earnings on Tuesday will give us a lot of insight into the direction of the trends.  I’ll be looking closely at nonperforming assets and the 30-89 day deliquents (which are an early warning of the soon-to-be not performing.  I also will be hoping to see some decent earnings.

What is the LTRO going to do for Europe? And how does it affect my stocks?

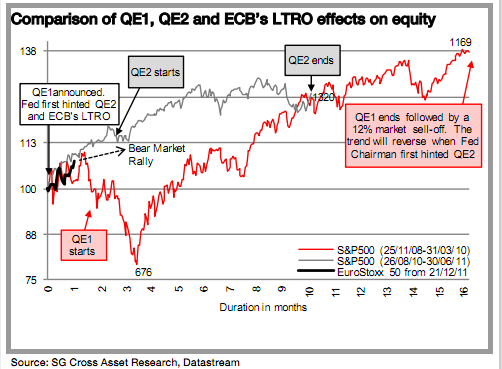
I think that the essence of this bullish rally can be summarized by this one chart

Investors have taken to the opinion that the long term financing operations (LTRO) provided by the ECB back in December has removed the risk of collapse in Europe from the table, maybe even for a couple years. It’s all clear to buy stocks.

Investors are of the mind that the LTRO has removed the risk of collapse in Europe from the table, maybe even for a couple years.

As described by Citigroup:

The ECB’s LTROs have succeeded in breaking the negative spiral of rising risk aversion, poor asset performance and forced selling. Money is cheap, and every day, confidence is building little by little, prompting buying. The resulting asset performance in turn raises confidence further. The lack of street inventory implies small shifts in demand have a much bigger impact on spreads than in the past.

I underestimated the effect of the LTRO. I might have recognized that having a liquidity backstop for the banks would be a big confidence builder for the market.  Unfortunately I didn’t.  Whether this confidence can be sustained, well that is a question I hope to look at here.

Things came very close to going sideways

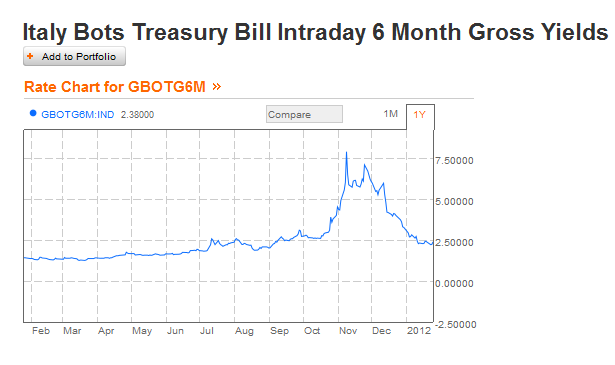
We were on the edge of the cliff at the end of November and early December. No where can these be seen more clearly then by the yields of short term bills of the periphery. While I have put up the chart for the 10 year Italian bond a number of times, I have not focused on the short term bills.  Below is the rather shocking collapse and then restabilization of the 6 month bill in Italy.

The LTRO coincided with a tremendous drop in short term yields.  A lessor, but still significant, drop came in longer term yields.  Equities rose as yields fell and the crisis abated.

Is it sustainable?

Citi doesn’t think so.  In the same note Citi says that the rally is likely mostly based on fumes. The reason?  While QE1 and QE2 stimulated lending (and speculation), the LTRO is not expected to stimulate anything other than bank liquidity.

To put it simply, almost all the big banks in Europe are going through a process of deleveraging.  The LTRO simply helps them through this process without putting undue stress on one another, like the stress at the end of November last year.

FT had a good piece on just what the ECB’s intent is for the LTRO. In it they argue that the ECB did not create the LTRO funding to flood the EU with Euros or to stimulate government debt buying by banks. They did it to “stop a heart attack of bank deleveraging in the eurozone.”  When the LTRO is understood this way, it can be seen that it is more akin to the Fed’s response to the commercial paper crisis in 2008 than it is any QE.

This is an important point.

Providing liquidity directly to banks for operational use, as the Fed did in 2008, has historically not been much of a prop to equity markets beyond an initial, confidence induced, blip. The Fed did all sorts of operations in the fourth quarter of 2008. It wasn’t until it embarked on a true QE in 2009 that the market actually responded favourably for an extended period.

It makes you wonder what the half life is of the LTRO effect.

What are the mechanisms of transmission?

The problem is that the LTRO is a liquidity mechanism and the problem in Europe is not a liquidity problem. As Mauldin pointed out in that piece I referenced last week, europe has a solvency problem brought on by countries that simply aren’t competitive and banks and sovereigns that are overleveraged. QE begins to solve the solvency problem because newly printed money pays off old, otherwise unpayable debt.  But is the LTRO intended, or should it be expected, to do that?   I don’t think so.  Its just a long term repo, or in other words, long term borrowing for the banks with very little restrictions on the collateral they have to put up in order to get the money.

I think that to speculate on the real effect of the LTRO on equities over the medium run, you have to think about the mechanism by which QE causes the market to rise.

So certainly there is a change in market psyche.  QE lifts the spirits of the market.  The LTRO did that too.  I would attribute the rise in stocks over the last few weeks mostly to this effect.

In our current case, there is probably also an element of pessimism that was no longer warranted.  The bank stock in Europe, in particular, had been priced to fail.  Failure was no longer imminent, so a rally had to be expected to reprice a degree of solvency back into the stock prices.

Those two elements are probably the biggest effects in the short term.  At some point though, they are going to wear off, and the market is going to start asking, so what is this LTRO actually doing?   Its this longer term impact where the picture gets fuzzy because I don’t think the LTRO has the same long term effect as QE.

The two main long term (with long term meaning months) effects of a QE program is  that the excess money sloshing around from the QE lowers the cost of funding, entice businesses and consumers to borrow, and it provides banks with the liquidity and capital to make more loans.

The problem is, I don’t see that happening here.  Banks in Europe are in deleveraging land.  Just as would be expected, the evidence is that the banks are taking the money and turning right around to inject it back into short term bills (see that chart of Italian bill rates above).  They want liquidity that can be easily accessed in case their wholesale funding dries up.  They don’t want to make a 3 year loan to Acme Manufacturers, taking on the associated risk.  They already have too much risk on their balance sheet.

This is great for the bill market; rates fall, and it certainly removes the most stressed condition from Q4, but if the money not finding its way into the economy, what good is it going to be for growth?

The Eurozone still isn’t growing much

Back to the Citi note one last time:

Despite a mild winter the European economic data isn’t really improving. Our economists have just lowered their Euro zone growth forecast for 2012 from -1.2% to -1.5%. Spain’s Budget Minister Montoro has just warned the country may miss its 4.4% budget deficit target for 2012. The earnings season has been decidedly mixed, with about 60% of US S&P 500 companies beating to date – much lower than in past quarters.

Access to liquidity just lets banks keep on keeping on for a few more months. Like the Fed operations in 2008, the liquidity injections led to short term spikes but no lasting impact on the market. I am willing to speculate that the LTRO response with follow suit.

Capital Ratios an other impediments

Another FT article, this time referring to Richard Koo of Nomura, speculated similarly.  Koo is talking specifically about the impact of the 9% capital ratio, but as he alludes to, there are a number of factors producing the same basic effect on banks: new capital is used to assist in de-leveraging, not growing:

What is preventing the funds supplied by the ECB from flowing into the real economy and improving economic conditions? Although there are a number of answers, the biggest obstacle from a policy perspective is the European Banking Authority’s tough new capital rules.

The EBA has demanded that European banks raise core Tier 1 capital to 9% of risk-weighted assets by June 2012. None of the policies unveiled in response to the crisis has been so counterproductive…This 9% rule effectively prescribes the size of European banks’ balance sheets. This means banks will not be able to increase lending no matter how much liquidity the ECB supplies, effectively rendering any monetary accommodation by the ECB powerless to stimulate the economy. The EBA’s 9% rule may help in preventing the next crisis, but it will do nothing to resolve the current one—in fact, it will make it much worse.

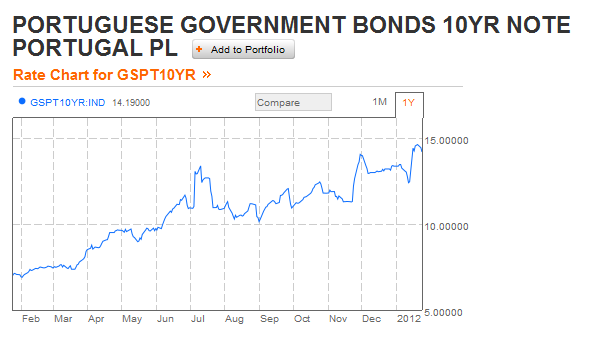
Yields in Portugal aren’t falling

On a related note, one of the most interesting developments over the past month is that the Portugese 10 year yield has NOT fallen.

Investors aren’t being totally fooled by the LTRO.

In the next few months we should start to get a better picture about the impact of the austerity measures on the economies of Greece, Portugal, Italy and Spain.  I would speculate the numbers will be grim, and a lot of the wind provided by the LTRO will be knocked from the sails.

Bringing it all back home (to the portfolio moves)

As you know, I continue to hold a couple shorts of European banks.    I also added more gold stocks yesterday (specifically ABX and more OGC)  after the Fed news so these banks shorts could be seen as a bit of a hedge on my rather large gold stock position.

The other day I was contemplating some of my positions which had begun to move against me.  A lot of that has cleared in my head over the last few days.  The Fed announcement brought back my conviction in gold stocks.  And after taking a long and hard look at Europe, I have decided that I am likely on the right side of this bet, and while I would be wary of adding too much to that bet as the market moves against me, its not time to cut it just because of a few tough weeks.

The biggest thing that I think I have to remain wary of is that the ECB holds the trump card here.  A true QE style of bailout in the neighbourhood of E2B to E5B would truly push the problem so far out that it would be someone else’s worry.   Today’s announcement by the Fed to keep rates low for much longer than most anticipated could be seen as a step towards that.  At the end of the day, realizing that the LTRO is not the QE that everyone seems to be interpreting it as leaves an open question: is the QE still to come?

Week 29: Conviction and Humility, Investigating PHH, Don’t forget about Atna, Buying Midway

Portfolio Performance

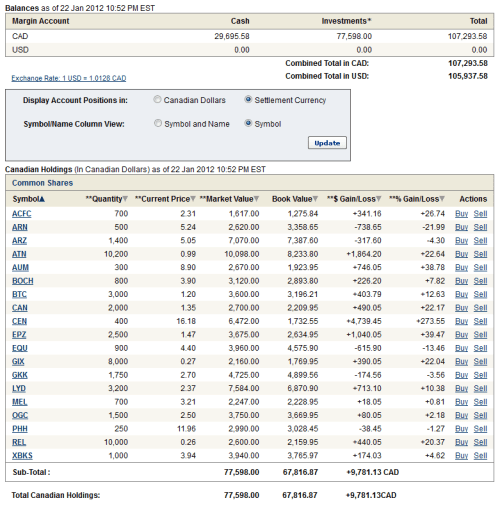
Portfolio Composition:
On Conviction and Humility

I find that investing in stocks is a constant antithesis/synthesis (to use a couple of terms from philosphy) between conviction and humility.  Never is this more evident than when things aren’t going your way.

While the market has been up the last couple of weeks, and my portfolio has been up somewhat as well, it is not doing as well as I would like, not as good as the market even, and that makes me want to reevaluate.

Part of me wants to just get out and start all over again.  Right now there are things of  which I am wrong.   Wrong about some of the gold stocks I own (while Atna continues to do well, Aurizon is not doing well, Lydian is not doing well, and a couple of my more recent purchases, Esperenza and Canaco, have stalled out).  Wrong about some of the oils I own (I probably should have sold out of Reliable Energy at 30 cents)  that aren’t doing much of anything.  Certainly wrong about my big bad bailout bank short bet, which went quite far south last week.

The other part of me, pushing just as strongly, wants to stay the course and, more exactly, to ignore what the market might be telling me because the market is wrong and I am right and in time I will be vindicated.

It goes without saying that this last attraction is a dangerous one.  Surely we all have listened to the expert that held his conviction against all evidence to the point where his credibility was lost forever.

The truth between these two extremes lies, of course, somewhere in the middle.  The difficulty is figuring out exactly where that is.

The basic long term investment theses on which I am currently holding stocks (and shorts) are as follows:

  1. Europe is on an inevitable course to dissolution, with a collapse in Japan not far behind
  2. Gold is the only asset that is no one’s liability and it will gain respect as a store of value as these events unfold
  3. The US, while troubled, is muddling through, and the US housing market has likely had, as Kyle Bass has put it, the pig go through the python
  4. Oil is harder to find and harder to get out of the ground then most people appreciate, and its price will prove sticky to the upside
  5. The hz-multifrac is a revolutionary technology and so you want to own oil companies that can take advantage of that technology

I think its helpful to review these basic points on occasion, particularly when things are not going my way.  If I can still stand by these tenants then the rest is just a matter of evaluating if the individual stocks themselves are decent businesses (or perhaps more importantly good stories) in their own right.

And, having thought about it over the weeked, I wouldn’t stand away from any of the above.

Two weeks of a market moving up with many of my stocks doing nothing can seem like an eternity.  Sitting with as much cash as I currently have (though I have reduced that cash level somewhat, mostly in response to specific opportunities and a recogntion that the deterioration of Europe no longer seems imminent) while the market rises, can be tough to bare.  But I can’t just abandon what makes sense because of a few tough weeks.  If the facts change, certainly I have to change with them.  No doubt about that.  But when the main fact that has changed is that the market is not going down any more, I think it is wise to respect that fact (no sense doubling down and some sense in lightening up with what doesn’t work) but not so wise to change course entirely.  Better to move as a big ship might, slowly inching it way towards a new course, ever on the lookout for signs on the horizon that might make the destination more clear.

Wading into the Mortgage Market

On Tuesday this week a 13-G was issued that Hayman Investments (the hedge fund run by Kyle Bass) had purchased over 7% (4,448,751 shares) of PHH Corp.  I got a google alert  on the news almost immediately.  It still wasn’t soon enough.  The stock was up 10% within minutes and closed up 12% on the day.

I sat down on Tuesday night with the intent of understanding what Bass what was up to.

I don’t think this is just Bass buying a cheap company (which they are) and hoping for the best.  I think there is more to this story, as I will explain below.  But first, lets talk a bit about where I think we are in the housing cycle.

First of all, I am no blind optimist here.  I don’t think for a second that housing is about to make a robust 180 with rising prices and robust new builds.  That’s not happening for a long time yet.

But that does not mean that all housing company’s should be left in the trash bin.  No I think that those that rely more on volume then price may find themselves doing better this year, and may be ripe for a move.

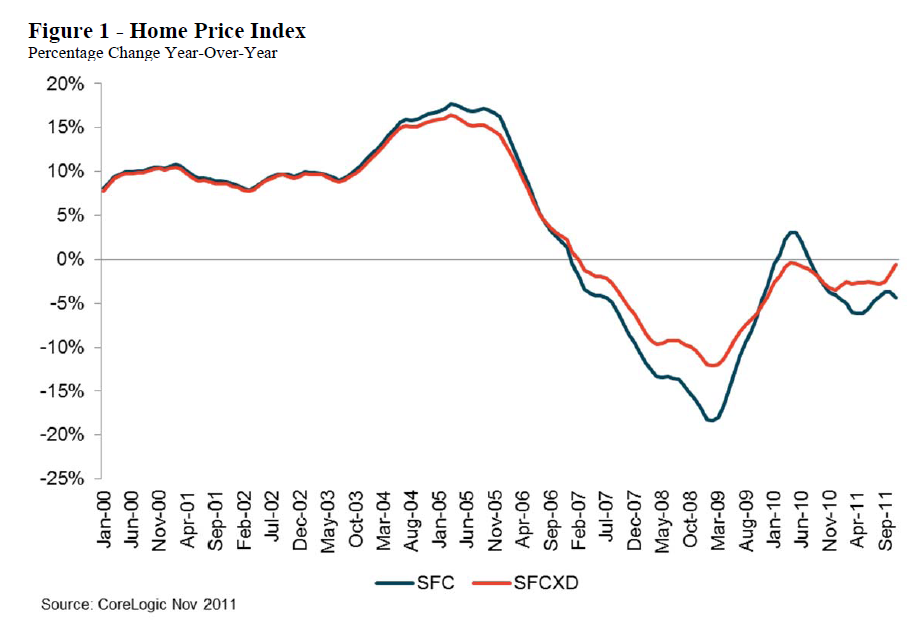
Why?  Because I think prices have fallen enough in many markets.   Most of the damage in terms of declines appears to have been done.  There was a great graph provided by Core Logic a couple weeks ago that showed prices both including and excluding foreclosures.

Illuminating!  If you ignore foreclosures, prices nationwide are on the verge of going positive.  If you look at the regional data, prices are actually up in many locales.  And while some areas are still bogged down in foreclosures, many have worked through the worst of it.  Those are going to be the areas where we start to see a turn.

So it makes sense to look for companies that stand to gain from these first signs of stabilization.

And with that, onto PHH…

PHH is in the business of mortgage origination. They are in the business of mortgage servicing rights.  Tthey are also in the business of commercial vehicle fleet management but I don’t think that’s the story here so I’m not going to dwell on that.  Lets talk for a minute about the two former businesses.

Mortgage Origination

Mortgage origination basically consists of finding a person that needs a loan to buy a home, showing that person a list of mortgage options of how they could finance that loan, qualifying the borrower for loan guarantees such as those from the GSE’s, and then processing the loan through (doing all the paperwork) and passing it through to the eventual lender institution (usually to Fannie, Freddie or a bank that will either keep it on their books or sell it to another investor).  PHH takes a cut in the process, or an origination fee, that is typically between 1/2% and 1%.  In the third quarter the company said that their “pricing margin also expanded by more than 47 basis points as compared to the second quarter.”

Mortgage Servicing

Mortgage servicing happens after the loan is made. The servicer is responsible for calculating how much the borrower owes and collecting that amount.  If a loan is not being paid then the servicer takes on additional responsibilities such negotiating a workout upon default, looking after the foreclosed property and such.

PHH refers to these businesses as a natural hedge of each other.  Why?  Because they are inversely correlated with respect to interest rates.

Let’s say interest rates fall.  What happens?  People with mortgages at higher rates refinance those mortgages.  That’s great for the origination business.  They are writing up refi’s and taking in the fees.

Not so great for the servicing business. Those refi’s mean that the mortgages that PHH has the rights to service no longer exist.  Now ideally PHH originates the refi and thus takes on the servicing rights for that refi so the old mortgage servicing right (MSR) is replaced with a new one.  But there’s no guarantee of that.

Rates go up and the opposite situation occurs.  Origination suffers, no one is refinancing at the higher rates, but that also means the MSR’s are not being lost either.

As it is, PHH has proven to be pretty good at holding on to more MSR’s then it loses.  Forthe 9 months ending in the 3rd quarter the company had a replenishment rate on MSR’s of 167%.

Ok, back to Bass.  There are a number of things happening in the mortgage business right now from which PHH stands to benefit.  Let’s go through them one by one starting with Harp II.

HARP II

Harp stands for the Home Affordability Refinance Program.  Harp II is the name that has been coined for the new version of HARP.  It supersedes the original Harp.  Harp I was a total failure.

The HARP program has helped far fewer borrowers than its proponents estimated — roughly 894,000 borrowers since Aug. 31, 2011. — and many less than the estimated 11 million U.S. homeowners who owe more than their homes are worth.

Why was it a total failure?  A few reasons:

1. Put back risk: Basically when a bank participated in the original program they were worried that they would get stuck with the original mortgage.  I think what happens here is that to rewrite the original loan to new terms, the loan is going to be scrutinized.  The banks and other underwriters know that the quality of many of those original documents are sketchy at best and they would rather not have to pull out the skeletons.

2. LTV Limits: This is probablythe biggest problem.  The original HARP program dealt with current loans with LTV’s of 80-105.  That was expanded to 125 in 2009, but that still wasn’t enough.  I was surprised by that until I read this:

This should have a big impact in certain parts of Nevada, Arizona, and Florida where many borrowers owe more than 125% of the value of their homes. In Nevada, for example, two thirds of all loans backed by Fannie Mae are underwater, and half of all loans are above the 125% loan-to-value cut-off.

3. Appraisal costs: the borrower had to have an appraisal done to qualify for the original program.  That appraisal could cost $400.  Borrowers were reluctant to take this cost on when there was no guarantee they would be accepted by the program

HARP II aims to correct these mistakes.  The LTV limit is gone.  Appraisals are no longer required.  And banks are protected against the put backs.Says Brian Ye, analyst at J.P Morgan Chase & Co:

“We are of the opinion that there are enough changes to the program that bank servicers could really change their behavior, and this could be one of the first times that the administration has under-promised and over-delivered,”

The two tiers of HARP II

There is one particular element of the new program that helps out PHH is that servicers get a head start over third party originators.   I confess I don’t know just what of impact this is going to have, but it is interesting and potentially significant, so I think its worth mentioning.  Servicers like PHH have been writing borrowers up for the program since the beginning of the year.   A third party originator cannot submit any documents to Fannie or Freddie until March.   This was done to entice the banks into the program, but the corrollary is that a company like PHH can capture business up front without the competition.

There is more interesting information on the new HARP program here.

What’s it going to mean?

This is, of course, the big question. The program is aimed to attract two million borrowers by the end of 2013.  This would be a little more than twice what the original program attracted.

However if the program works, and if JP Morgan turns out to be right and the administration “under-promised”, there is certainly a lot of room for upside.  According to CoreLogic:

10.9 million, or 22.5 percent, of all residential properties with a mortgage were in negative equity at the end of the second quarter of 2011.  Eight million borrowers with negative equity, or nearly 75 percent of all underwater borrowers, have above market rates. The disparity is even greater for those with severe negative equity. More than 40 percent of borrowers with 125 percent or higher loan-to-value (LTV) ratios have mortgages with rates at 6 percent or above, compared to only 17 percent for borrowers with positive equity.

Apart from the obvious fact that these numbers show just how staggeringly bad housing has become, if you prefer to see the glass half full those numbers also suggest that there are a lot of borrowers out that could benefit from a program like this.

I was listening to this week’s Lykken on Lending and they were talking about Harp II.  Lykken said that listeners (brokers and third party originators) needed to gear up for the “mother of all refinancing booms”.  In another segment a couple of weeks earlier Lykken and his guests spoke quite excitedly about the impact of no LTV limits. The one guest talked about how common it is to have to turn away borrowers because they are too far under on their home.  HARP II should help with that.

BOA and correspondent lending – another tailwind

So first of all, what is a correspondent lender?

Consider a broker who develops significant business volume, has earned the confidence of wholesale lenders who will authorize him to approve their loans, and has accumulated some capital. He can now obtain a credit line from a bank that can be drawn against to fund loans, repaying the loans when they are sold to wholesale lenders. Under the law, the broker has morphed into a “lender” – the type called a “correspondent lender”.

This has been a business the big banks have taken a large piece of.   Until now.  In August BoA reported that they were exiting correspondent lending.

This isn’t small potatoes.  It accounted for”47 percent of Bank of America’s mortgage originations, or $27.4 billion, in the first quarter of 2011, the Wall Street Journal said citing Inside Mortgage Finance.”

There are rumors others are leaving the business.  Its a low margin, highly competitive business but it could become less so with some of the big players moving on.

In comparison, for PHH total mortgage closing volumes for 2011 so far were $36.3 billion of which approximately 70% were retail and 30% were wholesale/correspondent.  Here is what management said on the Q3 conference call:

Yes I’m going let – yes the answer to the question is yes, we think there are better opportunities but once again we’re really pretty opportunistic in that channel. So we pay close attention to margins in that channel. As you know it’s probably the most cost competitive channel, it is the most cost competitive channel that we operate in and we’ve seen some really strange behavior in that market in terms of where margins are being priced. Some of our competitors are in the market, when they are in the market they’re very aggressive in terms of their pricing and then they back off and they’re out of market and that’s why we stay really opportunistic in that market. Luke, do you want to add anything?

The company made a total of $95M off of mortgage production, meaning off of fees for new originations of that $36.3B of loans they processed.  The company doesn’t break down the margins between the retail and the wholesale/correspondent.    Total revenue from the segment was $264M, which suggests that the fees on average are around 0.7% of total loan value.

Tailwind 3: Signing up new partners

The last tailwind for PHH is that they are having success signing up some big partners for their origination business.  From the Q3 CC:

We also made significant progress in growing our nationwide sourcing footprint over the past two quarters signing five new private label accounts. The new relationships include Barclays which we mentioned on last quarter’s call and today we’re pleased to announce that we’ve added Ameriprise and Morgan Stanley Private Bank along with two other financial institutions all as new PLS partners.

They also lost one significant client in Charles Schwab but over all the company expects to gain significant production:

We expect the five new PLS accounts in the aggregate based on their 2011 production and taking into account ramp up time and anticipated launch schedules to produce about 7 billion in closing volume in 2012, about double what we predicted for Schwab.

Twisting in the (tail)Wind

The Donald Coxe conference call this week was very good, and it produced one particularly enlightening graph.
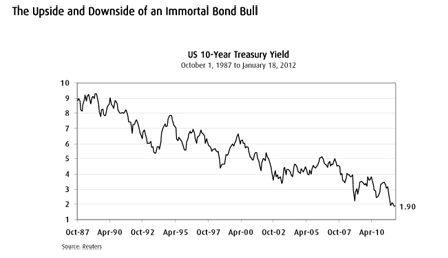
Long term rates, both treasury and mortgage, are at all time lows.  When the Fed embarked on operation twist, it was with the intent of bringing down the long end of the curve, and by doing so, propping up and ideally pushing ahead, the housing market.

I would say this was a success.

When you add to the fact of HARP II that interest rates are at all time lows and really, given the decline in house prices in many markets, are basically creating the conditions where you would be crazy not to buy a house, you just have to think that this is going to help origination activity in 2012.  I think the point that is sometimes forgotten is that the downard spiral of housing is really caused by the foreclosure mess.  Its the lynchpin.  If you could create the conditions to stem that flow, I think the situation would right itself a lot faster than is appreciated.

When core earnings matter

A lot of the time when a company is reporting some sort of non-GAAP earnings, its in order to hide something.  A good example of this is Salesforce.com.  They report non-GAAP earnings that exclude certain costs (particularly stock options) that they would rather ignore.

PHH reports a core earnings number every quarter but for a very good reason.  Core earnings is a far better representation of the company’s profitability than is the GAAP number.

The problem with the GAAP number is that it is obscured by changes in the mark to market value of the MSR portfolio. PHH has to write up and down their mortgage servicing rights with changes in interest rates and to a lessor degree credit quality.  When rates go down they have to write down the value of the rights and when rates go up they have to write up the rights.

The fluctuations on the income statement caused by these mark to market moves are huge.  Up to $400M in some quarters.  If you look at quarterly GAAP earnings over the past couple years they look like a scatter chart.

The reality of the MSR’s is that as long as the company is replenishing the existing pool with more rights from new originations then its losing to payoffs of its existing pool, its all good.  As I already noted, PHH is doing that.

The core earnings number takes out that effect. And if you look at that core earnings number you see a pretty cheap looking company.
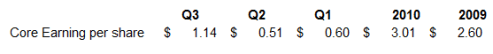
All that, and discount to book…

The last point I would like to make about PHH is the discount relative to book value.   You can get the shares at a pretty substantial discount, even after the post-Bass run up:
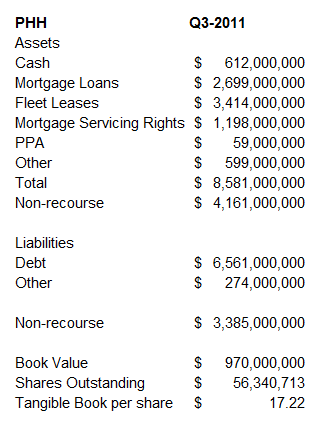
What’s even more interesting is that this discount exists even after the valuation of the MSR portfolio has been clobbered by falling interest rates.  It is not impossible to imagine a scenario where the MSR’s add book worth $500M plus, or another $10 per share.

So what does Bass see?

To sum it up, with PHH you are getting a cheap company that has earned decent money of late and that should benefit from the tailwinds of HARP II, weary competitors and a rebounding housing market.

The negative with PHH is the debt they have coming due, and whether they will have the cash to pay it off.  That debt is an issue I believe is worthy of a post in itself, and I will try to get around to that next week.

Europe is still a problem

…it just doesn’t seem like it right now.

I have a few other things I was hoping to talk about this week but I’m running out of time and this letter is getting quite long already.  But I do want to talk a bit about some of the reading I have done on Europe the past week.

It seems what with the stock market rising every day that Europe is old news now.  Yet I think that to ignore the risk of Europe right now, to go all in, is still at best a gamble.  It may turn out, you could do it and cash out big in 6 months.  But to say you knew it would turn out that way would be kidding yourself.  We could just as easily wake up tomorrow in crisis mode again as in the happy-happy-risk mode that we’ve been in the last couple weeks.

Europe  hasn’t gone away.

The S&P downgrade of a number of European countries been widely reported already so I’m not going to dwell on it, but I do want to point out that the language used.  In particular:

We also believe that the agreement is predicated on only a partial recognition of the source of the crisis: that the current financial turmoil stems primarily from fiscal profligacy at the periphery of the eurozone. In our view, however, the financial problems facing the eurozone are as much a consequence of rising external imbalances and divergences in competitiveness between the EMU’s core and the so-called “periphery”.

This strikes at the basic point that I have made in past posts.  Austerity measures are not going to fix the problem with Europe because the problem is not a one time spending binge that just has to be paid off.  The problem is much deeper, relates to inherent inequities in the productive abilities of the economies, and is quite possibly not solvable without a break up.

As John Maudlin said in his piece “End of Europe”:

For most of the past two years, European leaders have tried to deal with the problems as though they were short-term liquidity problems: “If we just find the money to buy some more Greek bonds, then Greece can figure out how to solve its problems and then pay us back. Given enough time, the problem can get solved.”

They have now arrived at the understanding that it this not a short-term problem. Rather, it’s a solvency problem of the various governments, which of course creates a solvency problem for their banks. They are now addressing the problem of solvency and providing capital until such time as certain countries can get their budgets under control and the bond market sees fit to provide the capital they need.

But they are completely ignoring the third and largest problem, and that is massive trade imbalances. Germany exports products to the peripheral European countries, which run trade deficits. As I have shown in several letters, a country cannot reduce private-sector leverage, reduce public-sector leverage and deficits (balance its budget), and run a trade deficit all at the same time. That is simple, unavoidable math, based on 400 years of accounting understanding. Ultimately, there must be a trade surplus if leverage and debt are to be reduced.

There is a great model that Maudlin creates in the post that summarizes the situation of Greece, Portugal et al to a tee.  I would recommend reading the piece in its entirety.  One last point from the piece:

Prior to the euro, the imbalances would be handled by currency exchange rates. The value of the drachma would go down relative to the value of the deutschmark. Things would balance over time. Now, all of the eurozone countries are effectively on a gold standard, with the euro standing in for gold this time. Britain, the US, and Japan print their own currencies. Their currencies can rise or fall over long periods of time, based on national accounts and the desires of foreigners to buy goods or invest in their countries.

He is retreading the old Jane Jacobs idea that I brought up a couple weeks ago:

What Europe has embarked on with the Euro is the exact opposite of what is needed.  Currency regimes need to evolve to produce better feedback, not worse.  The Euro currency feedback mechanism is skewed by the strength of the German economy (actually more exactly the economy of its one or two prime export replacing cities, Berlin and Frankfurt).  Peripheral countries like Italy, Greece, Spain and Portugal are doomed to receive faulty feedback rather than the natural “export subsidy” that would occur if those countries had (lower value) currencies of their own.

To think that all is well is to mistake the calm eye of the storm for the end of it.

Meanwhile, I’ll end my Europe talk with this: There seems to be a growing recognition that Greece needs to exit the Euro.  The chief executive of Germany’s natural gas firm Linde’s chief executive Wolfgang Reitzle was quoted as saying the following in Reuters:

“In the medium term Greece needs to exit. And the writedowns on Greek debt will not be between 50 to 70 percent, but in the end will be written down by 100 percent,” Reitzle said.

Asking Germans to pay more than 50 percent taxes to help fund other euro zone countries will erode the will of the German electorate to support rescue measures, Reitzle said.

Although this scenario is not desirable, he felt that German industry would survive working in a new currency.

Atna’s jump in reserves (and share price)

I haven’t spent as much time as I should writing about Atna.  I tend to ignore the stocks that I am right about.  This is perhaps not the best way to self-promote, but since I’m not really in that ballgame anyways, who cares.  I learn more from my mistakes.

But don’t take that for disinterest.  I watch Atna like a hawk every day. As I pointed out a month ago, I think that if Pinson works out the stock is worth somewhere between $3 and $6.  I know that there is some skepticism around Pinson, that there may be rock stability issues, but I’m of the mind that the current stock price is more than pricing in that risk.

It feels to me like a stock being accumulated before a break-out.  Perhaps we got a taste of things to come this week when the stock popped over $1 and up to as high as $1.05.

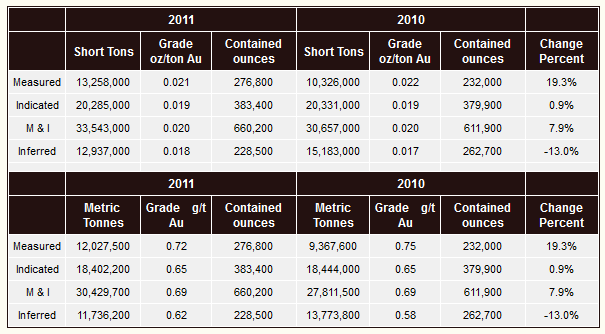
On the news front, Atna released an updated resource at Briggs on Thursday.
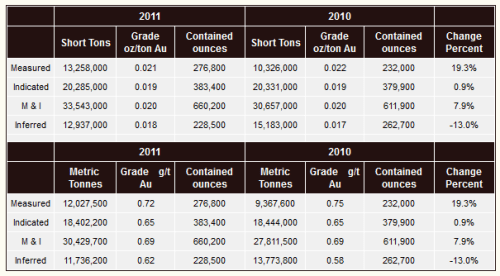
There is not too much to get too excited about, though it is nice to see that they managed to move about 50,000oz to measured and indicated, basically replacing production.  Overall they showed a slight increase of about 14,000 oz all in.  At the current production rate (45,000 oz), Briggs is good for another 10 years. That alone is probably good for the current share price.

Buying Midway Energy (Again)

The other move I made this week was to reinitiate a position in Midway Energy.  I decided to pull the trigger here because the other Swan Hill players showed signs of moving up towards the end of the week.

I already own positions in Second Wave and Arcan (though the Second Wave position didn’t get taken in the practice account due to an unfortunate glitch in the order fill).  I did not own Midway and it had not moved higher and it seems a reasonable presumption that it will follow suit eventually.