Skip to content

New Position in MYnd Analytics

Well we are less than a month into the new year and I am already breaking a rule.  Rule #2, stay away from illiquid stocks.  So what do I do?  Two days later I buy a stock that trades 20,000 shares most days.

That said the stock has had a lot of volume the last few days.  So it’s not illiquid at the moment.  And I am keeping my promise to write more. So there’s that.

Here’s the scoop.

Mynd Analytics (MYND) has a not-so-interesting legacy business of providing psychiatric help via video conference to patients in remote areas.  They have a second not-so-interesting business of offering a platform (called PEER) that helps doctors prescribe for psychiatric conditions.

Two not-so-interesting businesses are not a good reason to buy a stock.  What is interesting here is a merger that was announced a few weeks ago.  Mynd Analytics is merging with a private biotech firm called Emmaus.

Emmaus has a much more interesting business than anything Mynd has, so this is more of a reverse takeover kind of merger where the new company is going to be Emmaus, not Mynd.  In fact, exiting Mynd shareholders are going to get about 5.9% of Emmaus.  They are also going to get a spin-out of the two not-so-interesting businesseses into a separate company.

So while those businesses are not very interesting to me, the market was still saying they were worth up to $1.50 a few months ago.  So basically as a shareholder I get what I already had, plus now I get a piece of Emmaus.

Getting a piece of Emmaus is interesting.  Emmaus is in the early stages of marketing a drug called Endari.  Endari is approved to treat sickle cell disease.

Sickle cell disease (SCD) is an awful sounding inherited disease where your blood hardens, which can cause stroke.  There are 100,000 patients in the U.S, another 80,000 in Europe, and over 400,000 in Africa and the Mideast.

There is only one treatment on the market for SCD.  It’s called hydroxyurea and its been on the market for over 20 years.  It helps in most cases but it’s not a cure and it produces a lot of adverse side effects in patients.

Endari has went through FDA approval trials and its efficacy has been demonstrated.  It provides improvement in adverse events over the placebo, both on its own and when used with hydroxurea.   Importantly it is well tolerated by patients.

That last clause in the sentence is important, because physicians can prescribe hydroxurea and Endari together.

While it’s expensive to prescribe, insurance companies have been very willing to add Endari to their list.   Why?  Because adverse events for sickle cell patients are severe.  They require ambulances, hospital stays and are extremely expensive.  Endari comes at an ASP of $30,000 ($20,000 net to Emmaus after rebates and coupons).  All it takes is a couple less hospital visits and Endari pays for itself.

Okay, so the drug is effective.  What’s the stock worth?

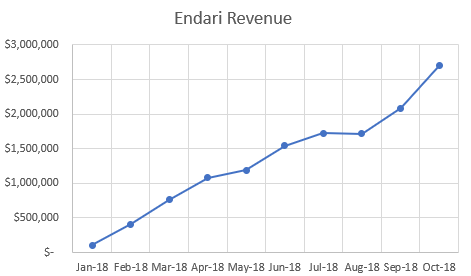
Well Emmaus just started their ramp with Endari in January.  The CEO, Dr. Niihara, who is also the founder and inventor of the drug, gave us an indication of the sales ramp in a PiperJaffrey presentation they gave in November.  This is gross revenue.

They also said there was about 1,200 patients on Endari at the time (so November).  That roughly lines up with the gross ASP of $30,000/year.

Niihara also forecasted 10,000 patients on Endari by the end of 2019.

So the math on that is 10,000 patients at $20,000 net ASP is $200 million of annual revenue.

The math on the post merger valuation is that there will be about 160 million shares of Mynd Analytics outstanding.  I bought the stock at $1.40 so that gave it a market cap of about $225 million.  Now the market cap is around $280 million.  I actually added a little at the open this morning after I wrote this up because it made more sense to me once I put it down on paper.  Sometimes writing clarifies the mind.

Somehow under 2x revenue for a biotech with a new drug ramping and an orphan drug designation seems too low to me.

Endari is on patent in the US for another 6 years.  There is a 10+2 patent in Europe that doesn’t begin until its approved.  There is another patent in Japan.

The  $200 million should be just a start.  It’s basically a 10% market share in the US, but market share isn’t really the right term here because it can be used at the same time as its competition.  Europe has a TAM of another $1.2 billion (the ASP is Europe is expected to be a bit lower).  ROW TAM is another $3.4 billion.

So the TAM is reasonably big.  It’s not like Endari is going to top out in a few months and stop growing its market.

Given that I think the stock isn’t pricing this in.

On the risk side, I have lot’s of questions.  First, why is Emmaus doing this?  They said they don’t need capital and its cheaper to merge than an IPO, which is fair.  They also get the $60 million or so of net operating losses, so that’s a reason.  But I have to think that after the lock-up (120 days) some of these early investors will want out.

Second is the risk that Endari falls flat.  I have no reason to think that from what I’ve read, but the drug is an improvement, not a cure.  I am also no biotech expert.  There are also a bunch of drugs in the pipeline that are a few years from approval and will be competition.

Third, I’m not sure how far off that competition is.  Both Global Blood Therapeutics and Novartis have recently received fast track designation for their drugs.  It’s not completely clear to me what that means for approval.

Fourth, the spin-off of the psychiatric business is likely to get sold hard when it happens.  Everyone now is buying for the interesting business and the not-so-interesting business is an afterthought.

Fifth, I don’t know much about Emmaus beyond what is on their website and what is in the disclosure documents.

Sixth, if the government shuts down again god knows when this will close.  I’ve been waiting on Eclipse and Blue Ridge to close for like 8 months now.

Seventh, prior to the merger it seems like there was quite a bit of management deals on shares and related party transactions from the not-so-interesting businesses they operated.

There are others, but that’s a few to ponder.

Nevertheless it seem like a decent speculation at this price.  And it let’s me write something up quickly and keep new years resolution #4.

Week 394: New Years Resolutions

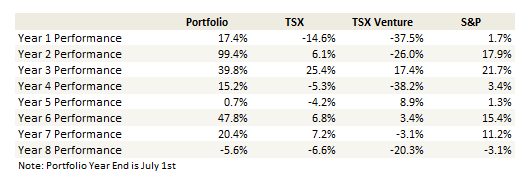
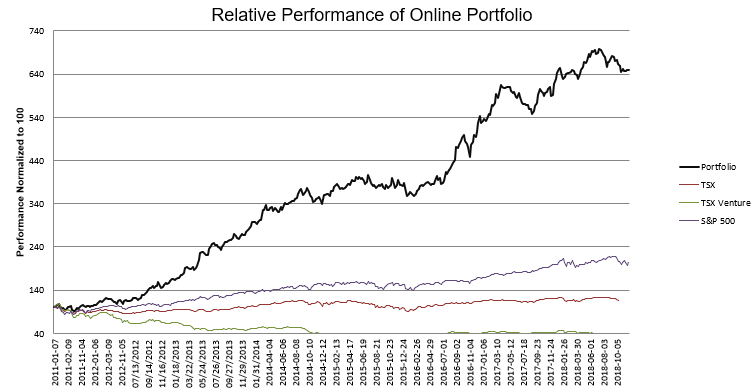
Portfolio Performance

Thoughts and Review

Here are a few investment resolutions for the new year:

  1. After a stock has a good run, I will sell a decent amount of it, no matter how much I like it.
  2. I’ll stay away from illiquid stocks that will be hard to get out of in a bad market
  3. I will stay away from stocks with high levels of debt
  4. I will be very thoughtful before purchasing any stock not generating free cash flow
  5. Be selective
  6. Post more!

These resolutions could also be described as Lane Sigurd’s investment strategy for a bear market.

Some of them are at odds to how I have invested over the long bull market we’ve been in.  Over that time I held my winners and watched them turn into two, three or five baggers.  I didn’t worry about debt.  In fact I coveted levered stocks that would really run if the tide turned.  I didn’t give a second thought to liquidity because I was always able to get out.

I think we are still in a bear market.  Maybe we’ll top out soon, maybe we’ll run back up near the highs, I don’t know.  But I am positioning myself based on the expectation that in the next few months there will be another leg down.

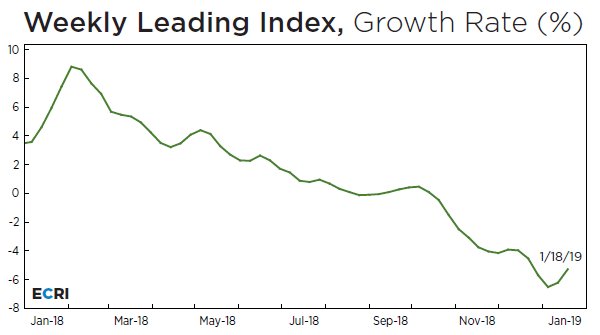
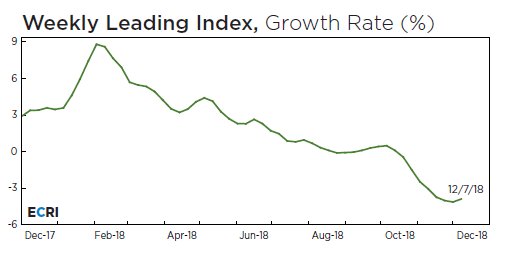
Having said that, there is a bit of good news.  The Weekly Leading Index looks like it might be putting in a bottom.

Is it possible this is just another 2016-like blip?  Possibly but I’m still going with the bear market view.  Maybe I’ll have to change my mind on it.  But not yet.

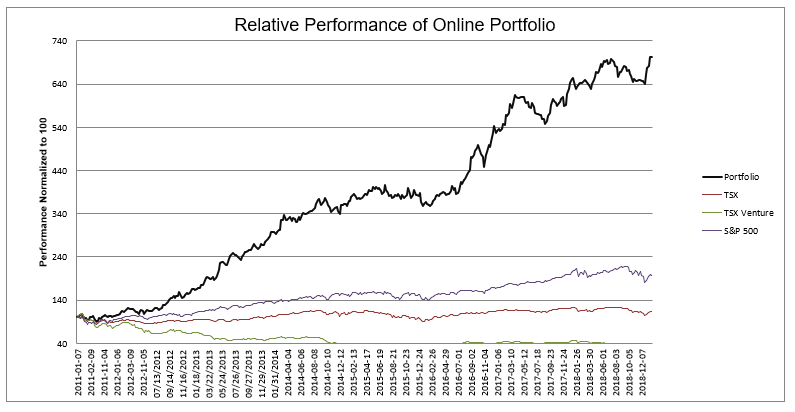
Looking back, December was a tough month, but I had a lot of cash and that helped cushion the blow.  And while I was not lucky enough to go all in at the bottom I did pick at a few positions in December, and the positions I held onto had big runs in January.  So I sit here now at (somewhat shockingly) new portfolio highs.

I’m a bit surprised by that.  My portfolio still has some 70% cash after all.  The market still isn’t great.  It’s really just a bit of luck and timing really.  A number of my remaining positions had big runs.  Liqtech took off.  Gran Colombia took off. Vicor, Golden Star and Wesdome all had nice moves.  UQM Technologies got taken over.  I bottom fed on a few small positions (Identiv, UQM and a few oil names) that all had really nice bounces off the bottom.  Meanwhile I went a few weeks where none of my positions went down.

Having had good performance while not owning very many stocks makes me think that in this market I would be better off being selective than to go with my more usual shot-gun like approach.   In the past I’ve taken small positions in a bunch of stocks, even if I wasn’t completely sold on them all, and watched whether they would develop.  A few would become big winners and I’d add to those as they went up.

I’m not going to do that in this market.  Instead I’ll hold cash and wait for stocks that I have a lot of conviction with.  We’ll see how it works.

So it was a pretty good month.  But I am not overstaying my welcome.

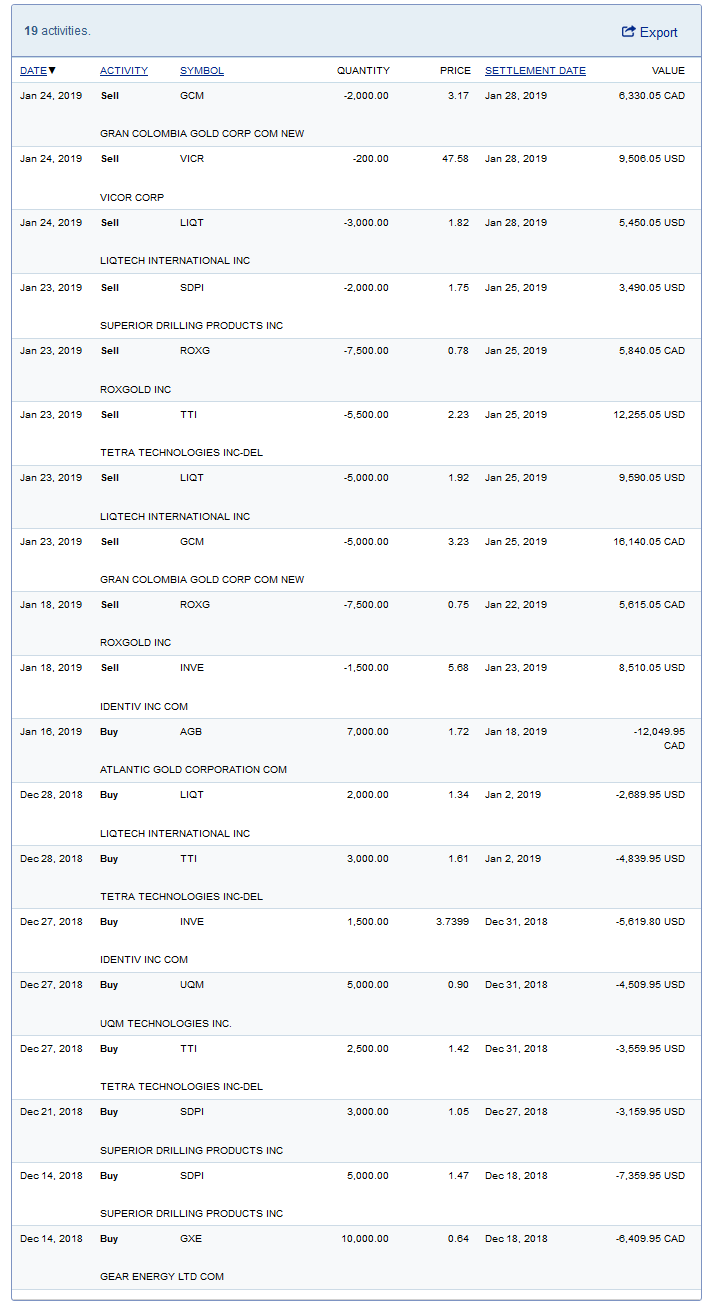
True to my first resolution, I have been selling my winners.  I sold out of three of my trades entirely already (Identiv, Tetra Technologies and Lone Star).  I reduced my Liqtech position by half.  I reduced Gran Colombia and Vicor as well.

I sold some losers too.  I got rid of Roxgold, Gear Energy and reduced my position in Empire Industries.

One stock I’m not selling is Wesdome.  As much as I love my other gold names, the more I dig into what Wesdome is onto at Kiena, the more I love it the best.  It’s not cheap I know, but its got so much going for it.  It’s in Canada and not in an area with questionable politics.  There are two mines with great potential for expansion.  But what I really love about the story is just how cheap the growth from Kiena will come for.  Something I had overlooked in the past were comments by Wesdome management that the mill at Kiena is worth $100 million.  That is basically a $100 million asset that was useless that is now an integral piece of their development plans.  That they can bring Kiena on-stream (and I’m seeing estimates from anywhere between 90,000 oz to 130,000 oz from brokerage for the project) for $50 million is about the most efficient gold development project I’ve seen.

As for my last resolution, I have been lax about posting.  It’s harder to post in a bear market.  Even when I get up the courage to buy a stock, I have weak conviction because of the market.  I find that it takes a lot of conviction to write about something because mentally it kind of ties you to the idea.  That makes me reluctant to lay out a thesis when I might get scared and sell a week or two later.  Or worse, I might hold it because I wrote about when I really should be selling.

UQM Technologies is a good example.  I bought it in November, sold it, then bought it again in December.  I didn’t write about it either time, even though it was a great story.  I was just worried the market might keep falling and I would be doing another round of selling if it did. UQM would be a stock I would cut.  Fortunately the market turned around and I didn’t.

I’ll try to put aside those fears in the new year and write about my positions more.  Even if I look at all of them right now as having the time frame of a pin-pulled hand grenade.

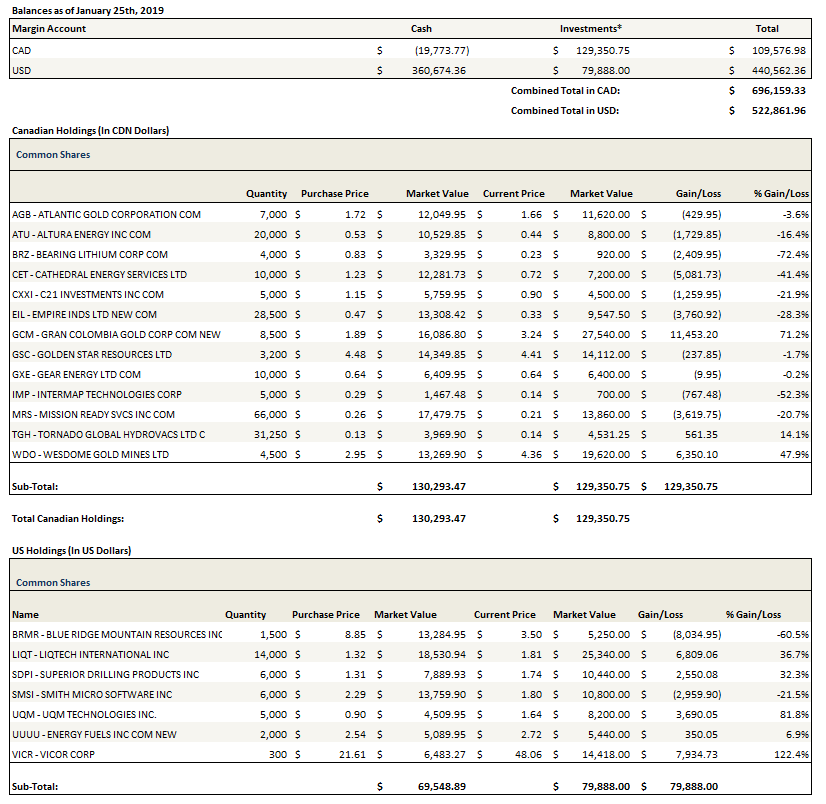
Portfolio Composition

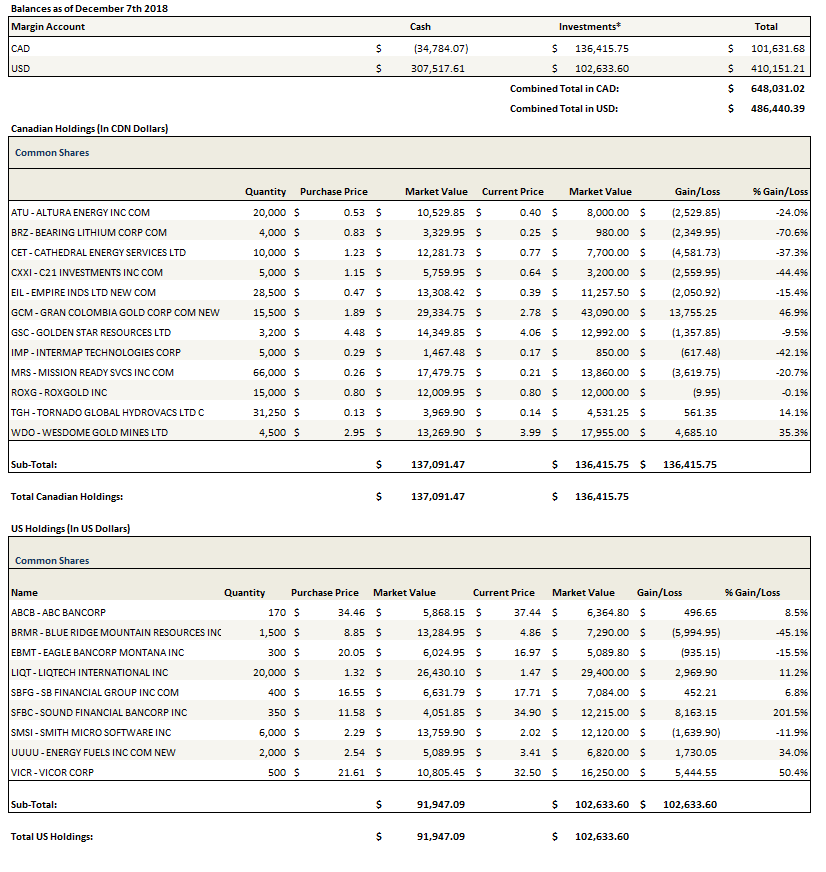
Click here for the last seven weeks of trades.


Week 387: My Recessionary Portfolio

Portfolio Performance


Thoughts and Review

I haven’t written in a while.  I don’t have much to say, the markets are brutal and I am in no hurry to start picking new stocks.  So its not a lot of fun writing.

I have continued to sell stocks in the last two months.  My already high cash position is even higher.  I’ve hunkered down.

I see no choice but to continue to sell.  The problem is that with the small and speculative stocks in a bear market the only safe place is cash.  So even as I went into the fall with a very high cash level, over the last 8 weeks I made it even higher.  As of this weekend the online portfolio I track with this blog is at 75% cash.  That trails my actual portfolio, which is now up to 85% and my RRSP is basically now a GIC.

I even sold my long-held bank stocks this week (not reflected in the portfolio below, which I updated for December 7th).  It’s a bit of a personal watershed for the portfolio and the blog.

I rarely have talked about these stocks since they are boring, but they have been great performers for the last 6 years.  I’ve held them through pretty much the entirety that I have been writing this blog.  Which is to say some tough times!  Yet with the yield curve inverting and leading indicators rolling over I decided to finally exit the trade.  I sold Sound Financial, SB Financial, Eagle Bancorp, and ABC Bancorp (they were the firm that took over Atlantic Coast Financial).  It was the end of a era!

That I am selling these stocks, which I held through some crummy times in 2015 and 2016, should tell you something.  I’m pretty bearish on where the economy is at.

The weekly leading indicators put out by the ECRI were at 144 week lows before a slight uptick this week.

The pH report recently said (also in a Real Vision interview which I’m not sure I can reproduce here so I won’t) that they thought we were on the cusp, if not in, a global recession.

Chemicals are the best leading indicator for the global economy. Data for both Chinese and global chemical production are warning that we may now be headed into recession.

On top of that we have the Fed raising interest rates and quantitative tightening, which are reducing the availability of credit.

And then there’s the trade war.

If this isn’t the tide going out, I don’t know what it.

Look, I’m not the smartest guy in the room.  All of the funds and firms and experts undoubtedly know more than I do.  So I might be wrong and maybe this is another pause, another correction, before takeoff.

What I do know is to respect my limitations.  And trying to guess the bottom in a market that is in a downtrend on top of a bunch of negative economic data just seems like a foolish exercise to me.

No one is paying me to take risk.  So when the environment isn’t conducive, why should I?

The last time I did something like this was January 2016.  That period turned out to be a false alarm.  This one might too.

This is what I wrote in my February 2016 blog post.

The point of existence of a hedge fund is to risk money in order to make more of it. You can argue the particulars of that statement, that risk reduction can occur through various hedges, diversification, concentration, whatever your flavor is, but the bottom line is that the money should be at risk somewhere or why is the fund even there?

But that’s not my job. While part of what I am trying to do is of course maximize my profit line, my first mandate is also very clearly and in capital letters, TO NOT BLOW MYSELF UP.

What I guard against with absolute vigilance, is insuring that my capital doesn’t permanently disappear.

You can look back on these comments and say they were poorly timed.  February marked the bottom, the market started to recover, in the fall when Trump was elected it really took off.

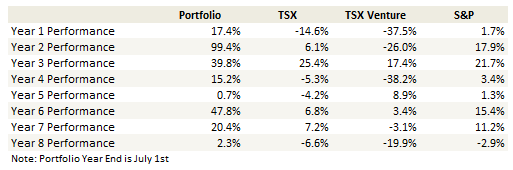
But the reality is that I greatly benefited from that rally.  My Year 6 performance (the table at the beginning of this post) from June 2016 to June 2017 was one of my best 12 month periods.  The market turned and so did I.  If that happens again I’ll turn on a dime just like I did then.

But I’m not going to sit around and wait for that turn while the market grinds lower.

You can look through my portfolio and look at what I sold.  I’m not going to go through the whole lot.  What I’ve held, I’ve done so for two reasons.

First, most of these stocks aren’t terribly economically sensitive.  Liqtech isn’t go to sell less scrubber filters because the economy is slowing (in fact a lower oil price probably means they sell more).

Second, the TSX Venture has already gotten creamed.  The few Canadian stocks I hold there have not done great, but they’ve done okay.  This seems like a bad time to throw in the towel there, especially since the positions are small.

And then of course there is Mission Ready which apparently isn’t going to trade again until the next decade.  Not that I’m complaining.  If I had the option to put all my stocks on a trading halt for the next 12 months I think I’d have to consider that.

(As an aside there was a piece of bullish news out of Mission Ready just released on Friday.  One of the company insiders exercised their 15c warrants that expire in a week.  One would think that an insider would not exercise warrants if they thought the Unifire deal was going to fall through).

So I don’t know.  Maybe I will find another compelling recession proof stock that will compel me.  That might be a hard proposition.  If not, and if this is more than your run of the mill correction, then this blog might be a bit boring for a while.

I’ll tell you though that when I see the turn, I’ll be in the middle of it.

So I did take a small Canadian oil position this week.  I don’t know how long I will hold it so take this for what its worth.

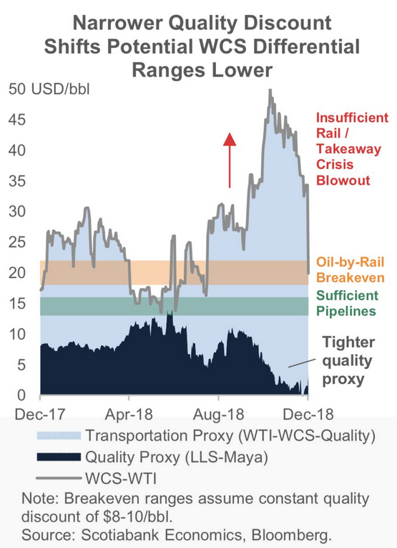
Gear Energy.  I owned it before and sold it after Western Canada Select spreads blew out.  The stock fell apart like I thought it would.  But in the last week and a bit the mandatory production cuts implemented by the Alberta government have worked wonders on Western Canadian Select differentials.

Part of the mandatory cut is that companies producing under 10,000 bbl/d are exempt.  In fact companies under 10,000 bbl/d can actually produce up to that level before being affected by the cut.  I was surprised to find this to be the case.

Before being forced to shut-in production in November Gear was guiding to 7,500 boe/d.  They have an acquisition that will bring that up to nearly 10,000 boe/d but those assets are in Saskatchewan and so they shouldn’t count toward the ceiling.

Small companies like Gear (and Altura Energy, which I continue to own) are in the unique position of benefiting from the spreads and having the ability to grow.  I don’t know if the market will see it that way.  I have heard the argument that capital just won’t come back to small-caps period. Maybe so.

I haven’t run the numbers for Gear but I did a detailed type curve model of corporate production for Altura and found that at C$40/bbl realized prices they can drill 5 wells next year, stay within cash flow and grow production slightly.  Right now WCS prices have risen to over $50 (the latest PSAC quote has them at $54).  At those prices Altura can grow production significantly (10-20% I think) while staying within cash flow.  I’ll maybe do a post of my model there shortly.

These companies aren’t in a terrible position any more.

No guarantees I keep any of my positions.  All comments in this market have the life expectancy of a hand grenade.

Portfolio Composition

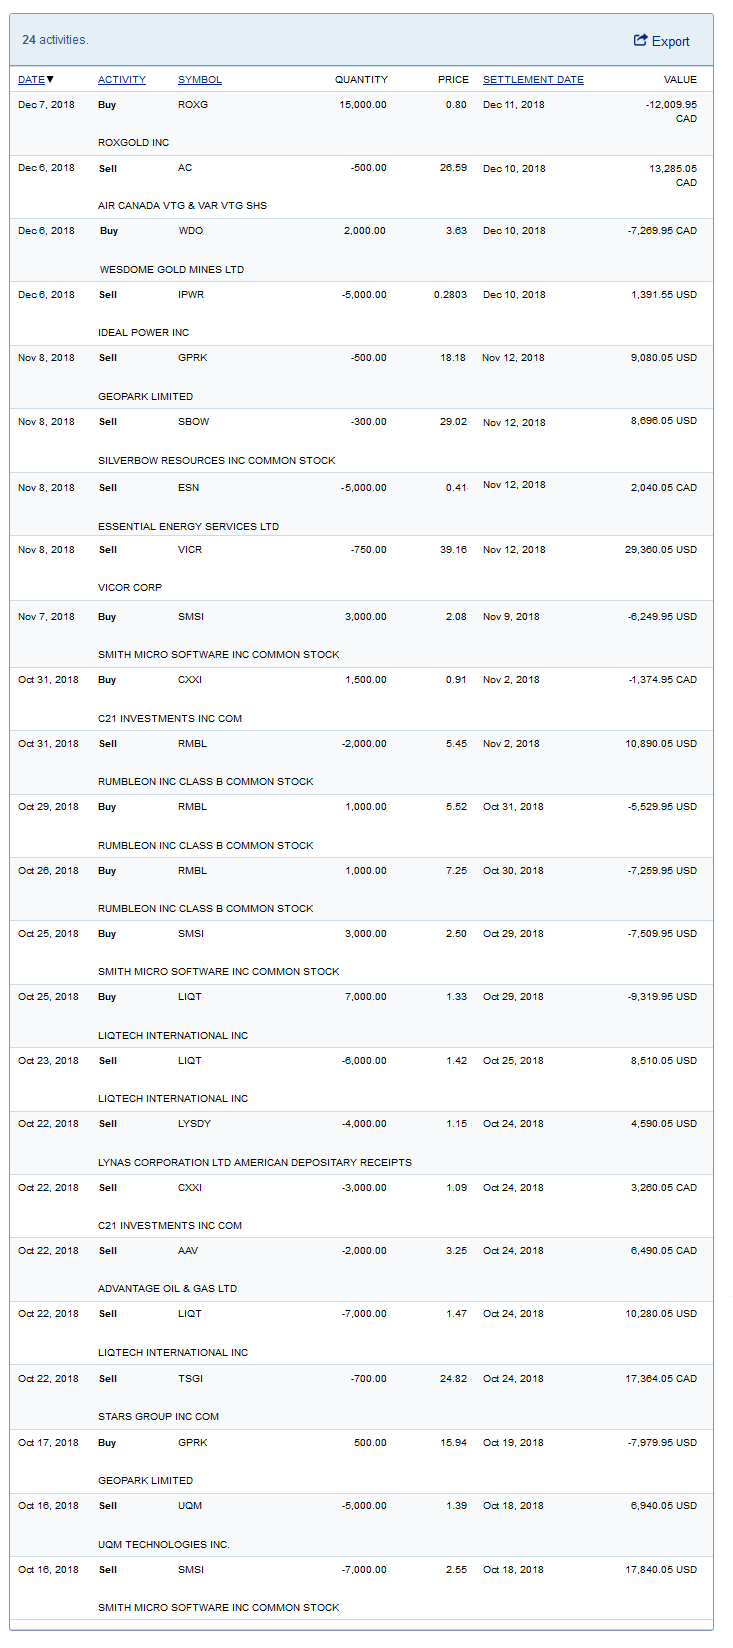
Click here for the last eight weeks of trades.  Note that this update is of December 8th, so it is a week old and doesn’t have my small purchase of Gear, my bank sales or my sale of Smith-Micro.

Comments on RumbleOn and Liqtech, also Smith-Micro and Vicor

I wrote a couple of lengthy responses in the comment section that I have reproduced here.  One was on RumbleOn (here).  The other was about Liqtech (here).  I also comment on Smith-Micro and Vicor briefly.

Liqtech

1. Isn’t the installation of scrubbers self-defeating if too many ships continue to use HSFO?

A couple points. First, assuming that there is a point where its self defeating to install scrubbers (which I am going to raise a question about in a second) I believe that its far enough away that if it happens Liqtech will have benefited well beyond what is justified by the current share price. Consider that right now we are talking a couple thousand ships getting scrubbers out of a 70k fleet. And my numbers are assuming Liqtech only gets a fraction of those ships (ie. I don’t have the latest framework agreement modeled in there, I don’t have direct to shipowner sales, no sales from the other 4 scrubber manufacturers they are working with). Second, are we sure it would be self-defeating? Consider this – What are current HSFO to LSFO equivalent spreads (you have to use a gasoil equivalent for LSFO because there isn’t a true LSFO right now) and what would be the payback on scrubbers at those spreads? I was looking at this a month ago and thinking that at current spreads (so right now, with all ships still using HSFO) scrubber payback would still be pretty good. Isn’t this the worst case scenario for spreads after 2020? To put it another way, the reason ships aren’t installing scrubbers right isn’t because spreads aren’t favorable, its because they don’t have to.

2. What is a fair multiple for Liqtech given that their growth is concentrated on the next seven years and will massively flatten or even be negative thereafter?

While it’s hard to predict that far out in the future, there are opportunities that could result in significant earnings even after the retrofit opportunity has passed.  First there is the new build opportunity – 60% of new builds are being installed with scrubbers. 1,000-1,500 ships a year get built I believe (I’ve never been able to pin that number down exactly, its always given on a DMT basis, not ship basis) and Liqtech is dealing with 7 of the 10 largest scrubber manufacturers. So the opportunity is quite large.

Second, I think the upside from the ramp could far exceed the current share price on its own. While its tough to project because we don’t know yet whether Liqtech will hold its market share through the build, how many scrubbers will be closed-loop or hybrid, etc, if an optimistic scenario holds then the cash they taken in should exceed the existing share price by quite a bit.

Further off there are other verticals where the exposure from being used in a large number of ships will help give them credibility to expand into – such as scrubbers for power industry, oil and gas flowback filtering, and maybe further inroads into DPFs.

But the main answer i that I think the new build opp is going to be large. The bigger question is what does the regulatory regime look like in 7 years and have even stricter environmental regs come in and how do scrubbers fit into that.  And the other obvious big question is whether there are more hiccups in the implementation of the regulations between now and 2020.

3. Will we see lower revenue because the latest framework agreement is for lower ASP systems?

No, I don’t think that’s right. Consider that the new framework agreement is entirely incremental to my model. You can basically add 80-100 units at $230K and 70% margin (they said higher margin and we know existing units at scale are 65% with the Mark 6 design so 70% is my guess). So I think my numbers actually change pretty dramatically for the better with the new agreement. Also consider that the number in my model (80) is actually less than the other two framework agreements. I conservatively said 80 but if you read the transcripts Liqtech said they expect 120 from these two framework agreements.

4. How likely is another capital raise?

Liqtech came out last week and said they don’t need to raise capital this week. They said they had more cash then they had at the end of the second quarter. And soon they are going to be getting a tonne of cash from orders. I agree $4 million doesn’t seem like a lot but given their comments it would definitely be a surprise to me if they raised at this point.

What I think of the IMO 2020 meetings

This wasn’t a question but I had commented last weekend about IMO 2020 here.   This is obviously the big weight on the share price.  I think the upside based on what can happen is a pretty clear picture.  It’s what will happen that was thrown a curveball when the US threw its hat in the ring leading up to the MEPC meetings.  But since that time the IMO approved the fuel carriage ban and basically told the flag states that if you want us to consider a proposal for a more gradual approach we want to see more details.  So the result was constructive for Liqtech.

The risk remains, but in my opinion the risk specific to Liqtech falls as time passes.   The implementation of the fuel carriage ban was the last step for enforcement and that was passed.  The rebuke of the flag state proposal says to me that the IMO wants any proposal to clearly state that they are asking only for waivers when compliant fuel is not available and not looking to delay enforcement generally.  While the clarification comment that the flag states made leading up to the meetings (which I mentioned in my previous comment) said as much, the actual proposal being voted on last week (which was what the flag states wrote at the end of August and had been interpreted by some as “an attempted coup”) sounded like it was more vague.  I don’t think the IMO wants to implement a vague proposal that might open other doors.  So they closed the door on that.

At this point the IMO meets next May.  That meeting might have a clearer proposal for waivers on the table but I think it’s less likely that some sweeping change comes out of the blue and derails the whole thing.   Barring an unforeseen event in the interim, shipowners are going to have to move forward with what they know.  I think this means scrubber purchases move ahead.

RumbleOn

I was also asked what I thought of the Wholesale acquisition by RumbleOn.

I was initially skeptical about the deal.  RumbleOn’s third quarter numbers, on the surface, weren’t very good. The reulsts matched what I had suspected when I was watching inventory on a daily basis – in September the numbers flattened out/turned down.   As a consequence they missed the unit number. I was surprised that ASP was down too. So when I saw the acquisition my first reaction was: hmmm, are they just trying to paper over a bad quarter and slipping growth?

But since then I’ve listened to the conference call a few times, read through all the documentation and I’m coming around to the deal.  The quarter was still not very good though.

Let’s talk about the quarter first.

While the third quarter results and guide are disappointing I’m not sure that they are as bad as they appear at first glance.  If you take management at their word, they changed their acceptance criteria for making cash offers, basically limiting offers to cases where they thought they could make at least $1,000/bike. Their “terminated” offers (meaning offers that they didn’t decide to make after the seller went through the trouble) went up from 2% to 15%, which is a big increase.  They said this resulted in a 700 bike slip in inventory.  That slowed unit sales, which is what I saw on the site myself.

Now you can believe them or not here.  Maybe this is an excuse and the business just slowed.  But what I have seen on the site is consistent with higher margin bikes being available.  They said that their ASP has been much higher in Q4 (anecdotally I saw that too at the end of quarter – that ASP of inventory has definitely gone up).

Maybe the bigger negative about the quarter is that the SG&A as a percentage of revenue did not come down.  It was up a little from the second quarter.  I had been hoping it would come down soon as the company moved towards profitability.  But this didn’t happen, which is a negative.

When I look at the Wholesale acquisition, I understand why the market was lukewarm to it. Wholesale gross margins are tiny, like 4.3%, so even with the volumes (they are expected to sell 2,000 cars a month next year) and even growing 15-20% that’s tough. Carvana has double the margins and the story there is margin expansion as they layer on services. But Wholesale can’t really layer on services because they are selling wholesale, not to consumers.

Therefore on the surface the acquisition kind of looks not that great.  What you can say is that it wasn’t expensive (as one analyst on the call pointed out they are getting the business at 12x income and asked why the owners would sell so low).

So that was my first take.  But I’m more constructive as I’ve thought about it some more. Here’s how I’m thinking about it now:

How much would it take RumbleOn to create a platform and distribution network to populate their new car and truck online portal with 2,000 vehicles available to consumers from the go, ramp their sales to dealer/auction up to 20,000 per quarter (which is the current Wholesale run rate), building out that network in the process, and build a distribution network to manage the supply chain? I don’t know that number but I think its higher than $23 million.

For $23 million they get immediate inventory that can go to the soon-to-be launched consumer facing site, they get a built and operating distribution network for deliveries and dealer network, and they get to layer on their consumer cash offer business.  And yes they also get the dealer purchasing vertical that Wholesale excels at as well as a couple of retail locations.

Yes margins at Wholesale are really low, but it’s because they buy from dealers, refurbish and sell to auction/dealer. Wholesale seems to me to be essentially an arbiter.  But I don’t think RumbleOn bought Wholesale because they were enamored with this dealer to dealer business.

To put it another way, Wholesale also has an existing network and inventory that can be leveraged to more quickly build the higher margin consumer purchases and higher margin consumer sales that RumbleOn has always planned.  RumbleOn has the automated cash offer system to drive consumer purchases which will be better margins. They have their site/app/brand to drive consumer sales.

I think that looking at Wholesale’s business as-is or trying to think about how RumbleOn will improve Wholesale’s existing business is probably not paramount to how Chesrown and Berrard are thinking about it – yes, RumbleOn should be able to make incremental improvements on what Wholesale does through data analysis that improve decisions but that’s not the primary motive for the acqusition – the point is layering on the consumer online buy side with the cash offer model and consumer sales through the website, and leveraging Wholesale’s existing dealer network to maximize turns right from the start. Improvements to Wholesale’s existing business are peripheral to what they are really going for here in my opinion.

They said it multiple times on the call – RumbleOn is creating a supply side solution – they are demand side agnostic – consumer/dealer/auction – whatever. They need to be able to access each vertical and the more they can sell to consumer the better but unlike Carvana, Vroom, et al the focus is not sales to consumers. Its closer to the other way around – the focus is buying from consumers. They will sell whereever they can sell fastest to maximize turns. It’s the buy side that matter, procuring as much inventory from as possible from consumers while insuring it’s the right vehicle at the right price. If they get the buy side right the sell side sorts itself out. Wholesale fits nicely into this IMO.

So I like the acquisition. But I also think the logic behind it is complicated and I’m not totally sure the market will agree with me right away. I also think the quarter was not so good and you have to buy into management’s explanation to be okay with the results.  So we may get more pain. Nevertheless, I did buy back a position on Friday.

A couple other things

I bought back Smith-Micro after the earnings report.  I had said in my update that I was worried they would miss estimates.   They did, kind of. I could have sworn the Roth estimate (the only analyst) was $6.7 million of revenue for the quarter.  The company came in at $6.5 million. But when I looked after earnings it appears the estimate was actually $6.1 million.  So I don’t know if I imagined that $6.7 million number or whether Roth changed it at the last minute.

For what its worth it means they beat, but the stock fell anyway.  I didn’t think it was a bad quarter at all though.  Safe & Found adoption at Sprint continues at a steady pace, there are overtures of a second carrier in the next 6-9 months, and it appears that the sunset of the legacy product used by Sprint customers is coming.  These are all positives and really the only negative had to do with the peripheral Graphics business, which saw a steep revenue decline but is now at the point where it can’t hurt the company going forward.  So I bought.

Vicor stock action remains a gong-show.  I’m holding on (pretty much HODL at this point) and I did think their quarter was fine.  There is weakness in the legacy business but the new products bookings were up 20% sequentially, which is a great number.  Apparently there is a negative report or article on Vicor that has been out for a while that could be the basis for some short selling of the stock.  John Dillon mentioned it on SeekingAlpha.  If anyone has the report I’d really appreciate seeing it.