Skip to content

Copper stars not quite aligned

Sometimes all the stars align for a trade.  And sometimes there is one star that is way off in its own orbit, throwing off the whole picture.

That’s what I’m thinking about copper right now.

There is a lot I really like about this idea:

  1. The demand picture is premised on what seems like the inevitable adoption of electric vehicles and increasing electrical infrastructure
  2. The supply picture paints a scene of depleted reserves and an empty pipeline that will lead to significant deficits for years to come
  3. The prices of copper equities are reasonable, if not downright cheap, and certainly not pricing in the upside of a rising copper price

It all fits.  Except for one thing.  These damn tariffs.

In my opinion there are reasonable odds that what is to come is more brinkmanship, more anti-ups, and maybe even some sort of climatic event ala Nixon in 1971 that changes the way the world operates for good.

Of course maybe not.  The market is certainly saying its all good.  But the market also rose right after Nixon put a 10% surcharge on imports and pulled the rug out from under Bretton Woods.

The 70s didn’t really go all that well.

I don’t know what is going to happen.  But it’s uncharted territory and it wouldn’t surprise me if the market is as clueless as I am.

Consider the following:

  1. We have a President that was elected, in part, by folks who lost their jobs or had their communities disrupted by the relocation of industries that were allowed to leave because of free trade (yes its complicated and there were other causes, but free trade was definitely part of it).
  2. The President has made it clear he will do whatever it takes to make good on his promise to fight for these people and communities and get those jobs back (whether or not what he is doing is actually going to be in their best interests is not clear but also not really relevant to the line of reasoning here)
  3. It’s not really clear if anything can be done to turn back the clock on these cities, counties and communities that have had the industries they were built on stripped from them, so perhaps regardless of what the President does, the outcome will disappoint

Those 3 points suggest that it is at least possible that we spiral into a vicious circle of escalating actions that don’t have the intended effect and therefore lead to even more escalation.

I’m just not sure I want to own a lot of copper in that environment.

With that all said, the picture for copper supply and demand assuming a “steady as she goes” economy is pretty enticing.

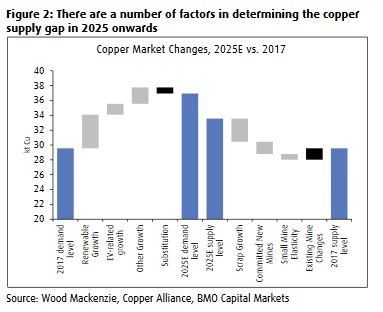
BMO put together a long and very interesting research piece describing the supply and demand dynamics of copper over the next number of years.

The demand side is being driven by electric vehicle demand and the grid infrastructure required to move to a higher amount of renewables.

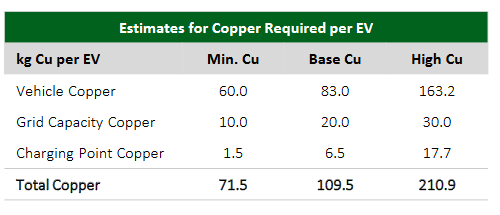
The simplest explanation of why this will increase the demand for copper is this: An internal combustion engine contains 23kg of copper for wiring, whereas a battery electric vehicle and plug-in hybrid contain between 60-83kg of copper.  On top of that another 20kg of copper is needed for grid capacity and 6.5kg for the charging point.

On the supply side, a combination of declining grade, rising capital costs and a number of years of depressed copper prices have left us with a depleted pipeline of projects.

The conclusion, which is hard to find fault with, is that there is a significant shortage of copper projects in the development pipeline and projects will only be added if the price of copper rises enough to incentivize them.

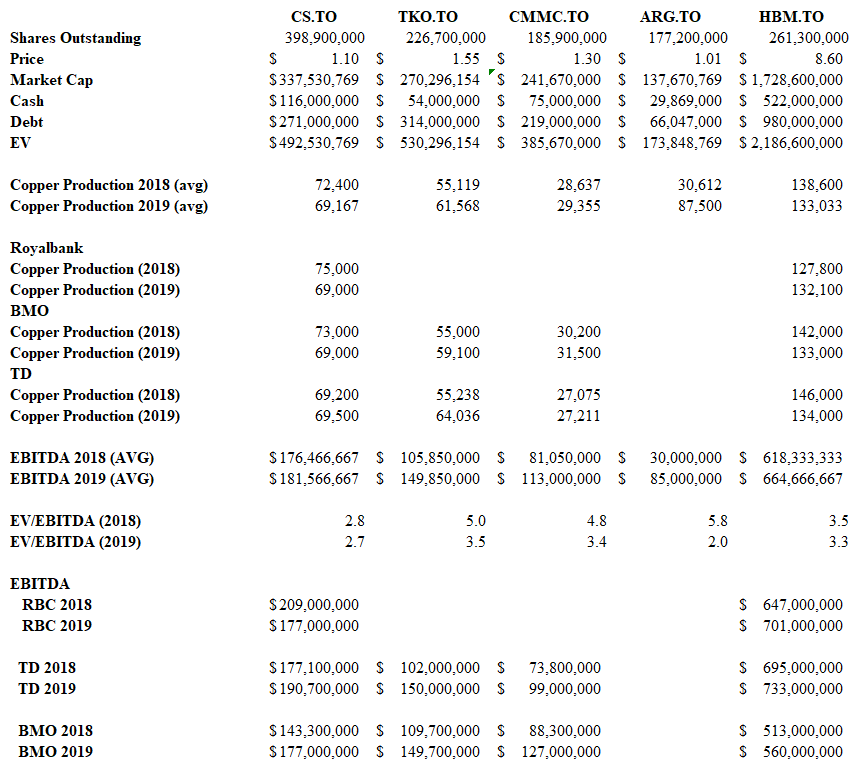
So how do you play this?  Well maybe you don’t because there is just so much risk in the world.  I’m still trying to figure that out.  But if you do, I certianly think the copper stocks are reasonably priced for it.  Below is a comparison of a few that I have dug into where I just took analyst EBITDA estimates and averaged them to get a rough idea of the EV/EBITDA multiple these companies trade at (note that because Amerigo isn’t followed by any brokerages I have reports for I used the companies own estimates that I found in their presentations).

At the moment I have taken positions in a couple: Copper Mountain and Capstone.  But these positions are really, really small (<<1% each).

For now they are going to stay that way.  I’m just too uneasy about where all this trade stuff is going.

Week 359: Buoyed by the CAD

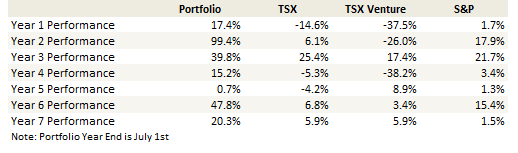
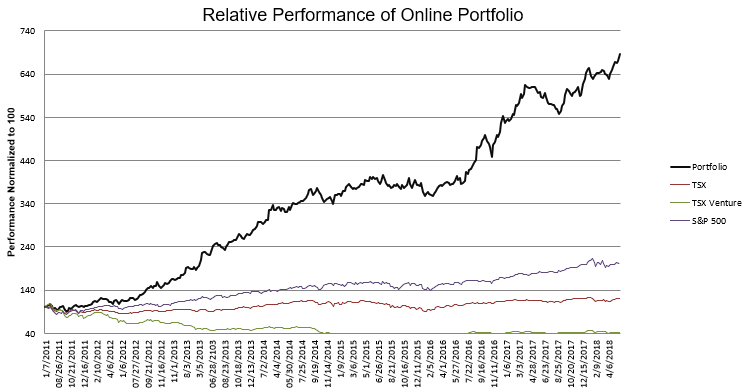
Portfolio Performance

Thoughts and Review

Another quiet month for my portfolio as I only added and subtracted a few stocks around the edges.  But I had quite a good month.

I can’t take credit for all of it however. I have been getting a boost from the Canadian dollar.  Since March the dollar has fallen from 81c to 77c.  Last spring I talked about this when I was going through a period of massive headwind from a rising Canadian dollar. Now it’s the opposite.

If you do the math, the move in the Canadian dollar has added about $25,000 to the tracking portfolio totals since the beginning of March.  So I’m looking somewhat better than I actually deserve (which is quite the opposite of last spring, when I looked like a schmuck as the CAD rose some 15% in a few months!).

Much of the rest of the move (which I can take credit for) is the move in Gran Colombia Gold.

Gran Colombia

In the last 5 weeks Gran Colombia completed the redemptions of their 2020 and 2024 debentures and announced first quarter results.    The results were great.  AISC of under $900/oz and EBITDA of $27 million.

After accounting for debentures redemptions and share conversions (including all the in-the-money warrants and the not yet converted 2018 debentures) I get about 60 million shares.  So that’s a market capitalization of about $200 million (CAD) or USD$153 million at the current conversion.  There is another USD$98 million of the new debt and they should have about USD$41 million of cash once all the warrants are converted.

The company did USD$27 million of EBITDA in the first quarter.  It seems pretty reasonable that they should do at least USD$100 million of EBITDA in the full year.  So even after the big jump in the stock price, Gran Colombia only trades at 2x EBITDA.  I realize the gold stocks are cheap and unwanted, but even the most unloved get at least 3x EBITDA and some are getting 6-7x.

I think the re-valuation still has a ways to go.

Tornado Hydrovac

Here’s a stock I haven’t talked about in a while.  I took a closer look at it after the first quarter results and had someone on Twitter ask about it which got me thinking about the stock a bit more.

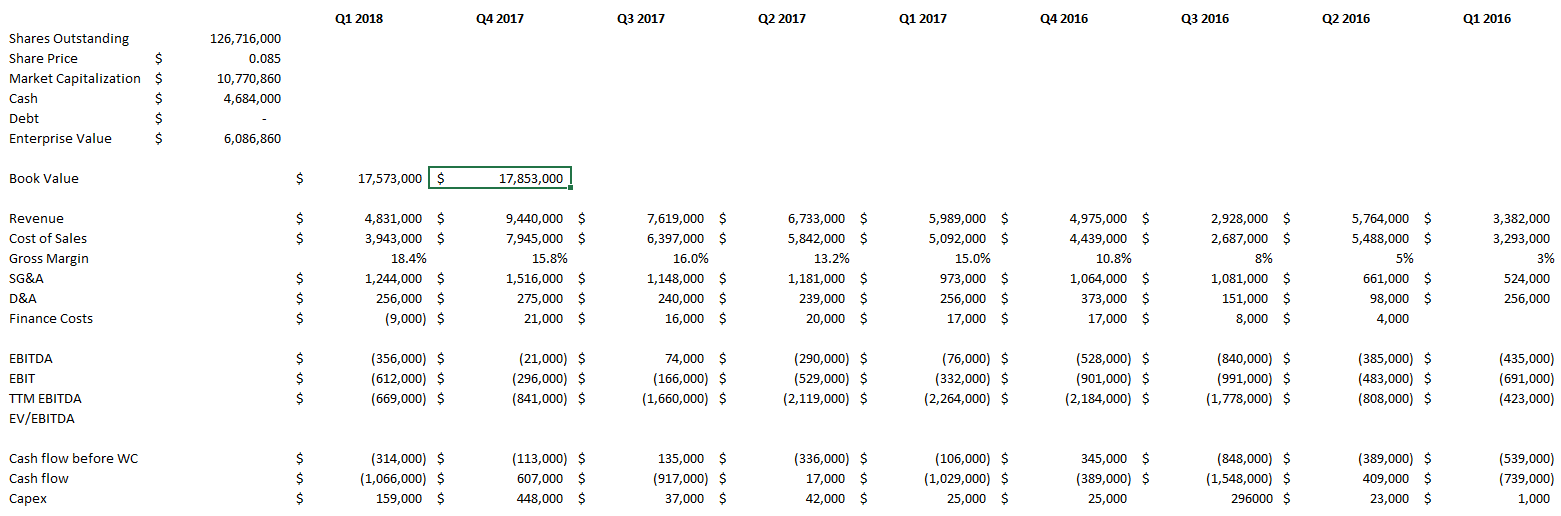
Tornado is a $6 million enterprise value company with almost $5 million of cash.  However, most of the cash ($3+ million) is in China and not readily available for the North American business.  They have an established hydrovac business in North America, and one they are trying to get off the ground in China.

These are the same trucks that Badger Daylighting rents out.  But Tornado’s business is not quite like Badger, as they are primarily building the trucks not renting them out.  Tornado has had a few rentals (1-4 trucks per quarter) over the past year, so its not a significant business.

The first quarter wasn’t great.  I had been hoping for a follow-up on the fourth quarter, where revenue hit a 3+ year high at $9.4 million.  But they only had $4.8 million of revenue in Q1.

So it was disappointing and the stock hasn’t really done much.   But to be fair, the stock has never really done much so let’s not read into that too much.  Still I’m inclined to think the business is turning for the better.

The poor results were partially seasonal – in 2014, 2015, and 2016, there was a significant slip in first quarter revenue from Q4 to Q1 (2017 was a bit of an anomaly because the industry was recovering from the downturn).

Also, inventory ticked up from $6.49 million in Q4 to $9.1 million in Q1.  Inventory has been a pretty good indicator of the next quarter revenue, which I imagine is because of the part procurement and build cycle.  The company said the following in the MD&A.

For the three months ended March 31, 2018, inventory was $9,072 compared to inventory of $6,490 as at December 31, 2017.  The increase in raw materials is due to stocking up for production ramp-up in the second quarter.  The increase in finished goods is due to 3 completed trucks held in finished goods as at March 31, 2018 that were not delivered and sold to customers until early Q2 2018.

The other angle with the company is China.  They are getting closer to generating revenue from China.  Tornado expanded into China over a year ago.  Since that time most of the efforts have been establishing a footprint, starting up a manufacturing operation and developing relationships.

In the first quarter they sent out their first three demonstration units in China.  Overall, China has overhead of $300,000 per quarter and no revenue.

The inventory related to the three demo units was $1.14 million.  Assuming 15% gross margins (margins for the company are around this level), they need to sell about 5 trucks per quarter in China to break even.

But that’s only assuming sales of trucks.  The model is China is both sales and services and I’m not sure about what the economics of the services side will look like.

Bottom line is that the stock is reasonable and I think its not a bad bet that they can have a breakout quarter one of these days.   Book value is over $17 million while the enterprise value is $6 million.

On the other hand, margins are super-thin and the operating history isn’t exactly stellar.  This remains a pretty small position for me, but an interesting one and one worth reviewing from time to time.

Oil Stock sales

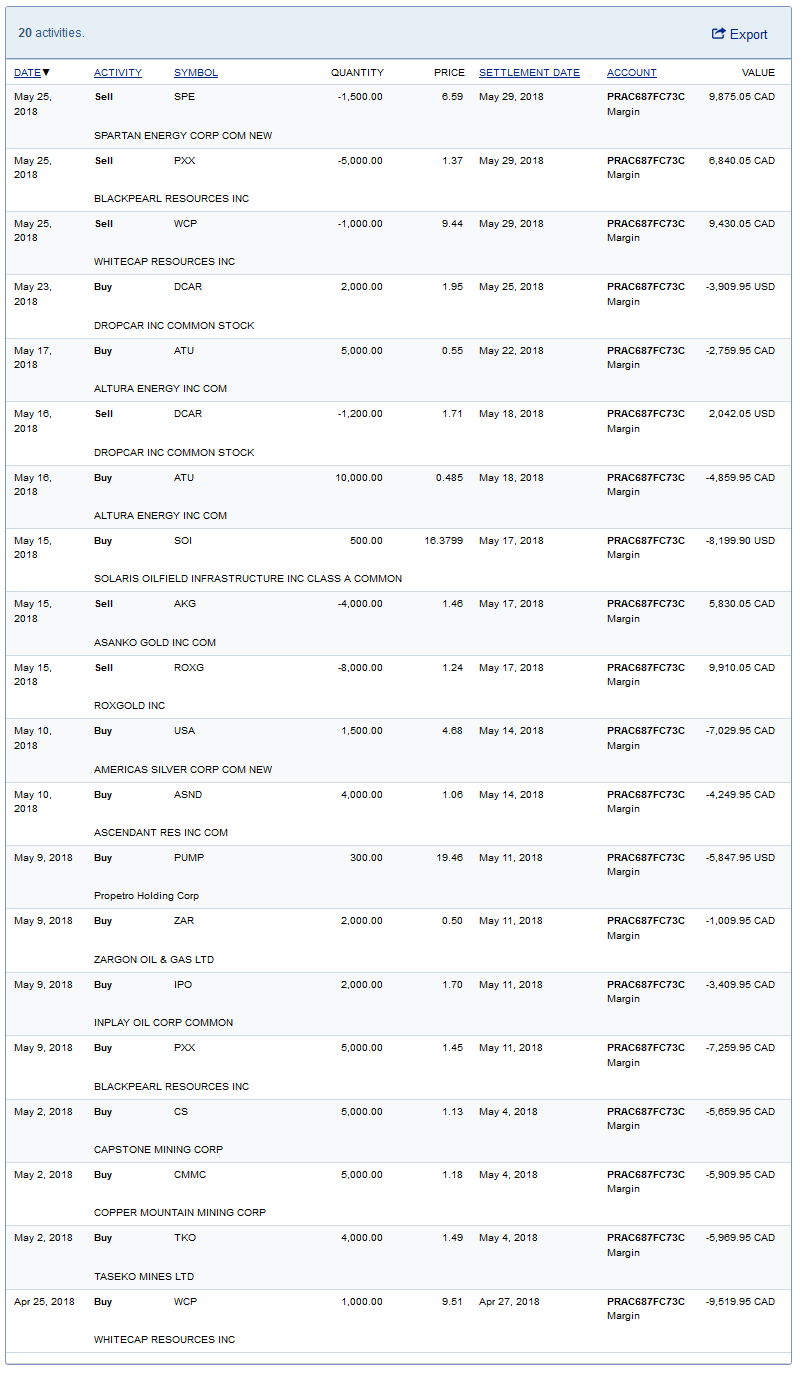
I sold out of a few oil stocks last week.  I can’t say that I had foresight into the carnage.  A lot of my selling was done on Friday, so after the plunge had occurred.  I sold Black Pearl, Whitecap and Spartan.

I have to admit, having missed a better opportunity to lighten up earlier in the week, I was a bit reluctant to do so after these stocks sold off.  Nevertheless I had a couple of reasons that led me to decide to sell anyways.

First, I was just getting a little too overweight into oil.  In particular, I took on a big position in Altura, which I wrote about, and hadn’t really sold anything.

I was getting particularly uncomfortable with my exposure to heavy oil.  The Western Canadian Spreads are looking good but I was long Gear, Zargon, Black Pearl, and now Altura.  It was a bit too much exposure.

Spartan was really now a bet on Vermillion and I don’t really know enough about Vermillion to want to take a position there.

Whitecap was just because I was nervous about Canada and Transmountain.   I know Whitecap isn’t heavy oil so maybe my logic doesn’t string together that well, but I didn’t want to sell Gear, Zargon or Altura and yet wanted to get my Canadian exposure down a bit more, so there you have it.

The other consideration I weighed was the build in crude last week.  It was a surprise, to say the least.  It could be a one-off and there seem to be indications that this week will look much better.  My thought was that the crappy number last week puts a lot of pressure on this weeks numbers.   What if, for whatever reason, its another surprise build?

With the Trans-mountain decision out of the way I might look at buying some of these names back.  But I think I will wait until after the Thursday numbers (delayed a day because of Memorial day) come out before doing anything.

Solaris Infrastructure

My services companies aren’t doing that well.  Cathedral has been terrible, down to almost $1.20 and if it goes much lower its going to hit the 52-week lows of when oil was $20 less.  I already gave up on Essential Energy.  Energy Services of America is always a next quarter story.

The problem is that none of these service companies can seem to generate any gross margins.

One story that is not a problem for is Solaris Infrastructure, where gross margins are a pretty amazing 60%.  But the stock is suffering nearly as much as these other names anyways.

Solaris provides a last mile solution for storing and delivering frac sand.  They don’t actually sell sand.   They rent out silos and conveyor systems that are installed on the well site and act as a sand buffer during the completion process.

The silo solution seems like it’s a big improvement over the Sand King trucks that are typically used.  Costs are lower, trucks don’t have to sit and wait, and the footprint on the well site is smaller.

Solaris builds the silo units and rents them out on a monthly basis.  The gross margins are as high as they are because of the rental model of the business.

Solaris is growing like crazy.  Revenue grew at over 205% in 2017.

Here’s my back of the napkin math for a theoretical 2018 exit.  At the end of the first quarter they had 98 systems in operation.  On May 9th, the date of the conference call they had 108.  They are adding systems at 8 per month.

So lets say they have 170 systems at year end.   Solaris gets roughly $100k per month of rental revenue per system so that works out to $204 million of annualized revenue.

There is no reason to think they don’t maintain their EBITDA margin of 60%, which would mean they are annualizing $122 million of EBITDA by year end.

In the first quarter they had $3.2 million of depreciation on an average of roughly 90 systems in operation during the first quarter.  That works out to $142,000 D&A per system or on 170 systems $24 million annually.

There is no debt so that means income before tax is $98 million and after tax is $77 million at a 21% tax rate.   On 47mm shares that would be $1.63 EPS.

If I assume they slow down their build to 6 systems per month in 2019, I get EBITDA of close to $180 million and EPS over $2.50.

None of this includes their new sand terminal in Kingfisher.  Or their sand supply chain management tool Propview.

There are a lot of things I like about Solaris but the one thing that I don’t like, that actually gives me a lot of pause, is the stock performance.  It is such a good environment for oil stocks and here is a fast growing service company right in the middle of it. And the stock price is as dumpy as can be.

That makes me think that maybe I’m wrong about it.  I’m hoping the market is just slow to jump on board, but its also possible that I’m too optimistic.  Maybe margins will decline and growth vanish as competition comes on the scene.  I have to think that’s what the market is worrying about.  Because otherwise the current share price doesn’t make a lot of sense.

One last Buy

The last thing I did was buy a small position in 3 copper stocks.  I’m not quite ready to talk about these, meaning I’m not sure I should have bought these stocks or not yet.  So I’ll leave that for now.

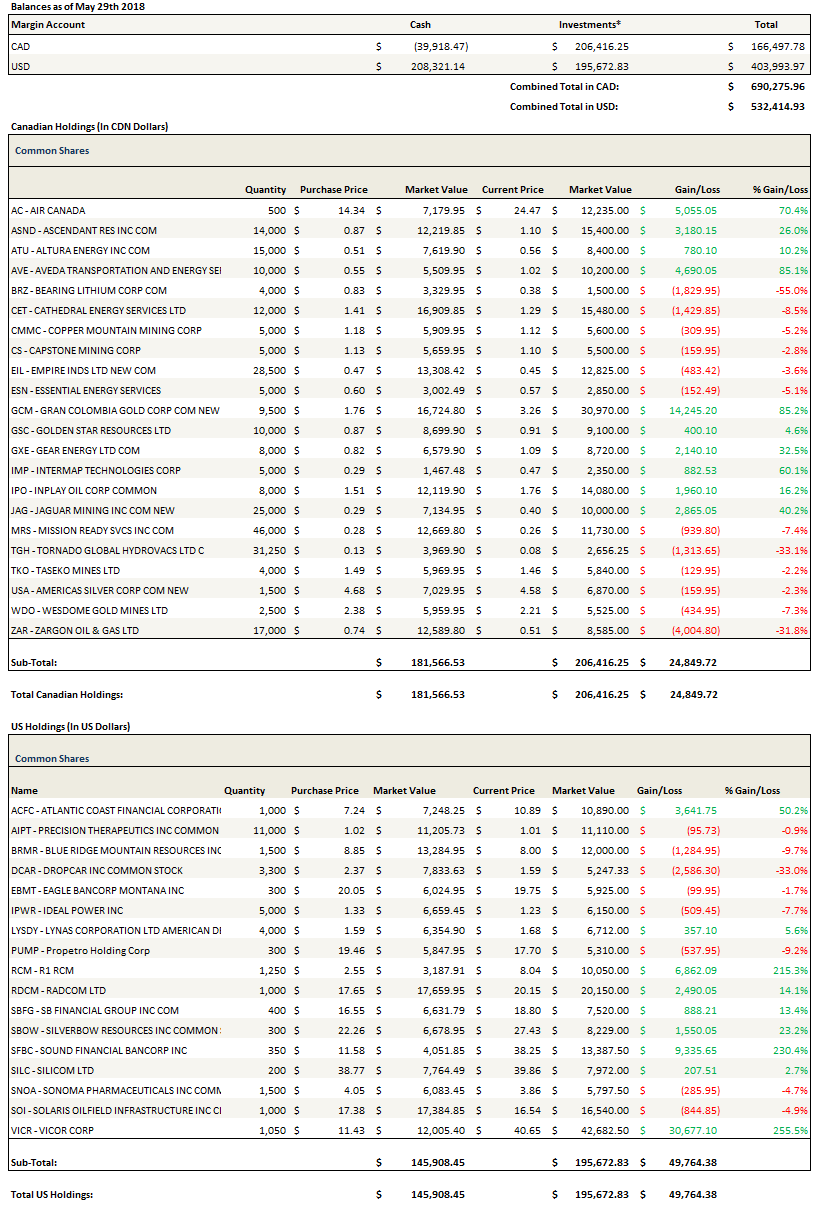
Portfolio Composition

Click here for the last five weeks of trades.

A Game Changing Disposition for Altura

I mentioned Altura last week in a comparison table I made to Zargon and Gear Energy.   As I noted in the comments, I had a position in the stock in another portfolio (my RRSP and my wife’s account) but not in the portfolio I track online so I haven’t talked about the stock outside of that reference.

Well that changed today.  I added to the stock in all my portfolios even though I was getting it up 20% on the day.

I want to give a big hat tip to @BrownMarubozu for bringing my attention to Altura a month or so ago.

Altura announced first quarter results after the market closed last night.  The results were fine, maybe a little weaker then expected actually, but the real news was the announcement of the sales of their Eye Hill, Macklin, Wildmere, Killam and Provost Minor assets.

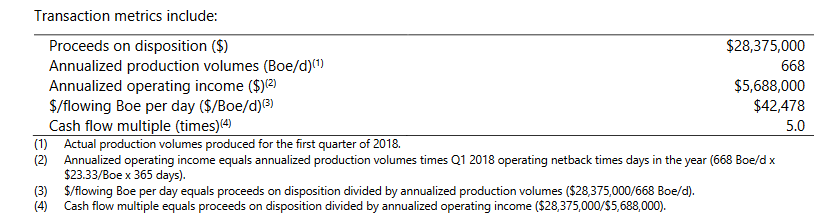
Altura sold the assets to Surge Energy (here’s their press release on the transaction.  The transaction metrics the company provided are below:

The sale of these assets leaves Altura with about $20 million of cash and no debt.  With the rest of their properties sold off, they are a pure play on their remaining asset: Leduc-Woodbend.

Leduc-Woodbend

They are going after the Upper Mannville formation at Leduc-Woodbend, which is about 1,300 meters deep.  They have amassed 65 sections (41,000 acres) in the area, with 40,000 of those acres considered undeveloped.  The formation produces 17° API heavy oil.

The Leduc oilfield has been around forever and is a well drilled out area using conventional vertical wells.  Given that its not a new area (Altura themselves says there are over 700 vertical wells in the area) I’m not sure if Altura discovered something new here or whether this was a previously uneconomic pool for vertical wells that is now being unlocked by better technology.  At any rate Altura described the pool as “one of the largest conventional oil pools identified in the Western Canadian Sedimentary Basin within the last 20 years” in their initial press release on the prospect.

This is early in the game in Leduc-Woodbend.   They have only drilled 5 wells in the property so far.  But these wells look quite good.

They started drilling into the Mannville formation in early 2016.  The first well, the 13-15 (see the map below), produced 230 boe/d over the first 30 days and was producing 160 boe/d after 5 and a half months.  It was producing 70 boe/d in July, after 8 months of production (from this news release).

The 13-15 was a one-mile horizontal and cost $1.7 million to drill and complete.

Their second well, the 12-15, was another one mile lateral drilled at the beginning of 2017 and place on production in April 2017.  This well was a full 6 sections north of the initial discovery well but production was inline with the 13-15 (this press release).

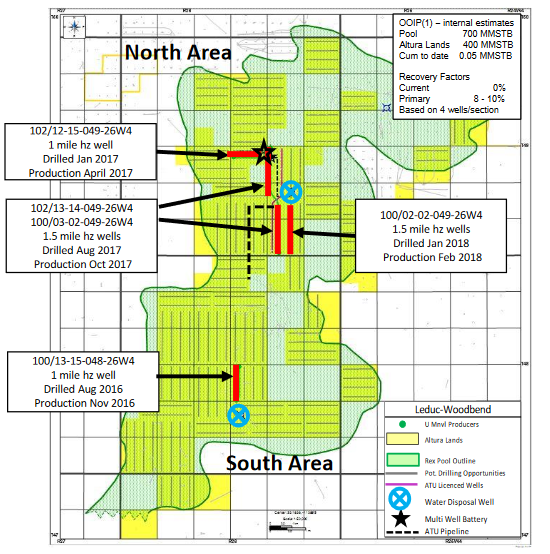
You can get an idea of how far apart these wells are in the map below (the 13-15 is the well furthest to the south while the 12-15 is the northern most well).

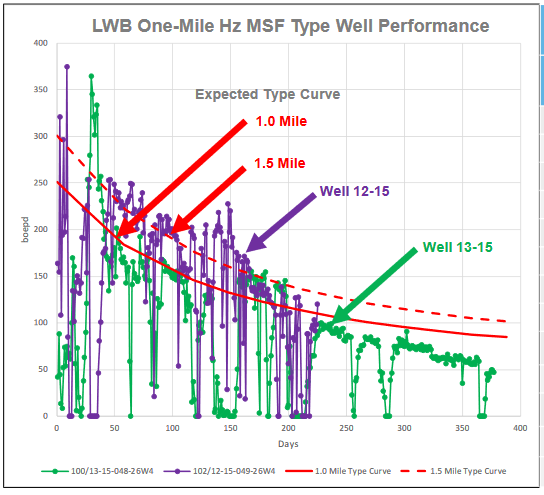
In their November presentation Altura detailed a reasonably steady decline profile from both wells (they are both one mile laterals):

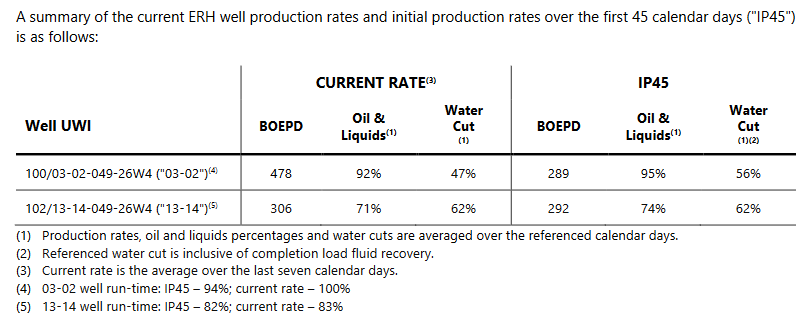
Since the beginning of the third quarter Altura has followed up with 3 more longer wells, 1.5 mile extended reach horizontals (ERH).  The first two (03-02 and 13-14) were placed on production in October (from this press release).

The third ERH well (02-02) was drilled in January and placed on production in February.  This well averaged 334 boe/d in the first 26 days of production (from this press release).

In the May 15th release the company said the well had produced 10,626 bbl of oil in the first 45 days, which equates to a 236 bbl/d average before being shut in for a month to replace a broken rod.

The company went on to say that they expected 150-175 boe/d over the first 12 months for all 3 of the ERH wells.

My takeaway from all this well data is that the results are consistent.   We only have 5 data points but so far the repeatability looks excellent.  Its particularly exciting that the original discovery well is so far away from the others and yet has yielded comparable results.

I was cautiously optimistic about Leduc before the quarterly release but the numbers presented have added to my confidence.

Guidance

The company obviously has confidence.  In addition to focusing entirely on Leduc they raised guidance significantly even after divesting over half their production.

Right now Altura is producing around 550 boe/d from Leduc, 80% oil.  They expect to exit the year at 1,900 boe/d.

To do this they are increasing their capital budget from $15 million to $33 million and expanding to an 8 well program.  So the cash they are getting on this transaction will be put to use drilling out Leduc.

Based on their presentation it looks like the wells cost $2.65 to drill, complete and tie-in.  They also spent $7.3 million already in the first quarter.  That means the company is spending roughly $7 million on infrastructure at Leduc.

The infrastructure money is going towards a larger oil battery.  They are increasing the size of their oil battery to 3,000 – 3,500 bbl/d.  So that gives you an idea of where they are expecting to take the property to.

They seem undervalued to me

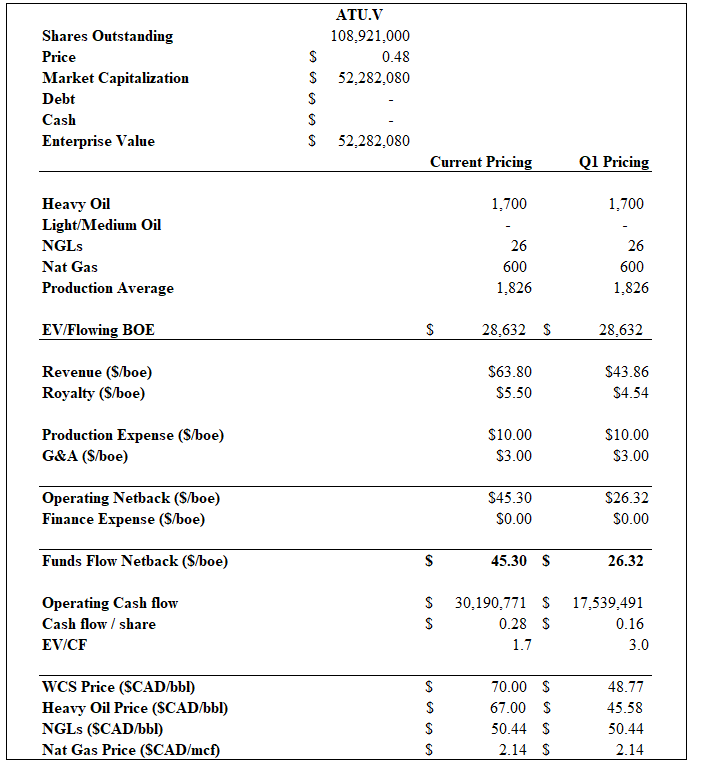
When I forecast ahead at what Altura looks like at year end using the company’s guidance, it looks cheap to me on most metrics.

Here are my estimates of cash flow and EV/CF using their guidance.  I am assuming they use all the cash to complete the drill program which should be conservative.  I looked at two scenarios:  A WCS price consistent with the first quarter (so a low price) and the current WCS price (a high price).

Apart from the valuation, what’s interesting is that at roughly $70/bbl WCS, Altura can cash flow $30 million based on their exit volumes.  So they should be able to fund a similar sized capital program in 2019 (actually a bit higher because they wouldn’t be building an oil battery) without adding at all to debt.  If they get similar production growth from that budget (based on exit guidance growth in 2018 is 1,250 boe/d), they’d grow over 60% and be producing over 3,000 boe/d by the end of 2019.

Considering that sort of growth runway, the company seems extremely cheap to me.  The risk of course is whether the oil price holds up and whether they can meet their target.

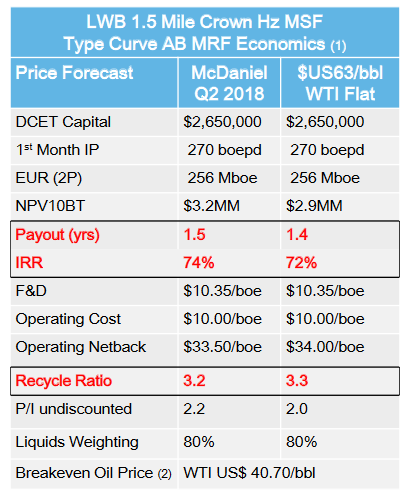
It’s still early days so we’ll have to see.  The economics that they present for these wells is impressive.

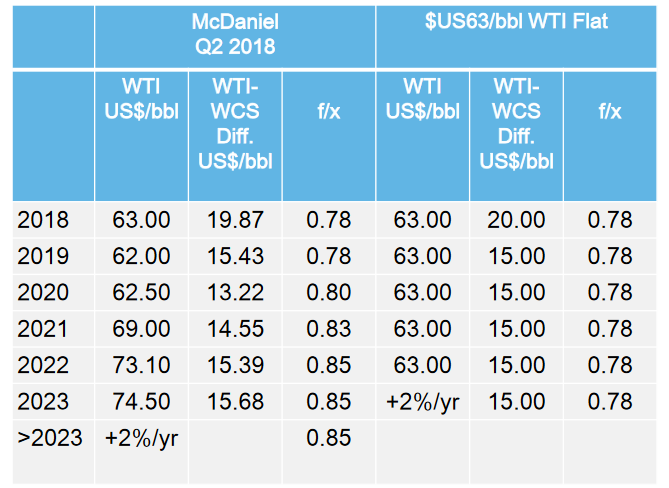
The wells have IRRs of close to 75%, which is pretty good.  But it looks even better when you notice the price forecast these are based on:

They are essentially using $55 WCS prices for 2018, followed by $61 for 2019 forward.  At last look WCS stood at $74/bbl.

Conclusion

One question that might be asked is why the stock didn’t move even more?  One answer is that I’m totally missing something.  Maybe, but I don’t think so.  Another is that the market isn’t going to de-risk Leduc until they drill more wells.  That definitely accounts for some of it.

A third reason has to do with liquidity.  I know that one of the reasons I didn’t buy more Altura before today was because it was so hard to buy.  The share volumes were anemic and it seemed like my bids would sit for days some times before getting bought up.  The Level 2 liquidity was usually equally sparse and it seemed like I would quickly move the price up to 44c or higher if I bought too much.

With that in mind I wonder how many sellers today are just liquidity sellers.   This is a liquidity event, lots of volume, so it’s a chance to unload shares.  If you have a very big position, you probably want to take some off.

Whatever the reason I took advantage of the volume and bought a decent position.  I’m looking forward to the next operations update.


Sticking with Zargon

I have owned Zargon Oil and Gas for almost two years now and it has been one of my worst performers.  I bought a small position after the company announced the sale of its South Saskatchewan asset in July 2016.  I added to the stock early in 2017 after the company announced a redemption auction for its convertible debentures whereby they would either redeem the debentures in full or exchange them for longer dated (December, 2019) lower strike ($1.25 per share) debentures.

Neither of those purchases have worked out so far.  I thought the asset sale would reduce debt and bring back interest in the stock.  I thought the debenture exchange would be a catalyst.  Maybe most importantly I thought the environment for oil stocks was improving, so it seemed a reasonable bet that Zargon would benefit.

As it turned out I was about a year too early. The stock languished through much of 2017, falling from 80c to under 40c at one point.

Why Zargon?

Zargon is not my biggest oil position. It’s one of a basket of stocks I have been holding and adding to.  In the last few days I added Black Pearl Resources and ProPetro Holdings to that list.

So why am I choosing to write about Zargon and not my other larger holdings?  Well for one, apart from a few Seeking Alpha articles Zargon doesn’t get much attention.  I could write about Whitecap or Gear Energy but you can get all the information you need from brokerages reports already.

Second. with the prospects for oil improving I decided to really dig into Zargon again a couple weeks ago.  The stock has under-performed for so long and I wanted to come to a conclusion as to whether to keep holding the stock or move those dollars into another E&P.

I decided to stick with Zargon.  Here’s why.

Zargon operates 3 assets.  They produce about 500 bbl/d from their Little Bow enhanced recovery project, another 300 bbl/d of conventional heavy oil at Little Bow, about 400 bbl/d of medium/heavy oil from North Dakota, and another 1,200 boepd from various assets around Alberta.

Little Bow ASP

The Little Bow asset would be considered Zargon’s flag ship.    The company produces 20-21° API oil from the Mannville formation at Little Bow, Some of this production is conventional, and some of it is an advanced waterflood technique called Alkali-Surfactant-Polymer (ASP) recovery.

An ASP is a waterflood recovery where the additional “A-S-P” chemicals are added to the water.  The chemicals thicken the water and turn the oil into a more mobile foam.  Together the thickened water and thinned oil mean that the oil moves more effectively than a traditional waterflood alone.

The problem with an ASP flood is that it’s expensive. The chemical costs alone are $6-$8/bbl.  Zargon has corporate operating costs of $20/bbl and while they don’t break out the cost of the ASP, I am certain its around the same level.  When oil was extremely low in 2016 Zargon suspended Alkali and Surfactant injections at Little Bow and shut in higher water cut producers.
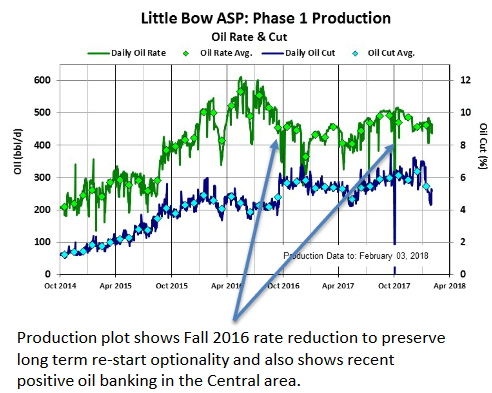
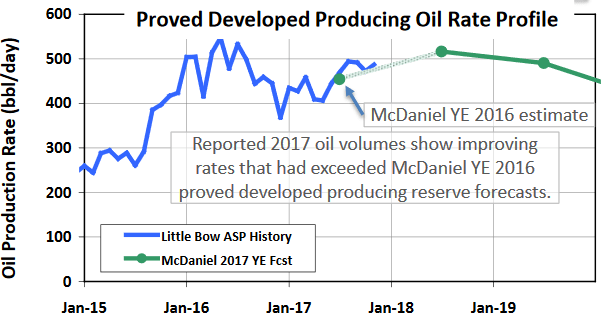
The good news is that ASP at Little Bow is long life and has a low decline.  Zargon has examples in its presentation of a Husky Taber ASP waterflood and Gull Lake ASP waterflood where production has been fairly close to flat for 10 years and counting.  Proved reserves for the Little Bow ASP were a little under 2mmbbl and proved plus probable (which includes the yet to be developed Phase 2) is 3.9mmbbl.  At 500bblpd this is 11 year reserve life index for proved and 21 years for proved plus probable. In their 2017 reserve report McDaniel is forecasting an increase in production in 2018 as Zargon reinstates the full ASP flood and brings back on previously shut-in wells.
Little Bow Conventional

Zargon also has conventional oil production at Little Bow.   This is from the “G” and “U” units in the map below.
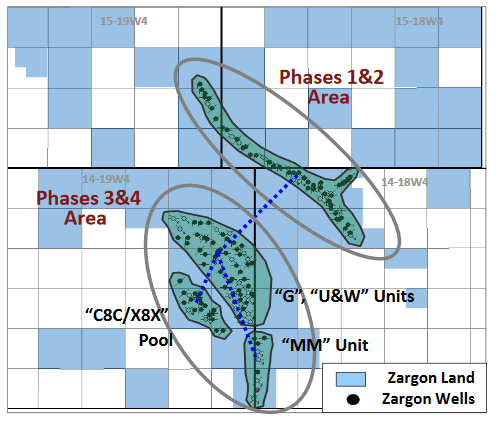
Both the G and UW units are targeted as Phase 3 and Phase 4 stages of the ASP development.  But for now the land is produced conventionally.

Together these pools produced 285boepd in 2017, 65% liquids.  The company doesn’t list additional locations anywhere that I can see, so I have to assume this asset is going to continue to decline until the ASP flood is implemented.

Bellshill Lake

Zargon owns 21.5 sections (13,760 acres) of land at Bellshill Lake.  Bellshill Lake is in East-Central Alberta, very close to Hardisty.  They produce out of the Dina sands formation there.
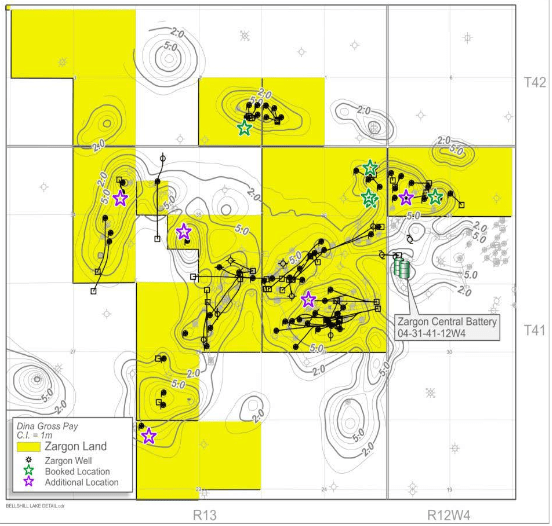
Bellshill Lake produced 409 boepd, 94% oil in the fourth quarter.  Bellshill oil has an API gravity of 27°API, so its firmly in the medium oil category.

This is another low decline property.  Based on the McDaniel decline (below) it looks like the decline on the field is 10-11%.   According to the company the area has aquifer support, which helps support the low decline.

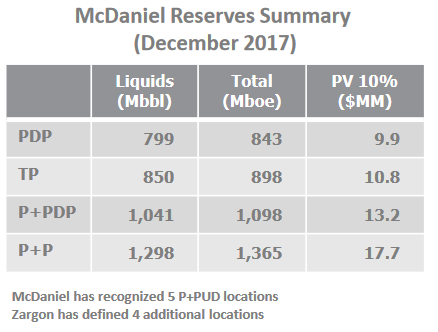
Zargon hasn’t drilled the property since 2014.  The McDaniel reserve report booked 5 undeveloped locations and Zargon says they have 4 more.  I believe these are all vertical locations.  In the fourth quarter Zargon expanded the water handling at Bellshill Lake which will allow multiple “low risk, low cost well pumping optimization projects” in 2018.

Its worth pointing out that before the collapse of the price of oil in late-2014 Zargon was able to keep production at Bellshill relatively flat at 550-600 bbl/d.
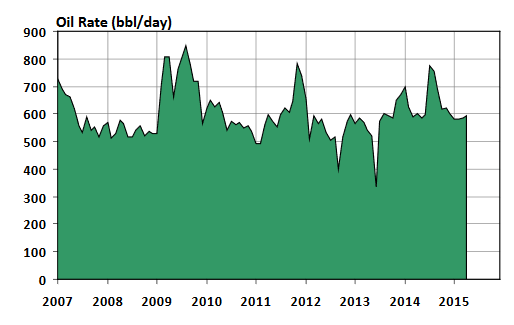
Proved reserves on the property are 850,000 bbl of oil.
Taber

It looks like Zargon has about 90 sections of land (57,600 acres) about 30km south of the town of Taber.  I say “it looks” because I’m counting sections of the map so I might be off give or take.

Zargon produces from a part of the lower Mannville Group called the Sunburst Sand.  There are two pools that they are producing from, North and South.  Both these pools are receiving pressure maintenance from waterflood.

The North Pool has a little ligher oil, 20 API, then the South at 16 API so again this is heavy oil.  Both these pools are fairly mature, having produced over 50% of the expected ultimate recovery.
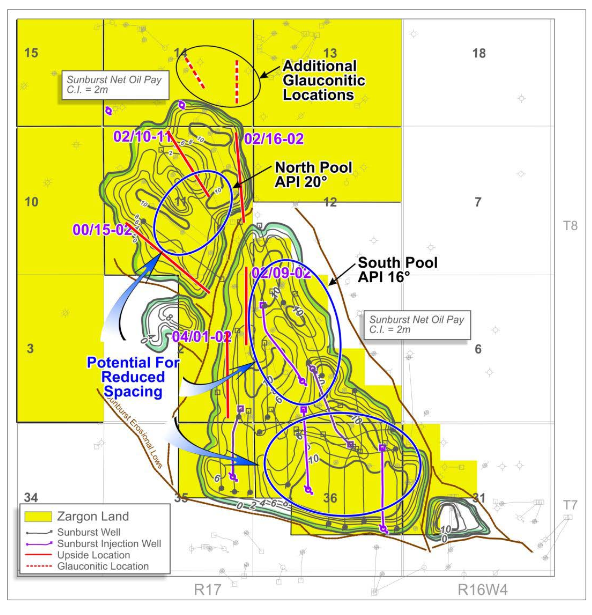
Zargon has drilled 30 wells into these pools since 2007, of which 5 are injectors.   McDaniel has 3 more horizontal locations booked and Zargon has an additional 5 they have identified.  I don’t believe they have drilled any wells here since 2014.  They have also identified a Glauconite oil pool north of Sunburst.

Taber South is another low decline property.  Based on the McDaniel estimate it looks like the decline is around 13%.
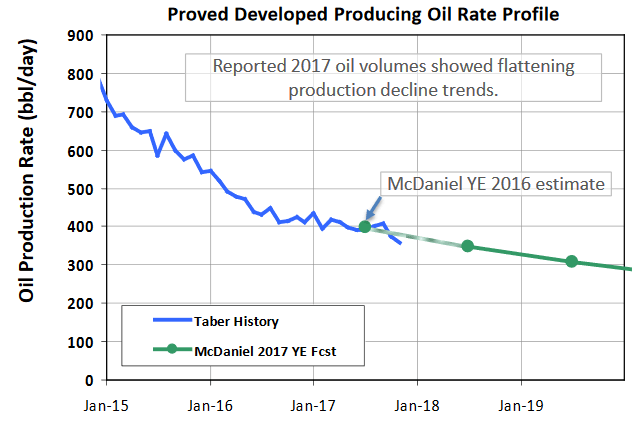
Proved reserves at Taber South stand at 1,144mbbl.

North Dakota

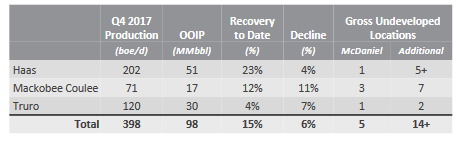
Zargon owns a scatter of land across Haas County, Truro County and Mackobee Coulee County in North Dakota.  This was originally part of a larger land package that extended into Saskatchewan, but the Saskatchewan portion was sold in July 2016.

This isn’t Bakken land.  I believe the focus on these lands is the Mississippian but I’m not sure which others are contributing.  They have 97% working interest in 18.78 sections (12,000 acres) of land.

They produce about 400 boe/d from North Dakota.  These are low initial rate, low decline wells.
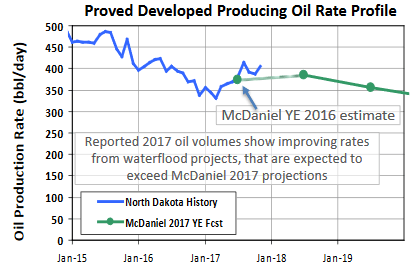
The decline on existing production is very low, varying between 11% at Mackobee Coulee to only 4% at Haas.
Strategic Initiatives

Zargon initiated a strategic alternatives process in August 2015.  Since that time they have sold the Saskatchewan assets for a pretty good price (at the time) but not done much else.

To be fair, that was perhaps the best choice.  I’m sure that the value of their assets has risen significantly in the marketplace over the past few months.  Even if the stock market doesn’t agree.

With the value of the assets rising, part of my expectation is that we start to see asset sales.

I don’t have many good analogies for the North Dakota assets.  I searched but I didn’t see any sales in Bottineau county.  In September 2017 Halcon Resources sold non-operated Williston Basin assets for $104 million of cash for $45,000 per flowing boe.  But this acreage is in Montrail, Mckenzie and Williams county, and prospective for the Bakken, so I doubt its analogous.

With such low decline base production and a land package that can support more drilling I would think that the North Dakota assets should fetch at least $40,000 per flowing boe in the current environment.  There are plenty of cases of oil assets in general selling for more than this (like the Cardinal purchase from Crescent Point of South Saskatchewan assets for $64,000 per flowing boe which I realize is not a great comparison).

If they can get $40,000 per flowing boe, that would be $20.5 million Canadian.

It might be worth noting (it also might not) that the company took down their February corporate presentation a number of weeks ago and has yet to replace it.

Paying off the Debentures

After the conclusion of the debenture redemption auction Zargon has $42 million left outstanding.  These debentures pay 8% interest (works out to $3.68/boe) and mature at the end of 2019.

The need to work a deal for these debentures in the next year and a half make me think that asset sales are probable.  The North Dakota assets seem like the most likely target.

I think these debentures are a real overhang on the stock.  Zargon has over $40 million of debt but only a $15 million market capitalization.

Paying off a significant portion of the debentures would go a long way towards improving market confidence.

Heavy Oil

A big knock against Zargon is that they are a heavy oil producer in Alberta.  And they are small.  This makes them vulnerable to the swings in Western Canadian Select (WCS) pricing.

It’s also going to hurt their first quarter results.  I am braced for a bad first quarter.  WCS spreads were huge, which means the price that Zargon got for its heavy oil was not very much.  To make it worse, Zargon seems to have hedged WTI on 1,000 bbl/d in the first half but not the spreads.

So it’s something to consider when trying to time a purchase.  On the other hand it should be well known at this point, and spreads have come in dramatically in April.

In fact I’ve been doing some work on heavy oil and drawn some interesting conclusions.  While pipelines are by far the best way to transport oil, rail cars are not a death knell to the industry.  According to an RBC report that came out a few weeks ago, rail transportation costs are $11-$15/bbl whereas pipelines are $8-$9/bbl.   That’s high, but its not crazy, “I have to shut-in my production and go home” high.  Especially at crude prices like what we are seeing now.

In fact with the Canadian dollar at 77c USD or whatever it is at today, these Canadian heavy oil producers are probably doing better now then they were the last time oil was this high, when the CAD was closer to 90c.

The pipeline story gets so much attention that these details get lost.  It made me rethink things, and made me add another heavy oil producer in Black Pearl in addition to Zargon and Gear.

Cheap compared to its peers

The other consideration that made me decide to stick with Zargon is that its quite cheap.  Especially if oil prices can stay at these levels.

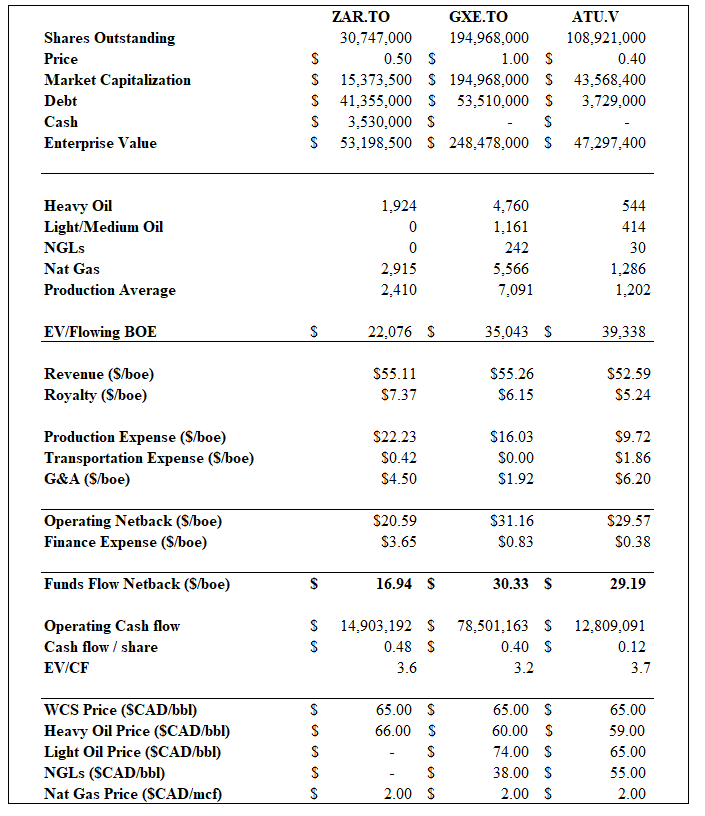
I am comparing the stock to two relatively close peers, Gear Energy and Altura Energy.  Neither of these stocks could be considered expensive in its own right.  In fact Gear is owned and touted by a number of funds as a cheap way of playing oil.  GMP recently listed Gear and Altura as two of their cheapest names.  I chose Altura because it does get brokerage coverage and because its roughly the same size as Zargon.

Now for the first half of 2018 Zargon is partially hedged at lower WTI and with no corresponding hedge on WCS spread.  So first half results are not going to look nearly as good as this comparison.

But come the second half of the year, if oil prices and spreads hold, things should work out to about this level.

Yet Zargon appears pretty favorably, even cheaper than these two.  The comparison below is at $65 WCS, so roughly $10/bbl higher than the fourth quarter.  Costs are based on the fourth quarter costs of each company.  I also estimated spreads off of heavy and light oil off of their fourth quarter pricing and for NGL pricing for Gear and Altura I just added $10/bbl to their fourth quarter pricing.  I might be wrong with the royalties, I added $3 to the fourth quarter royalty because I didn’t want to dig into the complicated calculation of figuring out how it escalated with price.
Based on proved reserves and net asset value again Zargon looks pretty good.
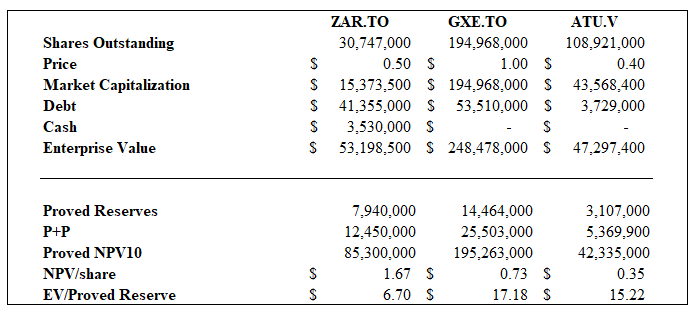
Looking at cash flow, on an EV basis Zargon is comparable to Gear and Altura.  On a per share basis, Zargon has a lot more torque.  In fact they trade at about 1x P/CF on these price assumptions.  On a reserve basis Zargon is very favorable, trading well under the value of its proved reserves.
The discount was justified when oil prices were low.  Just look at the operating costs to see that Zargon is by far the higher cost producer.  But if we really believe in these oil prices, I think you can make the argument that it’s time to peel it off.

Conclusion

Look I realize Zargon’s assets are not best in class.  They are high cost operating assets mostly in land locked Alberta.

They are also extremely profitable at current oil prices.  At $65 WCS the stock is trading at 1x cash flow.

Zargon spent $8.9 million on capital expenditures in 2017.  On those expenditures they kept production pretty much flat (in the fourth quarter of 2016, after the sale of the South Saskatchewan assets, production averaged 2,449 boe/d).  In the AIF McDaniel estimated $6.4 million in capex in 2018 in their proved reserves NPV calculation.

With cash flow of nearly $15 million (once the hedges in the first half run off) at $65 WCS, that works out to somewhere between $6-$8 million of free cash flow on a market capitalization of $13 million.

I decided that was worth sticking with.  I actually even added a little more.