Skip to content

Week 131: Flat on my Back

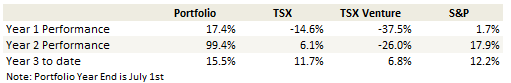
Portfolio Performance
yoyperformance

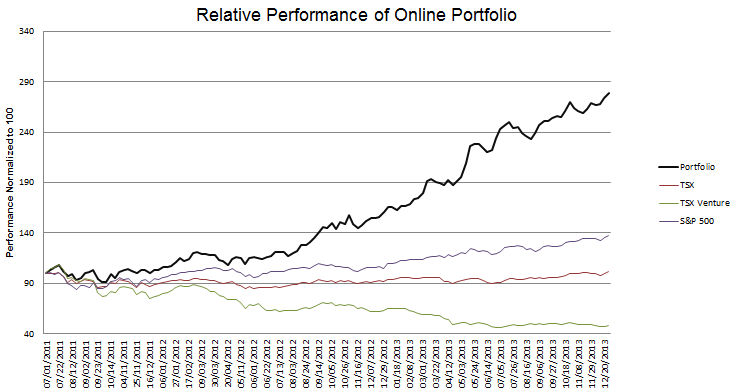
See the end of the post for the current make up of my portfolio and the last four weeks of trades.
week-131-Performance

Recent Developments

Its been a very quiet month and you can count the number of trades that I made on both hands.  I was away for some time, there were holidays, and I was laid up with back problems for over a week.

Being laid up and not able to do much of anything reminded me of the importance of giving myself time to think.  There are so many ideas to chase down, so many angles to look at, its easy to spend all one’s time doing and no time thinking about what else you might be doing.

It was that thinking that brought me to the idea about Pacific Ethanol, which I wrote about here.  Pacific Ethanol was a story that I had been reading posts on the Investorshub message boards for a while, but because I hadn’t really stopped to think about the idea, it remained just a stock that I didn’t understand that kept going up. Read more
Pacific Ethanol – Cyclical Turn?

Over the years I have had pretty good luck catching cyclical businesses at the turn of a cycle.  One of my first really successful investment ideas centered around the turn in copper prices in 2003-2004.  I ended up with multi-baggers in Aur Resources and Hudbay Minerals.  I caught the move in metallurgical coal in 2007-2008 and saw similar results from Western Canadian Coal and Grand Cache Coal.  In 2010 I latched on to a turn in the pulp cycle and saw 3-baggers from Tembec and Mercer International.  More recently I took advantage of the turn in trucking with a double from Frozen Food Express and of course YRC Worldwide, where I was able to make 6x my money in about 4 months.

So cyclical businesses can pay off big, but you have to time them right and never forget that they are cyclical businesses; what can seem like very easy come can also be just as easily gone.  Nevertheless, the upside can be quite large, because most of these businesses are low-margin commodities where relatively modest changes in prices can have a large impact on company margins.

A Turn in the Ethanol Business?

I’m still in the middle of looking at Pacific Ethanol so take what I’m writing here with a grain of salt.  There may be elements of the thesis that I am missing.  Nevertheless the idea seems promising and it appears, at least so far, to fit with the theme of a cyclical business on the cusp of a turn. I’m throwing this post out now because the stock is moving quite quickly and I am looking for feedback to fill the holes and solidify the idea for me. Read more

Week 127: A couple of new stocks and getting rid of a few others (JONE, MHR, PXL.CA, DGIT, TROX)

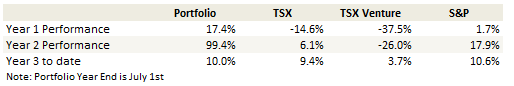
Portfolio Performance

week-127-yoyperformance

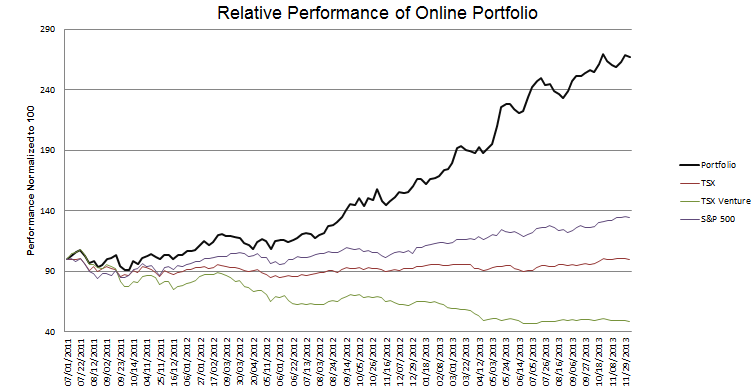
See the end of the post for the current make up of my portfolio and the last four weeks of trades.

week-127-Performance

Recent Developments

I don’t have a lot to say about the macro picture or generalized musings about my portfolio this month. The macro continues to be a party-on atmosphere so I guess we’ll keep dancing. My portfolio is still not performing as well as I would like but I don’t have any insights into why that is or what I should do different. I had a very good first seven months of the year, and now I am having a lull. These things ebb and flow. Onto the stocks.

Adding Jones Energy (JONE)

I really like this stock. It’s a recent IPO (it went public at the beginning of August), I don’t think it’s well covered or known by many, but it looks to me like they have been drilling extremely profitable gas-condensate wells in the mid-continent, and they have plenty of undeveloped acreage to drill more. I took a big position in it right off the bat at 6%. Read more

New Position in Cherry Hill Mortgage (CHMI)

I was going to put this in my update post but its gotten a little long so I thought I’d pop it out on its own.  I’ve talked a lot about New Residential and how much I like mortgage servicing rights as a play on a stronger economy and on rising rates. Well a few weeks ago a fellow who follows the blog wrote me about Cherry Hill Mortgage, a company that, like New Residential, is a REIT that holds mortgage servicing rights.   It took me a few weeks to find the time to look at the company and another week afterthat for it to really sink in just how cheap it was comparatively. But once it did I felt compelled to take a position.

It was a bit of unfortunate timing; I had to sell about 25% of my (albeit unreasonably large) position in New Residential to fund the purchase.  I wasn’t comfortable going on margin to fund the purchase.  So I took that New Residential position down from 20% to 15%.  Of course the day after I sold New Res at $6 the stock popped to $6.30. Maybe my sacrifice to the gods of trading was appreciated.

Nevertheless, in the long run I hope to be well compensated for my position in Cherry Hill.  Cherry Hill is being spun out of the mortgage originator Freedom Mortgage.  Soon after the IPO, the company purchased two pools of mortgage servicing rights from Freedom Mortgage. I ran some quick numbers and it looks like the company paid a reasonable price for these assets. In the table below the assets have been valued at cost: Read more