When I started to write this post a couple of days ago, Newcastle had a single $44M investment in mortgage servicing rights. On Tuesday the company announced a second MSR deal worth significantly more ($170M). Rather than have to re-write my post from scratch, I am instead going to focus here on the original $44M MSR deal. I will look at the larger, subsequent deal in another post.
Newcastle and MSR’s
I got interested in MSR’s after having become a regular listener to the Lykken on Lending mortgage lending broadcast. I have listened to a number of episodes where the mortgage professionals on the program describe the disconnect in the mortgage servicing world right now and the opportunity it has created with mortgage servicing rights. I invested in both PHH and Newcastle with the hope that that I can capitalize from this disconnect.
I have already written extensively about what a Mortgage Servicing Right is in this previous post.
The first MSR deal
In both their first and second forays into the mortgage servicing rights, Newcastle made a deal with Nationstar. Nationstar is a mortgage servicing company. The specifics of the deal, as put forth by Newcastle in a recent presentation, are as follows:
- The deal is for the mortgage servicing right of a pool of mortgages with a $9.9B unpaid balance
- Nationstar will be the servicer of the loan portfolio and will invest alongside Newcastle, purchasing a 35% interest in the Excess MSR
- Newcastle will not have any servicing duties, advance obligations or liabilities associated with the portfolio
- Newcastle received a private letter ruling from the IRS that allows for treatment of an Excess MSR as a good REIT
- Asset and the income that Newcastle generates from the deal will qualify as REIT income and not be subject to double taxation
The mortgage servicing right for the package of mortgages is, on average, 35 basis points per year of the unpaid balance. Of that 35 basis points, 6 basis points will go directly to Nationstar to cover the cost of the servicing. The other 29 basis points will be split between Newcastle and Nationstar 65/35.
It’s a good deal for both companies. Nationstar participates in a much larger mortgage servicing package than they would have been able to purchase with their own cash. They also participate in some of the upside of the MSR. Newcastle gets a high return investment that does not require them to develop any mortgage servicing abilities in house.
The Upside
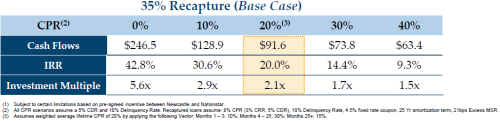
Newcastle says that they are expecting a baseline return from the investment of 20.9%. That’s a great number, but what I equally interested in is whether there is upside to that number.
In particular, Newcastle is assuming the following:
- 30% recapture rate. This means that Newcastle thinks that Nationstar can recapture 30% of the mortgages that go up for refinancing. If a mortgage goes up for refinancing and is captured by Nationstar, it remains in the pool. As Newcastle has suggested rather optimistically on their conference calls a couple of times, if you could recapture 100% of the mortgages that go to refinancing, you would have a perpetual money making machine
- 20% CPR. CPR stands for Constant Prepayment Rate. This term defines the number of mortgages that go up for prepayment short of their term. There are two reasons a mortgage will be prepayed early. Either the owner refinances or the owner defaults on the loan
Its worth pointing out that so far the 1 month CPR on the pool of mortgages Newcastle has purchased is 9.7%. The 3 month CPR is 7.3%. However, you have to expect that the CPR is going to increase rather substantially over the next couple of years. Why? Because of the government’s HARP II program, which allows homeowners with upside down mortgages to refinance those mortgages. Presumably this program is going to garner a lot of interest from folks with high loan to value amounts and you are going to see a refinancing spike.
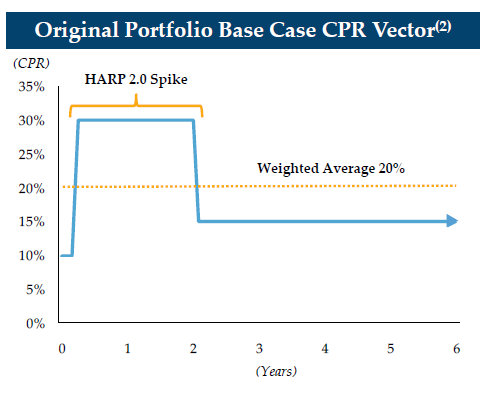
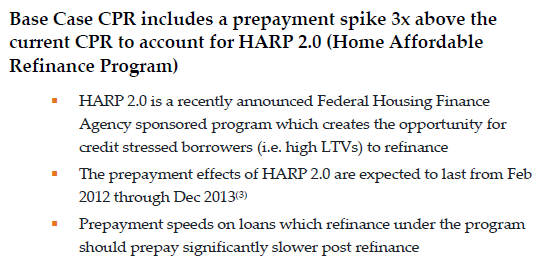
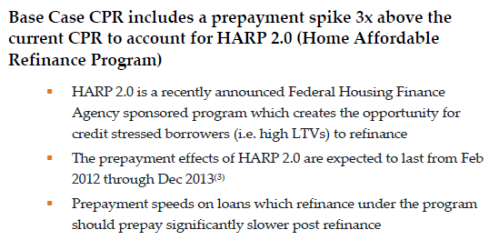
Newcastle has actually modeled the effect of HARP II assuming a spike in prepayments to 30% for the duration of the program (until December 2013). That 20% number that I mentioned is actually a weighted average over the life of the MSR’s. Newcastle provided the following chart to show how they are accounting for the spike in refinancings expected due to HARP II.
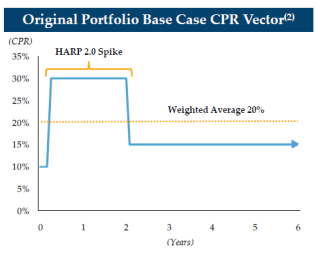
Newcastle also provided the following HARP II assumptions in the appendix:
Modeling the Baseline
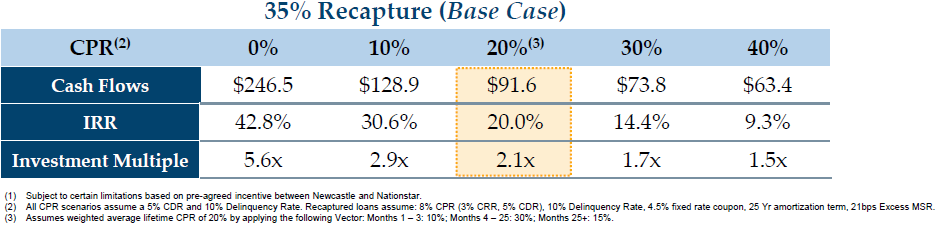
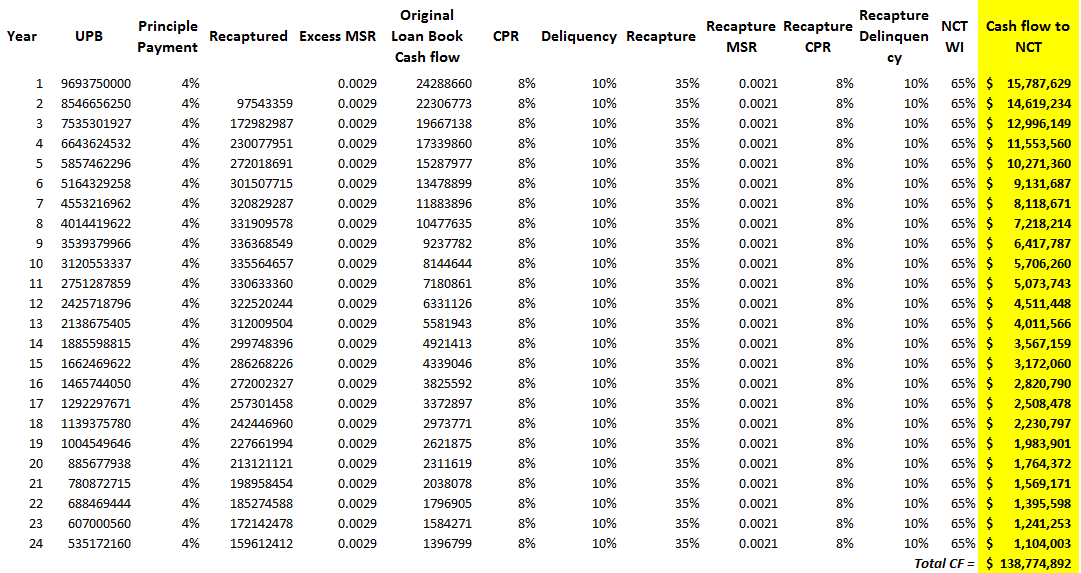
I always find it useful to create my own models, so that I can understand the dynamics at play and see what the cash flow really is. I started off by trying to match to the baseline assumptions put together by Newcastle. That scenario and the assumptions provided by Newcastle in the footnote are below:
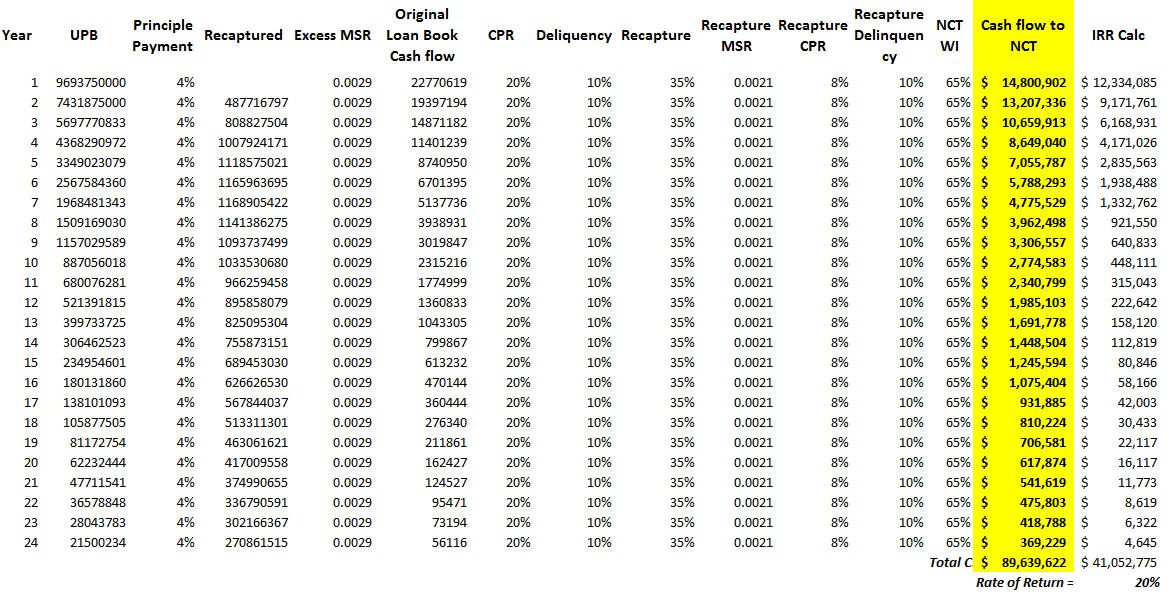
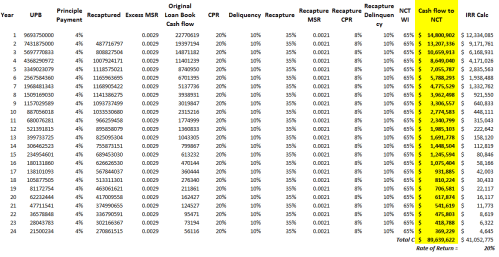
My model came up with the following:
Model Validation
How close is my model to the model that Newcastle is using? The primary differences between my model and the one Newcastle is using are that my model is done yearly (versus a monthly model completed by Newcastle) and I did not try to break out the increase in CPR due to HARP II, instead just using the weighted average 20% throughout the entire period modeled.
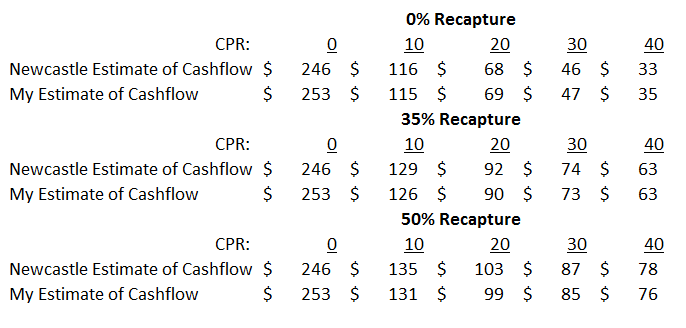
I made a comparison of the cash flow estimated by my model for each of the scenarios that Newcastle illustrated on Slide 8 of their presentation. My results along with the original Newcastle estimates are shown in the table below. All amounts are in millions.
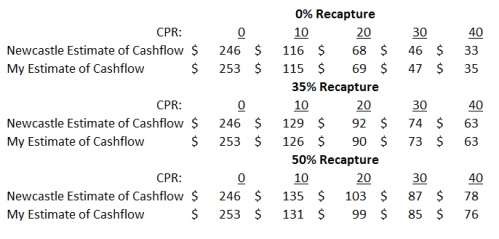
Close enough.
What does the model tell us?
The first point illustrated by the model is how much the cash flow changes from year to year. This is not a fixed return investment. The cash flow from an MSR is heavily weighted to the front end. The Year 1 and Year 2 cash flow decrease substantially as you move forward. While its always good to get paid out quickly, it also means that we have to be careful with respect to what we define as a sustainable dividend based on that cash flow. I’m not entirely sure whether a REIT like Newcastle has any say in the matter (they may just have to distribute 90% of their cash flow irrespective of how that cash flow stream may decline in the future, I’m not sure, I haven’t done the work to understand the rules of the REIT structure in the US carefully). But if Newcastle pays out the full $14M+ in the first year, the cash flow stream is going to decline substantially in subsequent years and Newcastle is going to have to find equivalent return investments to sustain that cash flow.
Investments that return 30%+ of capital in the first year don’t exactly grow on trees.
The second point is simply that the dividend hike should be significant. At even $12M, that is a hike of 12 cents per share, or 20% higher than the current 60 cent dividend.
A closer look at the upside
There are two potential sources of upside on the MSR’s.
- If there are fewer homeowners that refinance than the baseline scenario estimates than the cash flow stream goes up
- If more of the refinancing homeowners are retained than the baseline scenario estimates than the cash flow stream goes up
Newcastle already looked at the sensitivity to cash flow in their presentation, but they only showed a cumulative cash flow comparison. I am interested in seeing what the cash flow is in those first couple of years, because that is what is going to influence the dividend in the short term.
Let’s look at the first case.
To pick a rather significant deviation from the base case I am going to assume that the total CPR, so the total number of mortgages in the mortgage pool that refinance, comes in at 8% rather than the 20% weighted average assumed by Newcastle.
If this occurs I get the following cash flow profile.
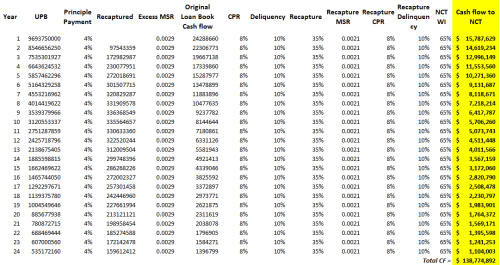
Note that the ROR increases to about 40%.
What is interesting is that the scenario shows how, as one might expect, the cash flow in later periods is effected much more than the cash flow in the earlier periods. This makes sense as I am really just adjusting how many of the original borrowers are lost in subsequent years.
So the conclusion that can be drawn is that changes in the CPR affect the later years cash flow, but they do not influence the current year’s cash flow significantly. While my analysis was done at lower CPR’s, the same can be said if you looked at a much higher CPR. Assuming that Newcastle is strictly bound to pay out a dividend on this years cash flow, that dividend would be similar under a wide range of CPR scenarios. Of course the sustainability of that dividend could fairly widely depending on the actual CPR that occurs.
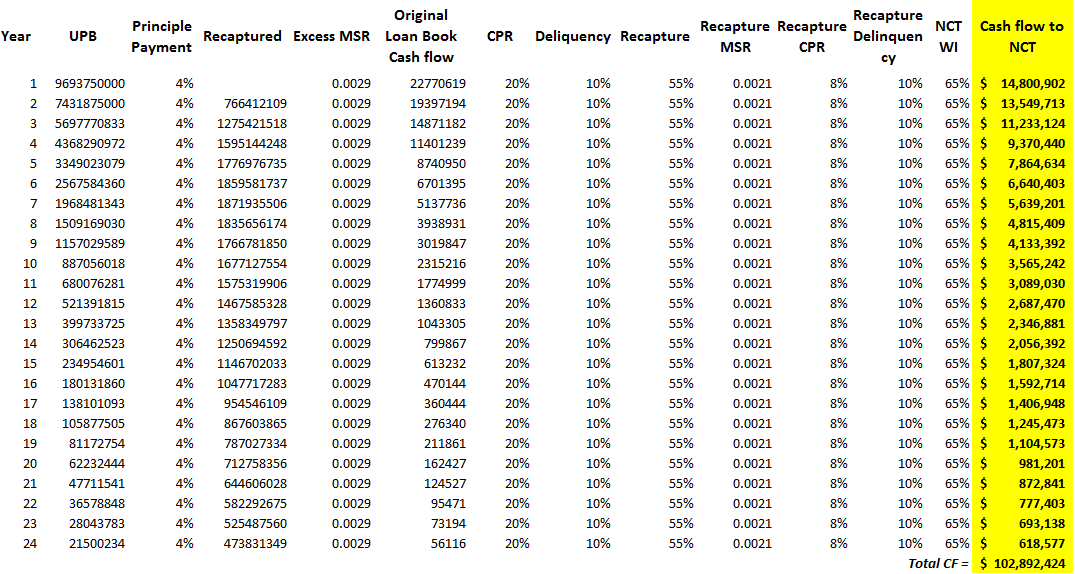
In the second scenario I am going to assume that the recapture rate ends up being significantly higher than the 35% estimate that Newcastle assumes. I’m going to assume 55%.
How valid is this? Funny you should ask. As chance would have it Nationstar is doing an IPO at the moment. As part of the IPO prospectus the company had the following to say about its recapture rate:
A key determinant of the profitability of our primary servicing portfolio is the longevity of the servicing cash flows before a loan is repaid or liquidates. Our originations efforts are primarily focused on “re-origination,” which involves actively working with existing borrowers to refinance their mortgage loans. By re-originating loans for existing borrowers, we retain the servicing rights, thereby extending the longevity of the servicing cash flows, which we refer to as “recapture.” We recaptured 35.4% of the loans we service that were refinanced or repaid by the borrower during 2011 and our goal for 2012 is to achieve a recapture rate of over 55%. Because the refinanced loans typically have lower interest rates or lower monthly payments, and, in general, subsequently refinance more slowly and default less frequently, these refinancings also typically improve the overall quality of our primary servicing portfolio.
So its a valid target. Here are the numbers at 55%:
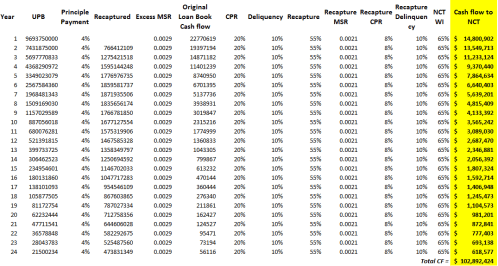
The cash flow really isn’t that sensitive to changes in the recapture rate. The change in cumulative cash flow is about $10M over the 24 year period. The change in IRR is between 2% and 3%.
What are the assets?
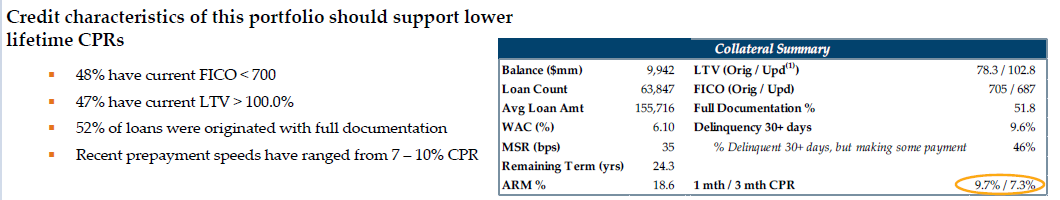
The last thing I looked at were the assets involved in the transaction. Newcastle provided, as a supplement to their mortgage servicing presentation, a summary of the assets that were acquired in the original Newstar deal.
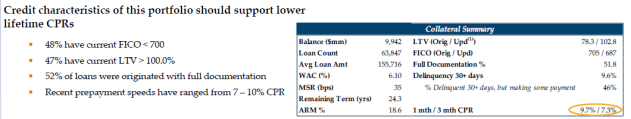
The loan package has a decent but not great average FICO score of 687. Typically, subprime has been considered to be below 640, whereas FICO scores above 700 are considered to be excellent lending opportunities. This loan package is somewhere in the middle.
I was a little surprised that full documentation loans only accounted for 52% of the loans in the package. I also am not sure what to make of the “% Delinquent 30 days but making some payment”. 46% seems to be an awfully big number, but maybe that is not uncommon? On the other hand, the one and three month CPR seems to be quite good, and the high loan to value, meaning that the loans are basically the same value as the house right now, will make it more difficult to refinance in the future.
The bottomline is that I need to investigate the asset quality further, and to some extent, just watch closely how it plays out. I’m still learning this whole mortgage business, and so I have more questions than answers right now. I’ve raised a few questions here, and I will report back when I have some answers.
Bottomline
The bottomline is that Newcastle is getting a high return investment (IRR of 20% on the base case) that is going to pay out the majority of the cash in the first few years. The investment also has some upside if the refinancing surge predicted to coincide with the HARP II program falls flat. There is also upside if interest rates rise, making refinancing less attractive to borrowers.
The investment should allow Newcastle to make a substantial dividend increase (one that should increase even more with the announced second MSR deal that has been made). In the recent past it appears that the stock price of the company has followed the dividend reasonably closely; when the hike to 60 cents was made the stock moved quickly into the $5-$6 range. A hike to 72 cents is likely based on the first MSR deal alone. I haven’t worked through the numbers on the second MSR deal but I imagine a substantial hike higher is in the cards.
In my opinion the company has proven themselves extremely shrewd by getting into the MSR business when they did. I have pointed out in the past that much of the buzz in the mortgage brokerage business right now is around how MSR’s are trading ridiculously cheap and how can one get into the business. Lykken on Lending, a radio broadcast I have mentioned in the past, has done 4 programs in a row dedicated to understanding the MSR industry. Every one of those broadcasts (the last of which was so good that I plan to do a short synopsis of tomorrow) reiterated the point that the opportunity in MSR’s right now is unprecendented. The quality of the loans has never been better, the refinancing surge over the past couple of years makes it likely that those loans will stay on the books for longer, and the prices for MSR’s are trading at extremely low multiples, a disconnect that has been caused by so many of the big banks getting out of the busines (Bank of America, which was previously the largest mortgage servicer, being the most commonly sited example).
Newcastle may not be a 10 bagger, but with a 10% payout right now and a high payout coming, I think it will prove to be a very profitable investment for me.
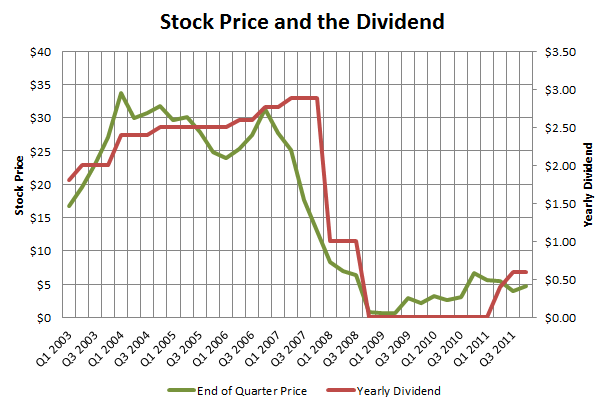
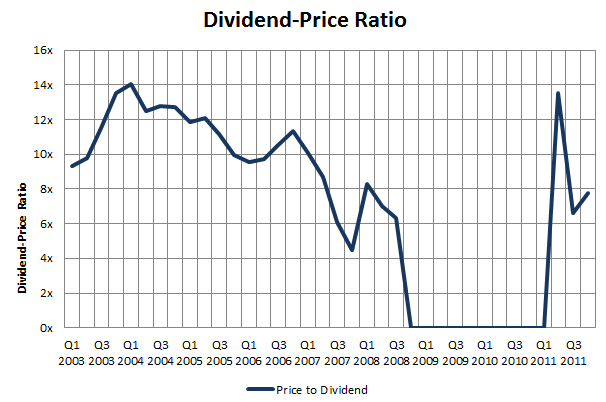 I haven’t run the numbers in full on the second MSR deal that Newcastle announced. Until I do I won’t be able to say what I think the dividend will eventually be. But to ballpark, based on a sustainable cash flow of 10 cents per share from the first dividend, and given that the second deal is roughly 4x larger than the first, I think that a sustainable dividend in the 80-90 cent range is not unreasonable. Tacking on a 10x to 12x multiple and we get a share price range of somewhere between $8 and $11.