Skip to content

Week 173: Done for now

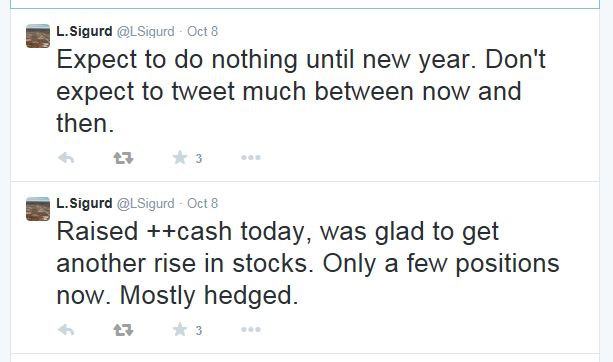
Two weeks ago I made the following tweets describing my latest and last investment decision:

finaltweets

I meant to get around to writing a post acknowledging the same sentiments but I never did until now.  Since that time I have watched the market go down a lot and then come all the way back up.  I haven’t done much of anything during the whole see-saw.

And that is because I think I’m done.  I have a lot of cash, a few positions and no plans to chase anything up or even add to anything as it comes down.  Maybe when the Fed (or perhaps the ECB) decides to get back into the game I will change my mind. But for now I don’t really have a strong inclination to do anything.  So I’m going to walk away while I’m ahead.  Maybe there will be a better set-up in the future.  But until then…

Good-bye.

Betting some more on BXE

My portfolio had a tough week and has had a weak September.  As it goes when I show weakness, I am quick to clean house and start anew.  This week I jettisoned a number of names (including Sherritt, Mart, Straight Path Communications and Aercap), made a number of positions much smaller (including Overstock, IDT, Transat, Sanderson Farms, and Supercom) and raised a bunch of cash.  When the dust settled I had 10 positions remaining of significant size.

One of those positions is Bellatrix, of which, in the midst of oil and gas carnage everywhere, I bucked the trend and added to this week.  This after I had mentioned in a tweet a couple weeks ago that a recent add would be the last one.

Well I lied.  With the stock dropping to the mid-$6’s I decided to revisit the whole idea, and after doing so, I added fairly aggressively.  I do not make this decision lightly; as I have written before, once I have a full position I rarely add to it if it starts losing money.  There’s just too much chance that I am wrong.  At the time of the tweet Bellatrix was a 4% position for me.  Its now the largest position in my portfolio at 12%.  My average cost base is down to around $7.17.

Why was I willing to add so significantly?  Because the work I did helped reassure me that my original idea is most likely correct; that the company is suffering from a short to medium term processing bottleneck that should be alleviated by the commissioning of their own plant in mid-2015.

Most of my work focused around a production/decline model that would help give me a better idea of how production should trend under various drilling scenarios and capacity constraints.

My model is simplified, but not too simplified. I think that oil and gas models are some of the most difficult to make.  The inputs require estimates of decline rates, which changes over the life of each of the wells in the field, drilling schedules, which are impacted by weather, rig and processing availability, and in the case of the Western Sedimentary Basin, by spring break-up.  There are so many difficult to determine parts that I think it is better that one not try to confuse precision with accuracy.

Read more
Week 168: Cutting my gains

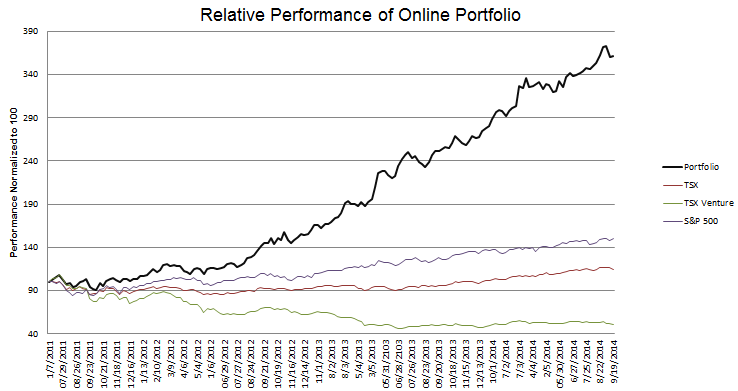
Portfolio Performance

week-168-Performance


See the end of the post for the current make up of my portfolio and the last four weeks of trades.

Recent Developments

I don’t know if the chart of performance really does justice to the volatility my portfolio has had over the last couple of weeks.  It feels like much more of a roller coaster than that little blip in the trend that you see on the screen.

I sold out of the rest of Pacific Ethanol and Rex American Resources in the first half of this week.  I hemmed and hawed through the weekend, even briefly added to my position to Pacific Ethanol on Monday (at the same time I was reducing my position in Rex American), but the volatility of the stocks, the declining price of ethanol, and specific to Pacific Ethanol, my uncertainty with respect to their corn basis (I concluded tentatively it is actually quite a bit higher than Q2) led me to capitulate on many of my shares on Tuesday.  I followed that up by selling the rest on Wednesday in the minutes that followed a very bearish EIA inventory report (+800,000bbl!). I tweeted on my sales at the time.

My caution turned out to be fortuitous as the stocks continued to fall the rest of the week.  I was even able to catch a few dollars of profit on the way down; always remembering the old classic to which this blog takes its namesake, I took the lesson that if a stock is to be sold it is likely just as well sold short, and so I took a small short position in Rex American and a few $18 puts on Pacific Ethanol.  The puts were sold Friday and my short position has been cut more than in half, so these were merely short term trades taking advantage of a clearly bearish dynamic. Read more

Adventures in Ethanol

Over the last week I have played some parts of the ethanol yo-yo well and other parts not so well. Let me review.

On the well side, I significantly reduced my extremely over-sized position in Pacific Ethanol (25% of my portfolio at its peak) at prices of about $23 per share.  On the not-so-well side, I added/subtracted and then added back my position in Rex Energy on continuously declining prices and held on to a still not insignificant percentage of Pacific Ethanol (about 5% position) through the declines of Thursday and Friday.  What is yest to be determine is that I added back some of Pacific Ethanol at $20.15 on Thursday. While I sold half of that on Friday morning for a bit of a profit, I held the other half through the decline on Friday and now sit with those shares at a lower price than I had purchased them for.

How this all ends remains to be seen.  This blog is not intended to be an account of my infallibility. Unlike many others on the blogosphere and on twitter, I have no omniscient insight into what can be absolutely stated as a good or bad decision.  Thus it is that you rarely see me laying out the ridicule, condescension or my favorite, the passive-aggressive rhetoric, that seems to be so prevalent in these mediums.  I can only wish for such certitude.  Unfortunately my world is far too gray to not feel empathetic for those who hold a different opinion than mine.

The beauty and horror of the ethanol stock is that it only takes a small difference of opinion to lead to a drastically different conclusion.  To take an example that I tweeted earlier tonight, in my model I get a $1 quarterly earning swing by adjusting the ethanol price by 20 cents – from $2.05 to $1.85 per gallon (note I originally had written 80c but I hadn’t been making an apples to apples comparison in my model).  A similar point could be made about Pacific Ethanol.  The significance of course is that 20 cents is about the swing that ethanol prices took in the last week. Read more