Skip to content

Taking advantage of the disappointment with Bellatrix

This is a company I should have owned 12 months ago when I was looking around the Canadian oil and gas universe but instead pissed around trying to buy the cheapest thing.  When investing in an oil and gas company buying the cheapest thing is simply not the way to make money.  I’ve been investing in the sector for 10 years now; every time I walk away and return I have to learn that lesson again.  Hopefully that will end now.

Bellatrix Exploration (BXE) is simply a company with lots of land in very prospective areas and a history of being able to grow production on a consistent basis. The stock is on sale because of a bungled private placement and I think that presents an opportunity.

Background about the company

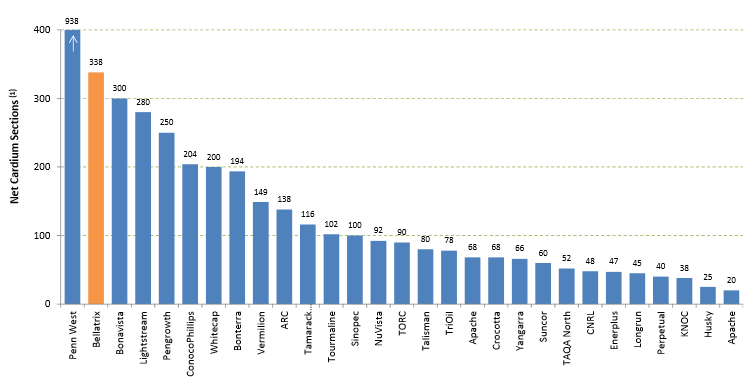
Bellatrix owns one of the largest positions in the Cardium (in Alberta) in the industry.
 

land_holdings


They’ve proven they can develop that land in an efficient manner.  The company has grown its production the last 4 years and expects another strong year of growth in 2014 (note though that the 2014 production number is being buoyed by the acquisition of Angle Energy, which closed late last year). Read more
A New Bet on Hercules Offshore

I have owned Hercules Offshore (HERO) for a couple of weeks now.  I tweeted about my position right after I bought the stock.  I think the stock has been hit too hard on concerns about drilling rig supply/demand and that a change in sentiment could send the stock back up to the $6 to $8 range.

Hercules performs drilling services in the offshore market.  Their focus is shallow water drilling; their marketed fleet consists of 27 jackup rigs and 23 liftboats.  Fifteen of their jackup rigs are contracted in the Gulf of Mexico with the rest located internationally in the Middle East, Southeast Asia and Africa.  In 2013 jackups made up 83% of revenue, with the liftboats taking the rest.

Why I took a position

I took a position in Hercules based on the following:

  1. The stock was hit pretty hard at the beginning of the year because of concerns about supply/demand of new build jackup rigs and the impact this could have on Gulf of Mexico day rates
  2. Those concerns have some validity but are not immediate.  For 2014 the new supply (32 rigs total, 24 rigs that aren’t contracted) will be absorbed by the market.
  3. Looking out to 2015 there is significant supply of new builds but much of the supply is being ordered on spec and by buyers who are not established operators.  It remains to be seen how much is built or who will operate it if it is built.
  4. The Gulf of Mexico is also not the most profitable destination for a new build, which should help insulate Hercules from the new builds to some degree
  5. The current price of the stock (I add at $4.50 but its now a bit higher at $4.80) reflects the concern about supply/demand and very little optimism that day rates will remain strong in 2014 and continue to hold up for 2015
  6. Hercules is quite levered (their market capitalization is around $700 million and they have $1 billion of net debt) so a small change in sentiment about the company (either via a reappraisal of the Gulf of Mexico situation or one of the other catalysts I will get to shortly) can have a big effect on the stock.
  7. Based on the first quarter results the stock is trading at a reasonable 4.5x EV/EBITDA multiple

Read more

Week 153 Update: Investing by a Thread

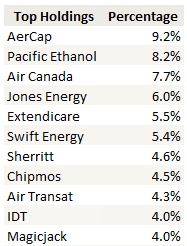
This is not a full update of my portfolio so I will not be providing all the details of my current positions and trades over the last few weeks.  I’ll do that again in the next week or two. Below are my current top 10 holdings and their percentage weighting in the portfolio.

06-07-14 topholdings

In this post I want to write about the tenuous nature of most of the stocks I hold.   While I make many purchases based in part on the judgment that an undervaluation exists, I’m not really a value investor in any strict sense of the definition.  I don’t really look for stocks that are simply cheap to their intrinsic/discounted/net asset value and then wait for something to happen to change that.

In addition to cheap I’m always looking for a catalyst.  Something that will change perception of the stock and where the stock has enough leverage to the change to make for meaningful upside.

Because of these two criteria I find that I am drawn into an inordinate number of cyclical, indebted, tenuous or heavily capital dependent businesses.  They are not great businesses over the long-run.  Their true value is usually wildly erratic depending on the assumptions used.  While this characteristic represents the opportunity it also means I have to continually re-evaluate the thesis and sometimes admit that I am wrong and give up. Read more

The upside is not reflected in King Digital

I added a new position in King Digital Entertainment (KING) this week.

I discovered the company while perusing through 13-F filings.   I search for hedge funds that have performed well in the last few years and look for tickers of either large or growing positions in those funds.  I found King via a fund called Steadfast Advisors.

King Digital is out of my usual area of competence.  The company is a video game developer and I have never invested in a video game developer before.  I’m not much of a gamer.  Nevertheless the company is extremely well-priced for scenarios outside of a collapse of the business, and I am an avid opportunist of market inefficiencies.

King is also a busted IPO.  The stock priced at $22 in March and is now $16.  The timing of the IPO was bad, both in terms of the market and the business.  It was a bad time for the market because tech has taken a pounding.  It was a bad time for the business because the biggest grossing game (by far) in the history of the company, Candy Crush, was beginning to go into decline. Read more