Skip to content

Tracing out Nordion

I’m going to start this post with a short summary of why I took a position in Nordion.  I tweeted the following at the beginning of January after establishing a position in the stock.

ndztweet

As I briefly explain in the tweet, Nordion has about $323mm of cash and another $40mm of restricted cash on their balance sheet.  They have $41 million of debt.  There are 61.9 million of shares outstanding. I bought the stock at a little over $10, so at an enterprise value of a little under $300 million. Read more

Week 135: Retail Changes

Portfolio Performance
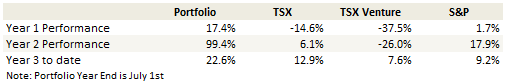
week-135-yoyperformance

See the end of the post for the current make up of my portfolio and the last four weeks of trades.
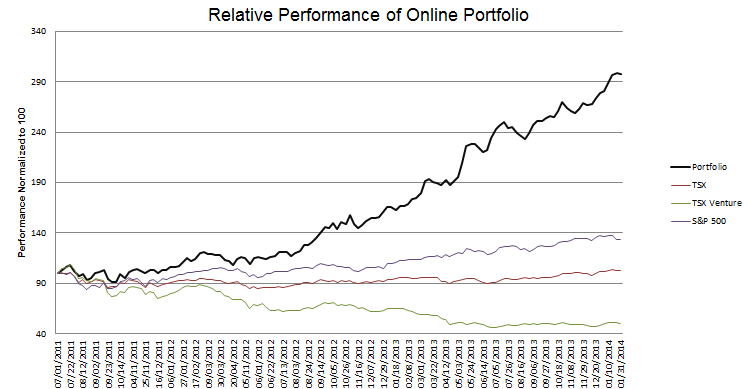
week-135-Performance

Recent Developments

During the Christmas break I began to focus my attention on the Canadian market, searching out stocks that had not yet participated in the bull market or that had further room to run.  I started to call these stocks my “Venture” ventures but that is not really accurate; I’ve actually only invested in a couple of companies that trade on the Venture exchange.  But they do tend to be small and micro and even nano cap companies, so many of them are Venture in spirit if not name.

My thesis was based upon a few pillars.  First, the Canadian markets severely underperformed the US markets in 2013 and given the tie between the trade of the two countries I didn’t think this disconnect could continue forever.  Second, The Canadian markets were dragged down by a rout in commodity stocks, particularly gold, and I wondered how much of the general downdraft had resulted in non-commodity businesses being dragged down unfairly.  Third, the Canadian dollar had fallen 10% and I had to think that this made any kind of export based business much more attractive.

The fall of the Canadian dollar also provided me with another reason to return to my home-country market.  I have done really well in the past year owning stocks in American dollars.  Its been a 10% gain across the board, even if a individual stock did nothing. But this force can work two ways and I am wary of a 5% correction to the upside that causes my portfolio to take a hit. Read more
An LNG Venture: Macro Enterprises

Back in the summer I bought a company called Entrec whose business was to provides large cranes and heavy load transport services.  My purchase was based on the thesis that there would be increased demand for these kind of services as the liquefied natural gas terminals began to be built along the BC coast.

Well I still believe that this thesis plays out over the next couple of years and Macro Enterprises (MCR) is my second endeavor under its umbrella.  Macro provides pipeline and facilities construction services in Northern Alberta and British Columbia.

Macro should benefit from the construction of the LNG facilities anticipated over the next few years. There were a couple of good articles written by ARC Energy’s Peter Terzakian with respect to the opportunity presented by LNG development (here and here).  Terzakian quantified the magnitude of the impact of LNG spending as follows:

If three projects get the green light, the implied wave of capital crests at $16 billion per year in 2017. Let’s consider some comparative perspectives. Spending by oil and gas companies in BC is typically only $6 billion a year, so the magnitude of what’s to come could be nearly triple at the peak. How about the speed of the wave? What happened during Alberta’s early oil sands development provides a comparative vignette: Three LNG projects will generate a steeper spending swell than what the Fort McMurray area experienced a decade ago. Read more

Sherritt and the Indonesian Nickel Ban

I spent my free time during the last couple of days reviewing Sherritt International.  I wanted to get some more clarity on my investment and come to a conclusion about the size of the position that I should have.  As I have talked about in the past, my free time is limited and so my upfront research on names can be less than complete.  I usually take small starter positions, between 1-3%, and then increase the size of those positions once I have had time to digest and review the idea in more detail.

As I tweeted last week, there were a number of catalysts that led me to take a position in Sherritt:

After digging deeper into the name, the conclusion that I came to is that Sherritt is really a play on nickel.  I think that as goes the price of nickel, so goes Sherritt. Read more