Skip to content

Arch Coal: Taking a Side on an Uncertain Outlook

I bought Arch Coal (ACI) last week on the thesis that the rise in natural gas prices along with the colder than expected March would lead to a change in perception from investors about the coal market.  I added to that position on weakness this week and now have what I would consider a full position (which is still only moderate in size because, as I described last week, my confidence in the natural gas thesis is somewhat tentative).

On Thursday I was pleased to see comments from Peabody Energy (from Seeking Alpha) that will contribute to the perception shift.

Now turning to the U.S. market, we have seen a dramatic improvement in coal fundamentals from this time last year. We now project 60 million to 80 million tons of increased coal demand in 2013 as the industry reclaims the majority of demand lost in 2012 to natural gas.

Within the U.S. market, winter was 17% colder than last year and natural gas prices have more than doubled from last April driving a 15 million ton increase in the first quarter coal burn at the same time the gas generation dropped 11%. Coal now accounts for approximately 40% of total generation, while gas has fallen to 24%. The supply side of the equation was also favorable in the first quarter as U.S. coal shipments fell 10%.

The end result is that PRB and Illinois Basin stockpiles have improved 20% over the last year, and over the next five years, we expect the low cost PRB and Illinois Basin demand to grow more than 125 million tons to a greater capacity utilization and regional switching, and this is after taking into account an estimated 60 gigawatts of retirements during that time.

You see U.S. generation only ran at 55% of full capacity in 2012. These plants can run much harder and utilities have invested more than $30 billion in new equipment over recent years to allow them to do just that. Read more

Some Conclusions on the Natural Gas Market

I have spent much of my weekend researching the state of the Natural Gas market. In this post I am going to outline what I’ve learned and draw some tentative conclusions.

My interest in natural gas was piqued after the abnormally cold March that we’ve had and the coinciding decline in natural gas storage to below the 5 year average.

storage

Subsequently, after reading an article posted by @Dedwardssays on his blog and a couple of articles on Seeking Alpha, I took a position in Gastar Exploration (GST).  At the same time I added a call position in Exco Resources (XCO).   Since then I have added a small position in WPX Energy (WPX), which appears to have had a large Niobrara discovery in the Piceance Basin.  I also, of course, have held a position in Equal Energy (EQU) for the last number of weeks.  I am actively looking for undervalued natural gas biased companies producing the in the lower 48. Read more

Getting Comfortable with Walker and Dunlop

I was originally put on to the idea of Walker & Dunlop (WD) by a reader of the blog back in September (while I will leave the name of that tipster anonymous, many thanks for the idea).  The call was prescient and I can only wish I had made my purchases sooner.

As it was, I initiated a position in Walker & Dunlop about 4 weeks ago, doing so after the stock had fallen 10% from its 52 week high of $21.76.  Unfortunately that turned out to be at least $2 too soon.

The stock has subsequently fallen further.  As usual being wrong has compelled me to re-evaluate my thesis, which I did this week.  After some waffling I have decided not only to hold on to the position but add to it, which I did on Thursday and again on Friday.

What they do

Walker & Dunlop is the commercial lending equivalent of Nationstar Mortgage. Their business is the origination and servicing of commercial mortgage loans.  The vast majority of those loans are multi-family and are passed along to Fannie Mae, Freddie Mac or into HUD insured Ginnie Mae securities. The company generates revenue from origination fees and on the servicing of its loans.  They are the eighth largest originator of commercial mortgage loans in the United States, and the second largest originator of multi-family loans.

Extending the analogy to Nationstar, Walker & Dunlop recently acquired its fellow commercial originator CWCapital from Fortress Investment Group, who became a large shareholder after acquiring 11.6 million shares as part of the sale. Read more

Week 91: Consolidating

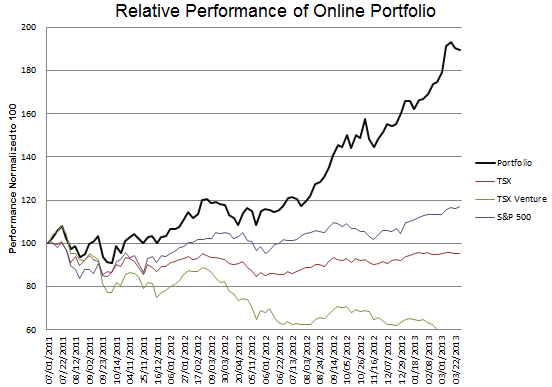
Portfolio Performance

week-91-Performance

Consolidation

Patience is a difficult virtue. I’ve had 3 weeks of pretty so-so performance, some stocks going up and some stocks going down and overall not much of anything happening. With the market going up seemingly every day its hard to not let that play on your mind.

But you have to have a balance of patience and impatience to do well in stocks. You need to have a healthy level of impatience so that you don’t hold onto positions for too long, but tempered with an equal dose of patience because, as I read some time ago from a cagey market veteran, you will make 80% of your gains for a year in 2-3 weeks, and figuring out which weeks those are is nearly impossible.

In the last few weeks I think I demonstrated a little bit both; witness impatience in my selling of gold stocks and of my position in Tricon Capital and patience as I held on to falling positions in MBIA, Impac Mortgage and watched YRC Worldwide and Yellow Media correct substantially from their highs. Read more